
From a strictly financial and functional perspective, an assistance animal represents far more than a companion; it is a high-value assistive asset that facilitates independence, productivity, and health for individuals with disabilities. While the emotional bond between a handler and their animal is profound, understanding “what is an assistance animal” through the lens of personal finance and business strategy is essential for anyone considering this significant life investment.
An assistance animal is a working animal specifically trained to perform tasks that mitigate a person’s disability. Unlike pets, these animals are categorized under various legal frameworks—such as the Americans with Disabilities Act (ADA) in the United States—as medical necessities rather than luxury goods. This distinction is the cornerstone of how they are treated in tax law, insurance claims, and personal budgeting.
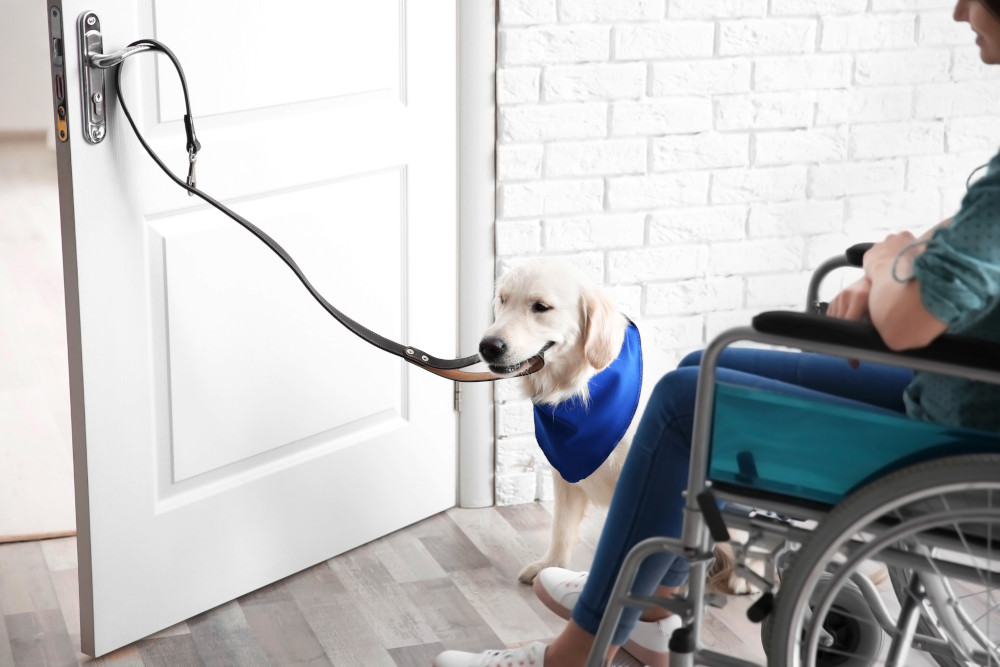
Defining the Assistance Animal as a Financial and Life Investment
To understand the economic footprint of an assistance animal, one must first categorize the animal correctly. The financial implications vary wildly depending on whether the animal is a service animal, a guide dog, or an emotional support animal (ESA).
The Legal Definition and Economic Value
Under the ADA, a service animal is defined strictly as a dog (or in some cases, a miniature horse) that is individually trained to do work or perform tasks for a person with a disability. From a financial planning perspective, this training transforms the animal into a “medical tool.” The economic value of this tool is measured by the degree of independence it provides the handler. For a professional, this may mean the ability to maintain full-time employment, navigate a corporate office, or travel for business without the need for a human personal assistant, which would carry a significantly higher recurring salary cost.
Distinction from Pets and Emotional Support Animals (ESAs)
The distinction between a service animal and an ESA is critical for financial auditing and tax purposes. While ESAs provide comfort, they are not trained for specific tasks and do not hold the same “medical necessity” status under many financial regulations. For example, the IRS generally allows the deduction of costs associated with service animals as medical expenses, whereas the costs for a standard pet or, in many cases, an ESA, are considered personal living expenses and are non-deductible. Understanding this distinction ensures that handlers are not only compliant with the law but are also maximizing their potential for tax relief and insurance reimbursements.
The High Cost of Procurement: Budgeting for a Professional Partnership
The acquisition of a high-quality assistance animal is a major capital expenditure. For many, the “sticker price” of a fully trained service animal can be a barrier to entry, necessitating a sophisticated approach to capital accumulation and budgeting.
Initial Acquisition and Specialized Training Expenses
A professionally trained assistance animal typically costs between $20,000 and $50,000. This figure covers the initial purchase of a candidate with the right temperament and genetics, two years of intensive boarding and training, veterinary oversight during the developmental phase, and the “matching” process where the handler is trained alongside the animal.
These costs reflect the specialized labor involved. Professional trainers are highly skilled experts who must ensure the animal can perform complex tasks—such as alerting to a seizure, guiding through heavy traffic, or detecting allergen traces—with 99% reliability. When viewing this as a business investment, the “unit cost” includes the high failure rate; not every puppy becomes a service dog, and the successful graduates must carry the overhead of the entire breeding and training program.
Comparing Professional Agencies vs. Owner-Trained Models
Some individuals opt for “owner-training” to mitigate the upfront cost. While this reduces the initial capital outlay, it increases the risk of “asset failure.” An owner-trained animal may take two years to reach proficiency, during which the handler invests thousands of hours in labor. If the animal “washes out” (fails to complete training) due to temperament or health issues, the handler faces a 100% loss of the invested time and training resources. Conversely, working with an accredited agency often provides a “replacement guarantee,” functioning much like an equipment warranty, where the agency provides a successor animal if the first one cannot perform its duties.
Ongoing Maintenance and Hidden Operational Expenses
Much like any critical piece of infrastructure, an assistance animal requires ongoing maintenance to ensure it remains functional and healthy. These recurring costs must be integrated into a long-term personal financial plan.

Veterinary Care, Health Insurance, and Specialized Nutrition
The “operating costs” of an assistance animal are significantly higher than those of a pet. Because the animal’s health is directly tied to the handler’s safety and mobility, preventive care is non-negotiable. High-protein, specialized diets are often required to maintain the animal’s energy levels for long workdays.
Furthermore, health insurance for service animals is a vital risk-mitigation tool. A sudden illness or injury to a service animal is not just a personal tragedy; it is a functional breakdown for the handler. Specialized insurance policies often cover not only medical bills but also the costs associated with “loss of use,” which can help fund temporary human assistance or alternative transportation while the animal recovers.
Equipment and Working Gear Requirements
A service animal requires specific “hardware.” This includes specialized harnesses for guiding or mobility support, which can cost hundreds of dollars and require custom fitting. Other expenses include boots for paw protection in urban environments, cooling vests for high-temperature climates, and high-visibility gear for nighttime operations. From a budgeting standpoint, these items should be treated as depreciable assets that will need replacement every 24 to 36 months of active service.
Financial Strategies: Grants, Tax Benefits, and Funding
Given the high costs associated with assistance animals, several financial mechanisms exist to help bridge the gap between need and affordability. Navigating these requires an understanding of tax law and the non-profit sector.
Leveraging IRS Deductions and Medical Expense Accounts
In the United States, the IRS allows taxpayers to deduct the costs of buying, training, and maintaining a guide dog or other service animal for a person with a physical disability. This includes food, grooming, and veterinary care. These expenses are categorized as medical deductions under Schedule A.
Additionally, individuals with Health Savings Accounts (HSA) or Flexible Spending Accounts (FSA) can often use these pre-tax dollars to pay for service animal-related expenses. This can result in a 20% to 30% “discount” on the overall cost of the animal, depending on the individual’s tax bracket. For many professionals, utilizing an HSA is the most efficient way to manage the recurring maintenance costs of their assistance animal.
Non-Profit Grants and Community Fundraising
For those who cannot afford the $30,000+ upfront cost, the non-profit sector provides a secondary financial market. Many accredited organizations provide service animals at no cost or at a steeply discounted rate, funded by corporate sponsorships and private donations. However, the “cost” here is often time, with waitlists stretching from two to five years.
Alternatively, many handlers utilize crowdfunding or community-based fundraising. This requires a “marketing” approach, where the handler must effectively communicate the “return on investment” the animal will provide to their life and their ability to contribute to the community.
The Business of Accessibility: ROI and Long-Term Impact
While the costs are high, the Return on Investment (ROI) of an assistance animal can be astronomical when measured over the animal’s 8-to-10-year working life.
Mitigating Income Loss and Enhancing Productivity
For an individual whose disability might otherwise prevent them from working, an assistance animal is an “income-enabling asset.” If an assistance animal allows a handler to move from disability benefits to a $60,000-a-year salary, the animal pays for itself within the first year of employment. Furthermore, the presence of a service animal can reduce the frequency of medical emergencies or hospitalizations, leading to lower overall healthcare spending and fewer lost workdays. This increased productivity is a net positive for both the individual’s personal net worth and the broader economy.

The Future of Assistance Animal Funding
As the corporate world focuses more on Diversity, Equity, and Inclusion (DEI) and Environmental, Social, and Governance (ESG) metrics, we are seeing a shift in how assistance animals are funded. Some progressive employers are beginning to include service animal support in their benefits packages, recognizing that supporting a disabled employee’s assistive “tools” is a smart retention strategy.
In conclusion, an assistance animal is a sophisticated, high-value asset that requires a strategic approach to financing. By understanding the legal definitions, procurement costs, maintenance requirements, and available tax advantages, handlers can ensure that their partnership with their assistance animal is as financially sustainable as it is life-changing. Whether viewed as a medical necessity or a career-enabling investment, the assistance animal remains one of the most effective—and complex—assistive “technologies” available today.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.