
Becoming a medical doctor is one of the most respected and demanding career paths one can pursue. It is a calling that requires immense dedication, intellectual rigor, and an unwavering commitment to human well-being. However, beyond the noble ideals of healing and patient care, the journey to becoming and thriving as a medical doctor is inextricably linked with significant financial considerations. From the colossal educational investment to the strategies for wealth management and the intricacies of practice finance, understanding “what is a medical doctor” from a monetary perspective reveals a complex landscape of costs, returns, and strategic financial planning.
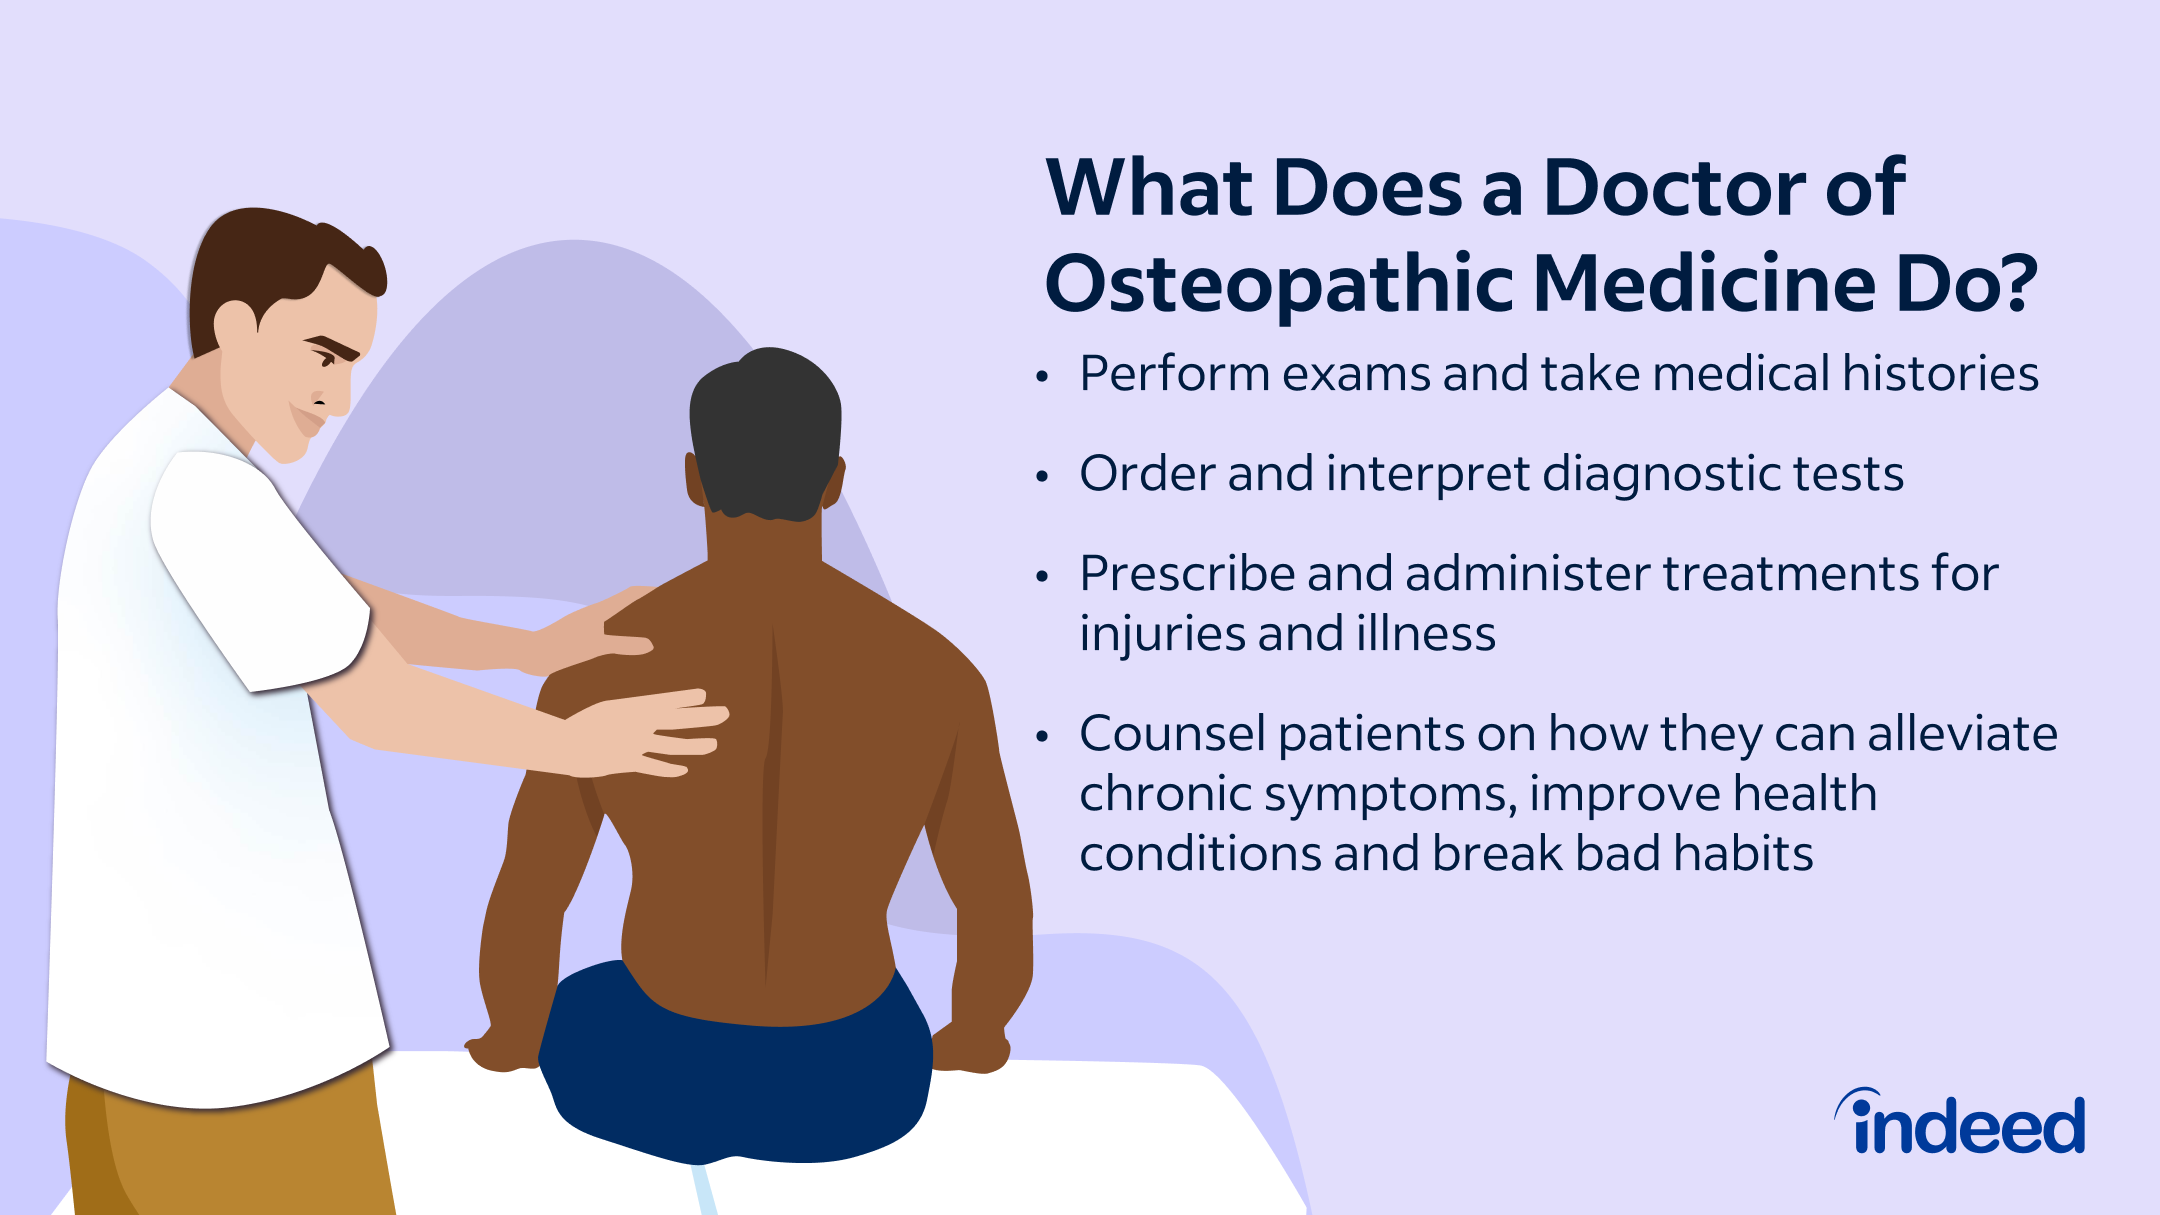
This article will meticulously explore the financial dimensions of a medical career, providing an insightful and professional perspective on the investments required, the income potential, and the unique financial challenges and opportunities faced by physicians throughout their professional lives.
The Formidable Investment in Becoming a Physician
The path to becoming a medical doctor is famously long and expensive, representing one of the most significant human capital investments an individual can make. This journey begins long before medical school and extends well into specialized training.
Undergraduate Pre-Med Costs
The foundation for a medical career is typically laid during a four-year undergraduate degree, often in a science-heavy field. While tuition fees for these programs vary widely based on institution type (public vs. private) and in-state vs. out-of-state status, the cumulative cost can be substantial. Students often incur significant debt at this stage, particularly if they attend private universities or do not qualify for substantial financial aid. Beyond tuition, there are expenses for textbooks, living costs, application fees for medical schools (AMCAS, AACOMAS, TMDSAS), and MCAT preparation courses, which can run into thousands of dollars. While not exclusively medical costs, these form the initial financial hurdle on the medical trajectory.
Medical School Tuition and Fees
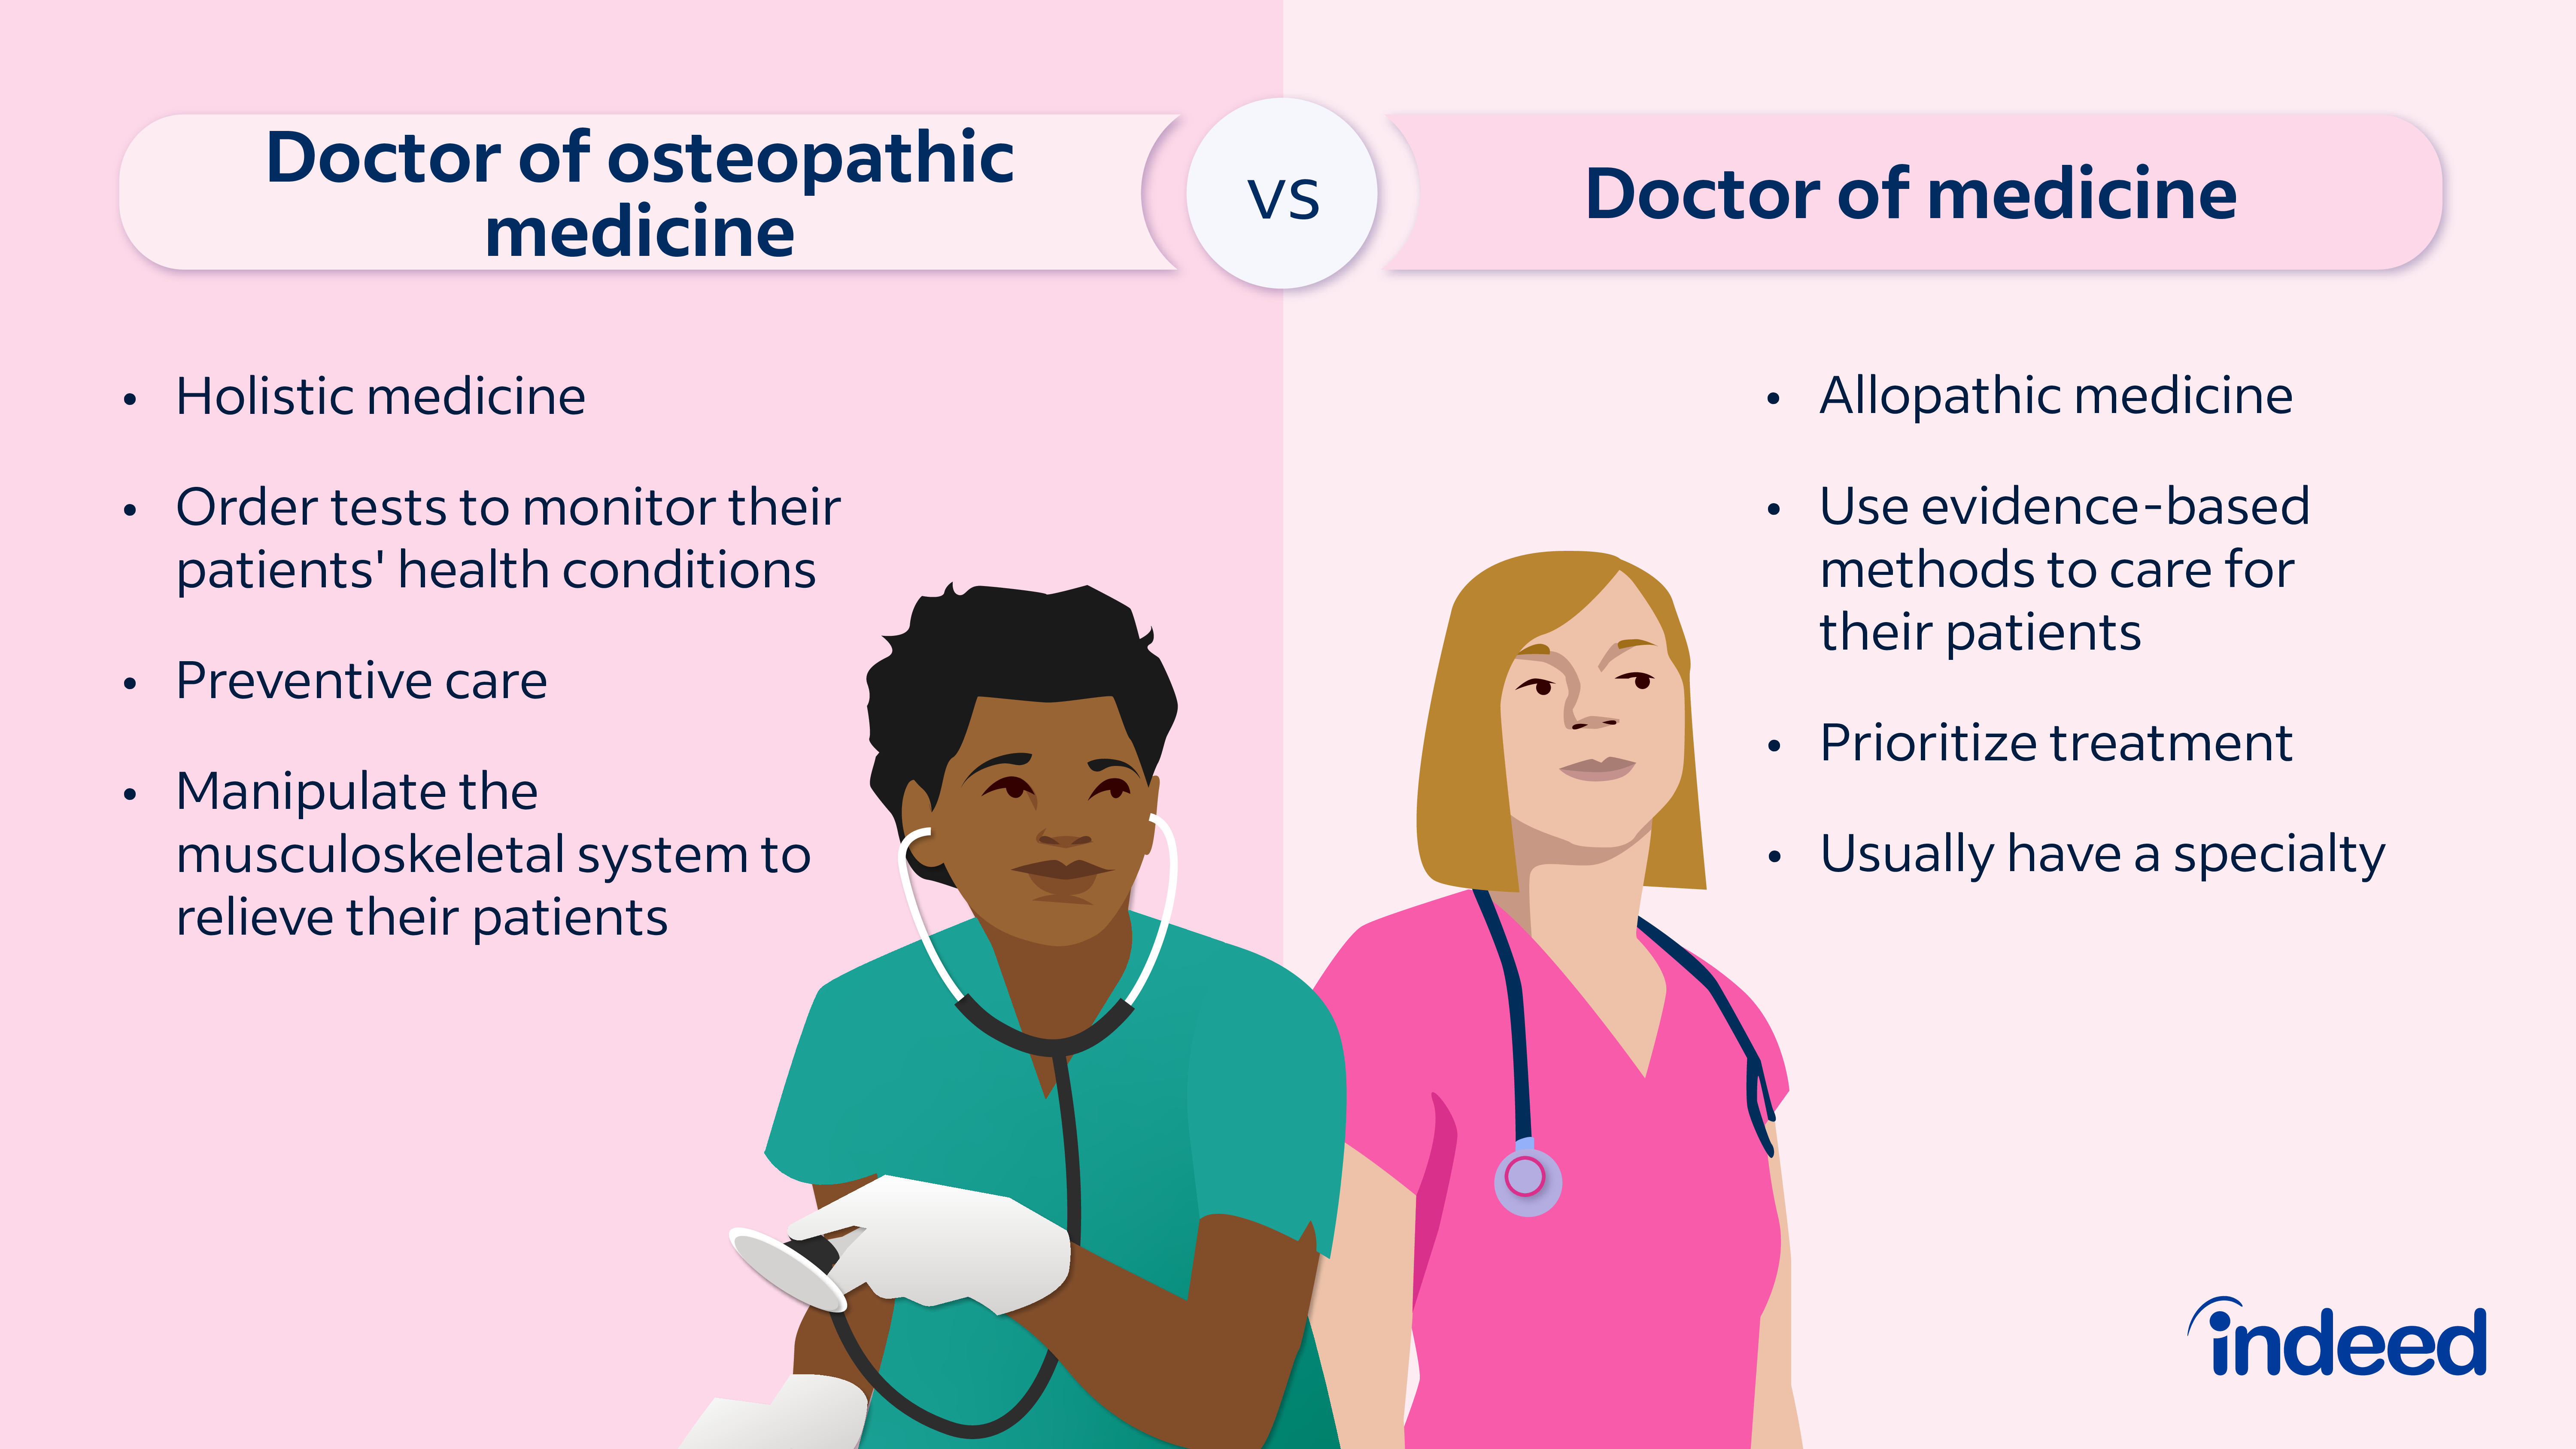
This is arguably the most substantial financial outlay. Medical school is typically a four-year postgraduate program. According to the Association of American Medical Colleges (AAMC), the median cost of tuition, fees, and health insurance for the 2023-2024 academic year was approximately $69,000 for in-state public school residents and over $95,000 for out-of-state public school and private school students. Over four years, this translates to an average debt burden for medical school graduates exceeding $200,000, with many carrying significantly more. This figure doesn’t even include living expenses, which can easily add another $20,000-$40,000 per year, pushing the total debt for many graduates close to or even over $300,000 by the time they receive their M.D. or D.O.
Residency and Fellowship Stipends vs. Opportunity Cost
Following medical school, aspiring physicians enter residency, a period of supervised training in a hospital or clinic setting, which can last anywhere from three to seven years, or even longer for sub-specialties. During residency and subsequent fellowships, doctors are compensated with a stipend, which, while providing a living wage, is significantly lower than what fully licensed physicians earn. For instance, first-year residents might earn in the range of $60,000-$70,000 annually.
While this income helps cover living expenses, it represents a substantial opportunity cost. For nearly a decade after high school, these highly educated individuals are earning modest salaries compared to their peers who entered other professions directly after undergraduate studies or even a shorter professional degree. The foregone income during these formative years, coupled with the escalating interest on student loans, further amplifies the total financial investment in a medical career. This period requires immense financial discipline and often necessitates continued reliance on student loan deferment or income-driven repayment plans.
Understanding Physician Compensation: Beyond the Salary
After the extensive training period, medical doctors finally begin to see the financial returns on their substantial investment. However, compensation is not monolithic and varies widely based on numerous factors.
Salary Ranges Across Specialties and Geographies
Physician salaries are among the highest across all professions, reflecting the years of training, critical responsibility, and specialized expertise. Data from sources like Medscape, MGMA, and Doximity consistently show average physician salaries ranging from $200,000 to over $500,000 annually, depending heavily on specialty. Primary care physicians (e.g., family medicine, internal medicine, pediatrics) typically earn on the lower end of this spectrum, while highly specialized fields like neurosurgery, orthopedic surgery, cardiology, and radiology often command the highest incomes. Geographical location also plays a significant role, with areas facing physician shortages or higher costs of living often offering more competitive compensation packages. For instance, a rural area might offer a higher base salary to attract talent compared to a highly competitive urban center.
The Role of Incentives, Bonuses, and Practice Ownership
Beyond base salary, many physicians, particularly those employed by hospital systems or large groups, receive performance-based bonuses, signing bonuses, and productivity incentives. These can be tied to patient satisfaction scores, quality metrics, panel size, or relative value units (RVUs) generated. For physicians in private practice, compensation is directly linked to the revenue generated by their practice, after accounting for overhead. This can offer significantly higher earning potential but also comes with greater financial risk and management responsibilities. Equity ownership in a practice, surgery center, or other medical ventures can also become a substantial source of wealth accumulation over time.
Navigating Student Loan Repayment Strategies
With an average medical school debt exceeding $200,000, and often much more, strategic student loan management is paramount for new physicians. Repayment options range from standard 10-year plans to income-driven repayment (IDR) plans (e.g., PAYE, REPAYE, IBR), which adjust monthly payments based on income and family size. Public Service Loan Forgiveness (PSLF) is another critical option for those who work for qualifying non-profit organizations or government entities for ten years while making 120 qualifying payments. The choice of repayment strategy has significant financial implications, impacting cash flow, interest accrual, and the total amount repaid over time. Many physicians work with financial advisors specializing in student loan management to optimize their repayment plans and minimize interest costs.
Financial Management for Medical Professionals
The high income potential of physicians is often counterbalanced by their substantial debt burden and the late start to wealth accumulation. Effective financial management is therefore crucial.
Budgeting and Debt Management in Early Career
For newly minted attendings, the transition from resident stipends to a full physician salary can be exhilarating but also dangerous without proper financial planning. The temptation to “lifestyle creep” – increasing spending in line with increased income – is strong. However, prioritizing aggressive student loan repayment, establishing an emergency fund, and beginning to save for retirement should be the immediate financial goals. A robust budget helps allocate funds strategically, ensuring that the high income is leveraged to pay down debt rapidly and build a strong financial foundation, rather than simply being spent.
Retirement Planning and Wealth Building Strategies
Due to the late start in their careers, physicians often have fewer years than other professionals to save for retirement. This necessitates maximizing contributions to tax-advantaged retirement accounts such as 401(k)s, 403(b)s, and IRAs (Roth or Traditional). Many physicians also utilize Backdoor Roth IRAs and Health Savings Accounts (HSAs) for additional tax-efficient savings. For those in private practice, setting up a SEP IRA or Solo 401(k) allows for even higher contribution limits. Beyond these, diversifying investments into taxable brokerage accounts, real estate, and other assets is common to build substantial wealth. Estate planning also becomes critical for physicians to protect their assets and ensure their legacy.
Malpractice Insurance and Other Practice-Related Expenses
A unique financial aspect of being a medical doctor is the necessity of malpractice insurance. This covers liability arising from alleged negligence or misconduct. The cost of malpractice insurance varies significantly by specialty and location, with high-risk specialties like obstetrics, neurosurgery, and emergency medicine facing premiums that can range from tens of thousands to over $100,000 annually. This is a non-negotiable expense that directly impacts a physician’s take-home pay, whether they are employed (where the employer often covers it) or in private practice. Other ongoing professional expenses include continuing medical education (CME), professional society dues, licensing fees, and potentially maintaining multiple state licenses.
The Business of Medicine: Private Practice vs. Employed Physician
The financial landscape for a medical doctor also differs significantly based on their employment model – whether they operate their own private practice or are employed by a hospital system or large group.
Startup Costs and Overhead in Private Practice
Opening a private medical practice is akin to launching any small business, with substantial startup costs. These include leasing or purchasing office space, medical equipment (from examination tables to diagnostic machinery), electronic health record (EHR) systems, furniture, and initial inventory of supplies. Beyond the initial investment, ongoing overhead costs are considerable. These encompass staff salaries and benefits (nurses, medical assistants, administrative staff), utilities, rent, malpractice insurance, billing and coding services, and marketing. Managing these expenses efficiently is crucial for the financial viability and profitability of a private practice. Physicians in private practice take on entrepreneurial risk but also gain autonomy and the potential for higher long-term earnings.
Revenue Generation and Billing Cycles
The financial health of a private practice hinges on efficient revenue generation and managing complex billing cycles. This involves accurate coding of services, submitting claims to insurance companies (both public and private payers), and managing patient collections for co-pays, deductibles, and self-pay services. Delays or errors in this process can significantly impact cash flow. Understanding reimbursement rates, negotiating with insurance providers, and navigating the ever-evolving healthcare regulations (e.g., HIPAA, MACRA) are critical skills for a physician leading a practice. The move towards value-based care models, away from fee-for-service, also introduces new financial complexities and opportunities.
The Financial Security of an Employed Physician
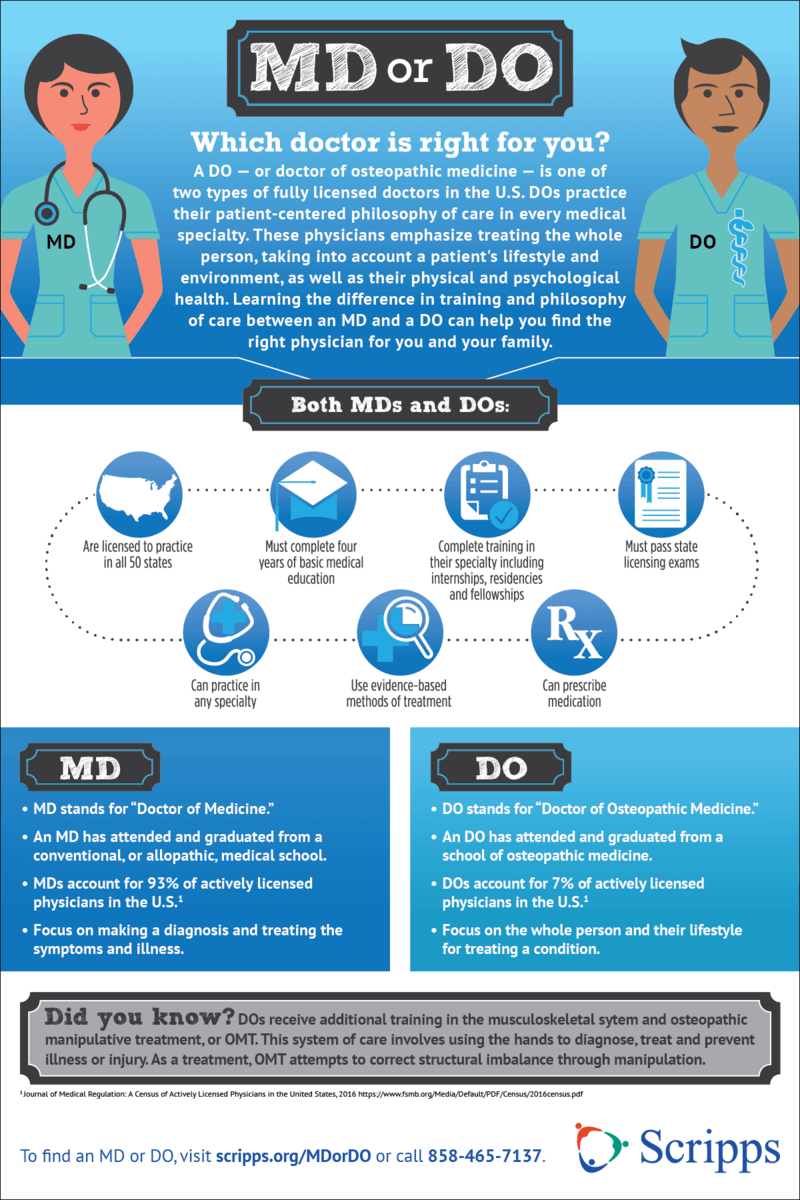
Many physicians today opt for employment by hospital systems, large group practices, or academic institutions. Financially, this often provides a more predictable income stream with less administrative burden. Employed physicians typically receive a steady salary, often with performance bonuses, and benefit packages that include health insurance, retirement contributions (e.g., 403(b) or 401(k)), and malpractice coverage. This model reduces entrepreneurial risk and allows physicians to focus primarily on patient care, delegating the business aspects to their employer. While the ceiling for income growth might be lower than for a highly successful private practice owner, the stability and reduced overhead responsibility are significant financial advantages, particularly for early career physicians still managing substantial student loan debt.
In conclusion, “what is a medical doctor” is a question with profound financial implications. The journey is marked by a massive educational investment, years of delayed gratification, and a subsequent career offering substantial earning potential alongside unique financial complexities. From managing a six-figure student debt to planning for retirement and navigating the business intricacies of healthcare, a medical doctor’s financial life requires diligent planning, strategic decision-making, and often the guidance of specialized financial professionals. Understanding these monetary facets is key to appreciating the full scope of what it means to be a physician in the modern era.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.