
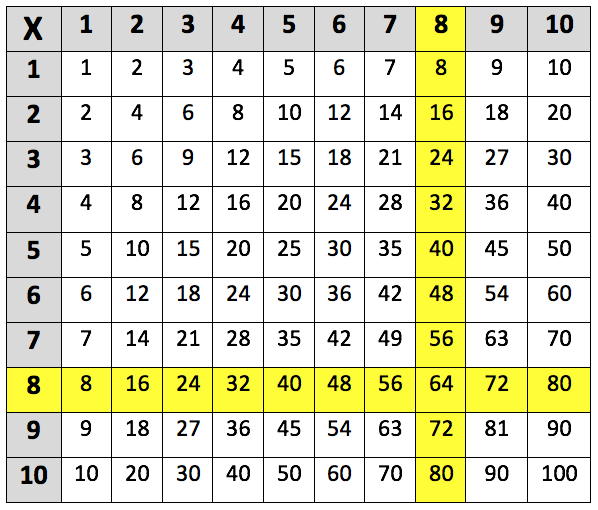
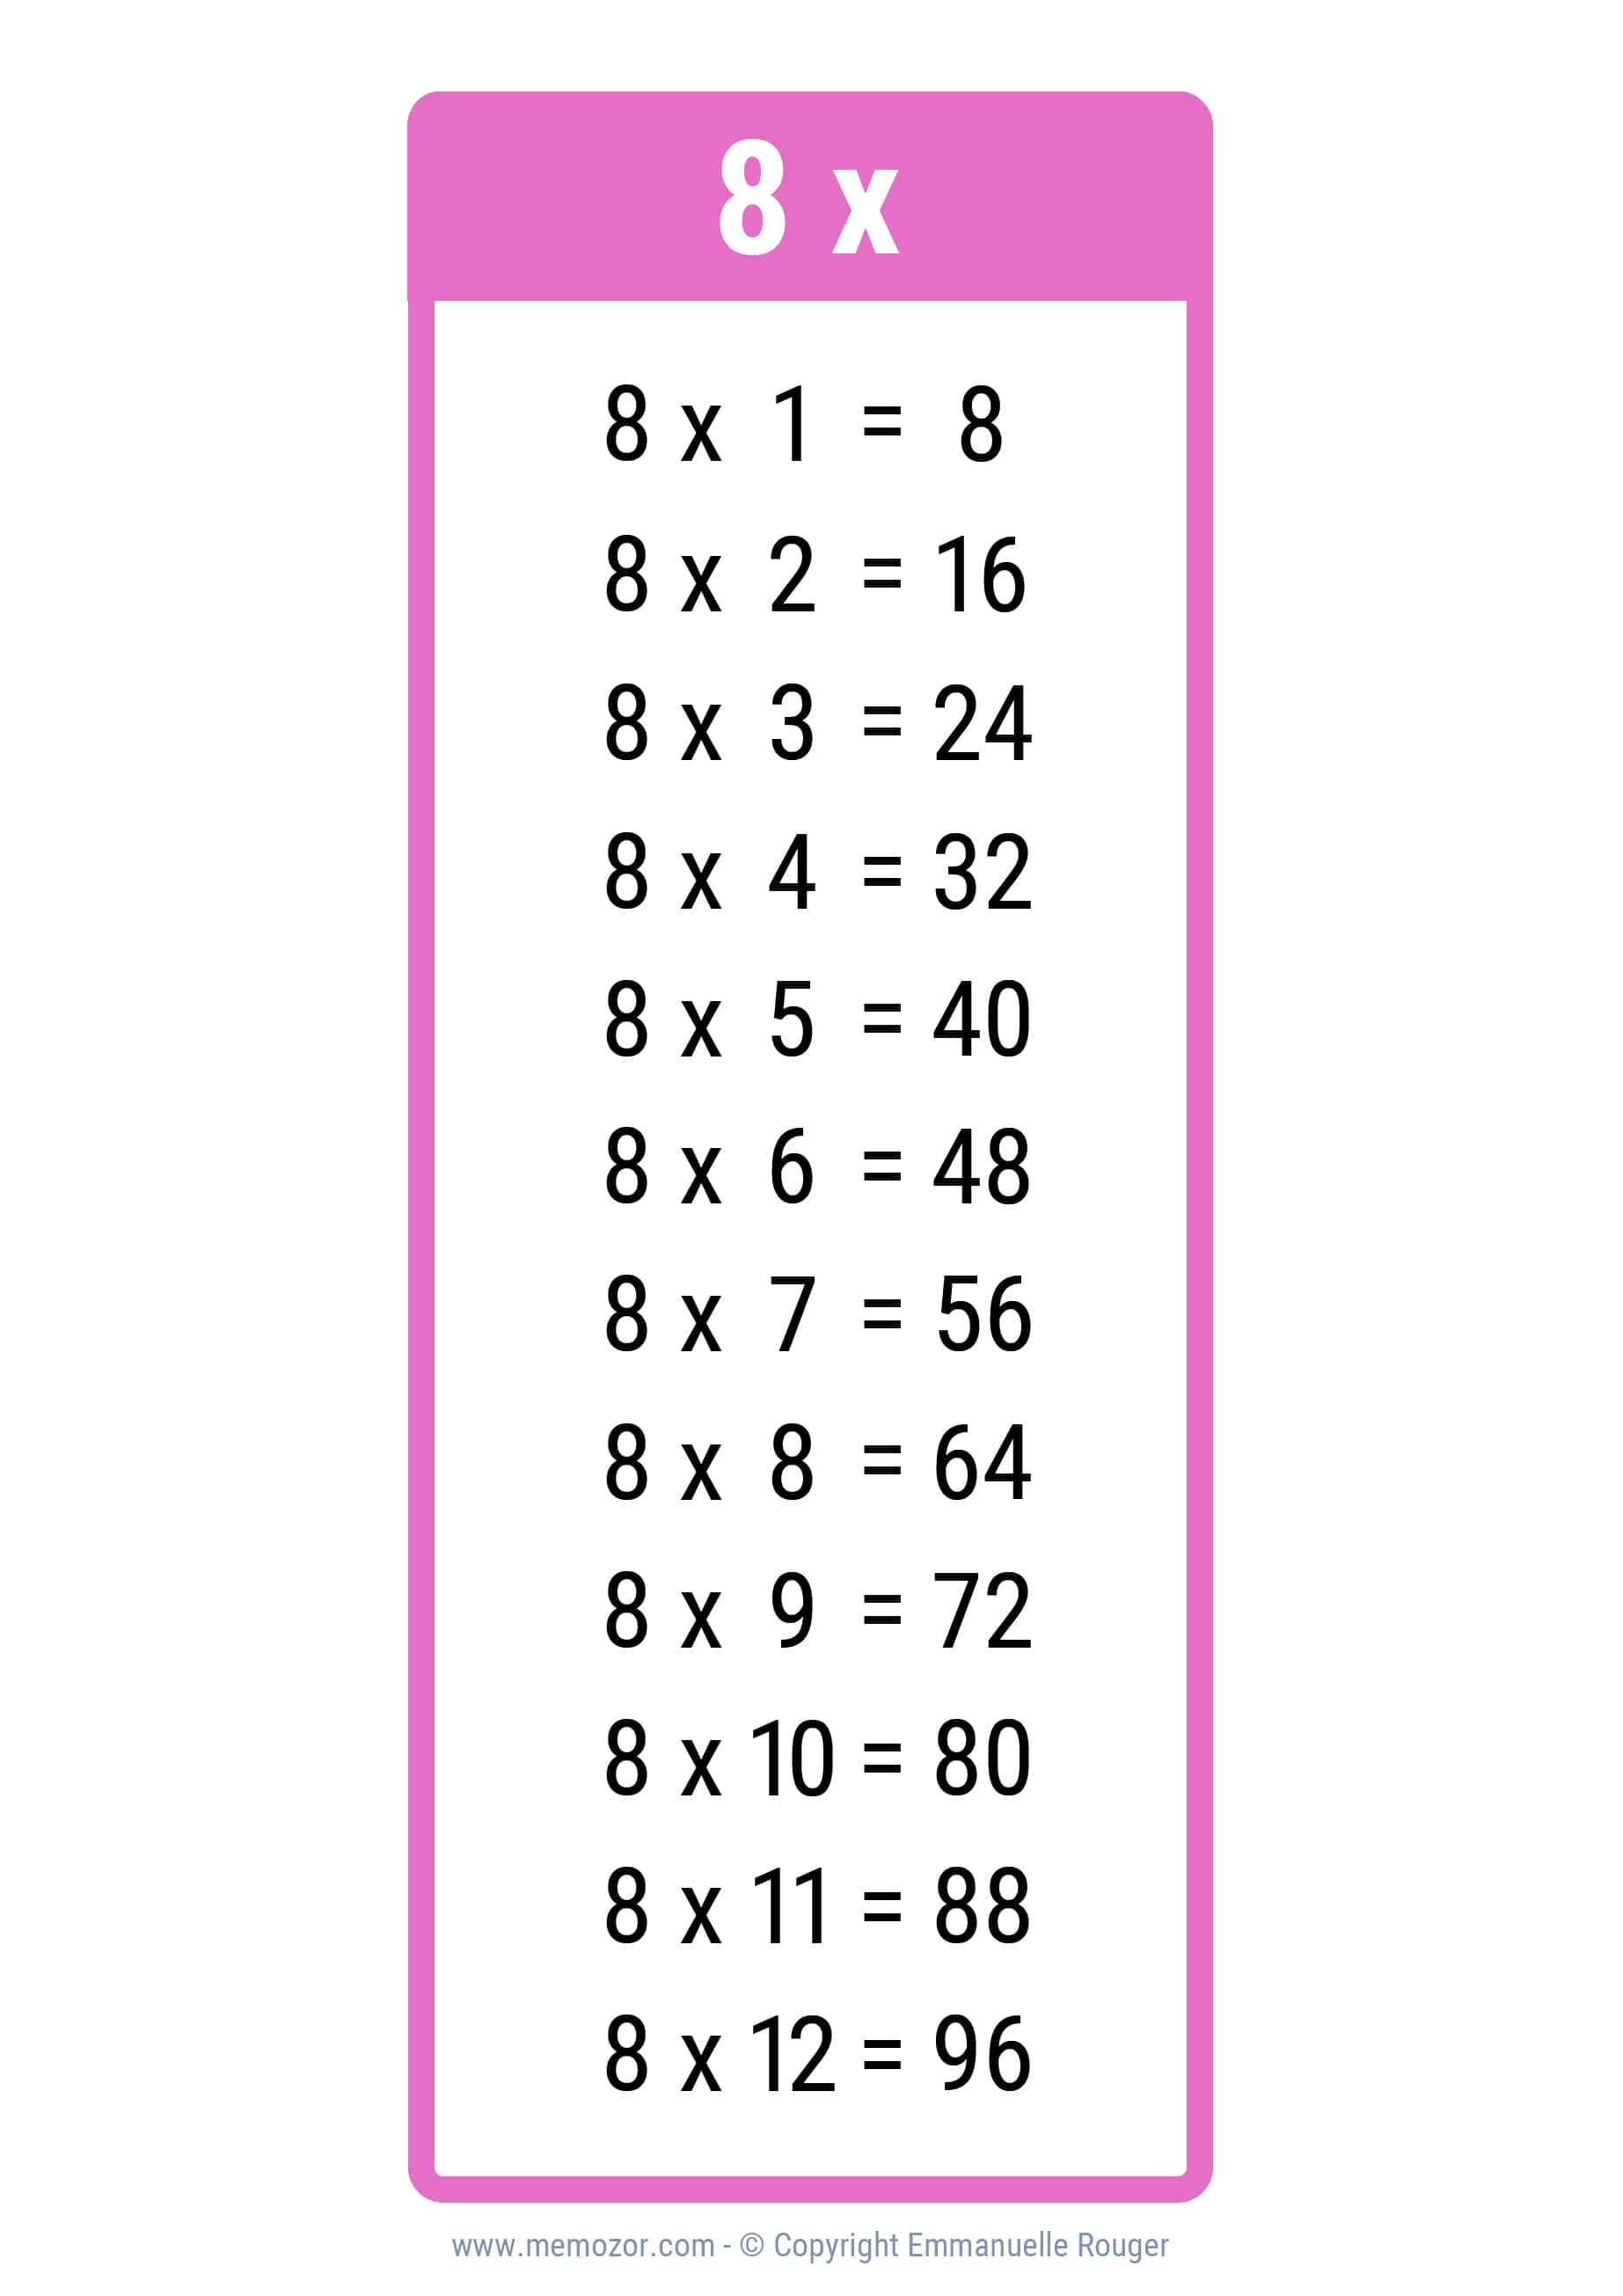
In a world increasingly dominated by sophisticated algorithms, artificial intelligence, and instantaneous data, the question “what is 8 times 3?” might seem almost comically basic. It’s a multiplication problem typically solved by a child in elementary school, a task so fundamental that our brains can often compute it faster than we can type it into a calculator. Yet, beneath its deceptive simplicity lies a profound truth, especially when we apply its essence to the realm of money. This seemingly trivial arithmetic problem is a powerful metaphor for the bedrock principles of financial literacy, a reminder that even the most complex financial landscapes are built upon foundational calculations, and that a solid grasp of these basics is not just helpful, but absolutely essential for navigating the complexities of personal finance, investing, and business.

Ignoring the simple arithmetic, whether it’s 8 times 3, 10 divided by 2, or 5 plus 7, is akin to building a skyscraper without understanding the structural integrity of its basic beams and columns. While financial tools and advisors can undoubtedly assist, a fundamental understanding of how numbers interact is the ultimate compass. This article will delve into why this basic mathematical query, when viewed through a financial lens, unlocks critical insights into wealth creation, debt management, and strategic financial decision-making, ultimately empowering individuals and businesses to master their money.
Beyond the Calculator: The Foundational Math of Financial Literacy
In an era where technology promises to automate and simplify much of our lives, the temptation to delegate even the most basic calculations to our devices is strong. However, true financial literacy demands more than just knowing how to operate an app or a spreadsheet; it requires an intrinsic understanding of the numbers themselves. “What is 8 times 3?” serves as a powerful reminder of the fundamental arithmetic that underpins every financial transaction, every investment decision, and every budget allocation.
The Primacy of Basic Arithmetic in Personal Finance
At its core, personal finance is a game of addition, subtraction, multiplication, and division. Your monthly budget is an exercise in ensuring that your income (additions) exceeds your expenses (subtractions). Understanding how much you’re saving over time often involves multiplication (e.g., saving $100 per month for 12 months is $100 x 12). Calculating interest on a loan or a savings account is a direct application of multiplication (principal x rate x time). Even complex financial instruments like derivatives or advanced investment strategies boil down to these elementary operations at some point, albeit with many layers of complexity built on top.
Consider the simple act of grocery shopping. You might buy 8 items, each costing roughly $3. Your mental calculation of $24 helps you track your spending even before you reach the checkout. This isn’t just about getting the right answer; it’s about developing an intuitive feel for how money moves and accumulates. This instinct, honed by consistent engagement with basic arithmetic, allows for on-the-fly decision-making that aligns with your broader financial goals. Without this bedrock, every financial interaction becomes a black box, leaving you vulnerable to miscalculations and poor choices.
Why Simple Calculations Still Matter in a Digital Age
It’s easy to argue that with smartphones and financial software, the need for mental arithmetic is obsolete. After all, why calculate 8 times 3 when a calculator can do it instantly? However, relying solely on tools without understanding the underlying mechanics is like driving a car without knowing how to steer manually. When the GPS fails, you’re lost. Similarly, when a financial statement presents a summary, or an advisor explains a projection, your ability to quickly verify or comprehend the numbers relies on your grasp of basic math.
Moreover, calculators and software are only as good as the data entered and the formulas applied. A fundamental understanding of arithmetic allows you to spot errors, question anomalies, and critically evaluate the information presented to you. If a loan repayment schedule shows an unexpectedly high total interest, knowing how to do a quick approximation of principal * interest rate * term allows you to identify potential discrepancies or hidden fees. This critical thinking, fueled by basic mathematical confidence, is an invaluable asset in protecting your financial interests and avoiding costly mistakes that automated systems might overlook or even propagate if fed incorrect initial data.
Building Blocks for Complex Financial Understanding
Just as understanding the product of 8 and 3 is a prerequisite for more advanced algebra or calculus, mastering basic financial arithmetic is the gateway to understanding more complex financial concepts. Concepts like compound interest, present value, future value, inflation, and risk assessment are all fundamentally built upon repeated applications of multiplication, division, addition, and subtraction over time.
For instance, understanding the power of compound interest – often dubbed the “eighth wonder of the world” – is essentially grasping exponential multiplication. Knowing that a small, consistent investment made early can grow into a substantial sum over decades isn’t just about plugging numbers into a future value calculator; it’s about internalizing the cumulative effect of repeated “multiplications” (returns) on your principal. Without this foundational comprehension, these powerful financial concepts remain abstract, making it harder to truly harness them for your benefit.
Decoding Financial Decisions: From Simple Multiplications to Strategic Growth
The power of “8 times 3” extends far beyond simple tallying. It embodies the very essence of strategic financial planning: breaking down large, complex financial goals into manageable, calculable steps. Every successful financial journey, whether it’s saving for retirement, investing in a business, or paying off debt, relies on the ability to quantify, project, and optimize outcomes through a series of interconnected calculations.
Compound Interest: The Power of Repeated Multiplication
Perhaps the most potent demonstration of “8 times 3” applied to money is the concept of compound interest. If you invest $100 and earn 8% annually, in the first year you gain $8 (100 * 0.08). The next year, your 8% return is applied not just to your initial $100, but to your new total of $108. This seemingly small adjustment is what creates exponential growth over time. It’s multiplication applied not once, but repeatedly, year after year, on an ever-growing principal.
Understanding this mechanism, not just the result, is crucial for long-term wealth building. It drives the urgency of starting to invest early, even with small amounts. It also highlights the importance of consistent contributions, as each new dollar added to the principal has the potential to multiply itself over time. For instance, a small business owner reinvesting a portion of their profits back into the company isn’t just adding capital; they are setting the stage for future “multiplications” of that capital through increased revenue or efficiency.
Budgeting and Expense Tracking: Quantifying Your Financial Flow
At the heart of sound personal finance is a well-structured budget. And what is a budget but an intricate series of “8 times 3” calculations? You multiply your monthly rent by 12 to get your annual housing cost. You multiply your daily coffee expense by 30 to understand its monthly impact. You divide your annual income by 12 to determine your monthly earning potential.
Expense tracking, similarly, involves constantly calculating what comes in and what goes out. If you earn $3,000 per month and your fixed expenses total $2,000, you have $1,000 left for discretionary spending or savings. How you multiply, divide, add, and subtract from that $1,000 determines your financial trajectory. This simple yet disciplined approach prevents overspending, identifies areas for savings, and ultimately allocates your resources towards your financial goals. For businesses, this translates to meticulous cash flow management, where every expense and revenue stream is quantified to ensure solvency and profitability.
Investment Returns: Calculating Your Potential Gains
When evaluating investment opportunities, whether it’s stocks, real estate, or a new business venture, investors are constantly performing calculations akin to “8 times 3.” They might estimate an expected annual return of 8% on an investment of $30,000, quickly calculating a potential $2,400 annual gain. While actual returns can fluctuate, this basic projection provides a baseline for decision-making.
Furthermore, understanding risk-reward ratios often involves comparing potential gains (multiplications) against potential losses (subtractions or divisions). Diversification, for example, is about spreading your “multiplication” potential across different assets, reducing the impact if one asset performs poorly. For business finance, projecting ROI (Return on Investment) for a new project or product line is a critical exercise in estimating future revenue (multiplication) against initial capital outlay (subtraction), guiding strategic resource allocation. A clear understanding of these basic numerical relationships allows for informed choices rather than speculative gambles.
The Cost of Ignorance: When Basic Math Errors Prove Expensive
While knowing “what is 8 times 3” seems straightforward, the financial consequences of not internalizing such fundamental arithmetic can be devastating. Small numerical misunderstandings or simple calculation errors, when applied to financial instruments or repeated over time, can snowball into significant debt, missed opportunities, and substantial financial loss.
Miscalculating Debt: The Trap of Unseen Interest
One of the most insidious ways a lack of basic financial math can harm individuals is through debt, particularly credit card debt or high-interest loans. Many people understand they owe a principal amount, but they often underestimate the true cost when interest is applied. If you have $1,000 in credit card debt with an 18% annual interest rate, that’s $180 in interest annually if you don’t pay it down. But if you only make minimum payments, that 18% is applied to an ever-present balance, often compounding monthly.
The “8 times 3” scenario here illustrates how quickly a small interest rate (e.g., 3% monthly, equivalent to 36% annually if you don’t understand the compounding) can multiply the original debt. A person who struggles to grasp the cumulative effect of interest might only focus on the principal, failing to see how much extra they’re truly paying. This oversight can lead to an endless cycle of debt, where the interest payments consume a large portion of their disposable income, preventing them from saving or investing. Similarly, a business failing to correctly calculate the cost of capital can find itself with unmanageable leverage.
Underestimating Expenses: Budgeting Blunders
Another common pitfall is the failure to accurately estimate and track expenses. Individuals might remember their big monthly bills but overlook smaller, recurring expenses. For example, three $8 impulse purchases a week might seem insignificant, but over a month, that’s $96 (8 x 3 x 4 weeks), which could fund a significant portion of a savings goal. These “small multiplications” accumulate quickly.
Businesses, too, suffer from underestimating expenses. A small, overlooked operational cost, when multiplied across thousands of units or hundreds of employees, can erode profit margins significantly. Failing to correctly calculate the cost of goods sold, administrative overheads, or marketing spend can lead to incorrect pricing strategies, reduced profitability, and ultimately, business failure. The precision of “what is 8 times 3” highlights the importance of accounting for every single unit of cost.
Missing Opportunities: Failing to Project Growth
Just as poor math can lead to financial losses, it can also lead to missed opportunities. An individual who doesn’t grasp the power of compound interest might delay investing, losing years of potential growth. If they understood that even a modest 8% annual return on a $3,000 initial investment could become a substantial sum over decades, they might act sooner.
For entrepreneurs and businesses, a lack of mathematical acumen can be even more detrimental. Failing to accurately project potential revenue (e.g., 8 sales per day multiplied by an average price of $300), return on investment for a new product, or the scalability of a business model can mean passing up viable ventures or investing in unprofitable ones. The ability to model financial scenarios, even with basic “what if” calculations, is paramount for strategic planning and capitalizing on growth prospects. Not knowing how to project or interpret these basic calculations means opportunities pass by, or worse, are pursued blindly.
Empowering Your Financial Future: Developing a Mathematical Mindset
The question “what is 8 times 3?” is more than an elementary arithmetic problem; it’s a call to action for cultivating a robust mathematical mindset when it comes to money. It emphasizes that financial empowerment doesn’t solely come from earning more or having sophisticated tools, but from understanding the fundamental numerical relationships that govern our financial lives. Developing this mindset involves practical steps, a balanced approach to technology, and a commitment to informed decision-making.
Practical Steps to Enhance Financial Numeracy
Improving your financial numeracy doesn’t require a degree in mathematics; it requires intentional practice and a willingness to engage with numbers.
-
Budgeting Manually (Initially): While digital tools are convenient, try creating a budget on paper or a simple spreadsheet initially. This forces you to manually input, sum, and subtract, reinforcing the core arithmetic.
-
Estimate Before Calculating: Before using a calculator or app, try to estimate the answer to a financial calculation. For instance, if you’re buying something on a 20% discount, try to mentally calculate the approximate savings. This sharpens your numerical intuition.
-
Break Down Complex Problems: Just as “what is 8 times 3?” simplifies a calculation, learn to break down large financial goals into smaller, digestible numerical steps. Want to save $10,000 in a year? That’s roughly $833 per month ($10,000 divided by 12). This makes daunting tasks feel achievable.
-
Read and Understand Financial Statements: Don’t just glance at your bank statements, credit card bills, or investment reports. Take the time to understand where the numbers come from and what they mean. Question anything that doesn’t make sense.
-
Practice with Real-World Examples: Use your daily financial interactions as learning opportunities. How much interest did you pay on your last loan statement? What is the effective annual percentage yield on your savings account?
Leveraging Tools, Not Replacing Understanding
While a strong mathematical foundation is crucial, it doesn’t mean shunning financial technology. Quite the opposite: a deep understanding of basic arithmetic allows you to leverage these tools more effectively.
-
Validate Outputs: When a financial app or spreadsheet gives you a projection, your understanding of basic math allows you to critically evaluate if the output seems reasonable. If a simple interest calculation for 8% on $3,000 for one year shows an interest amount significantly different from $240, you know to investigate.
-
Set Up Formulas Correctly: If you’re using spreadsheets, knowing the underlying math helps you set up formulas accurately and troubleshoot them when they don’t produce the expected results.
-
Understand ‘Why’, Not Just ‘What’: Financial software can tell you ‘what’ your balance is, or ‘what’ your projected retirement fund will be. Your mathematical mindset helps you understand ‘why’ those numbers are what they are, allowing for better strategic adjustments. Tools should enhance your understanding, not replace it.
The Confidence of Calculated Decisions
Ultimately, mastering the simple mathematics behind “what is 8 times 3” and applying it to your financial life instills a profound sense of confidence. When you understand how interest accrues, how your budget works, or how investments grow, you’re no longer passively accepting financial outcomes. You’re an active participant, making calculated decisions based on solid numerical reasoning.
This confidence extends to various aspects of your financial journey: negotiating a salary, evaluating a mortgage offer, planning for retirement, or even launching a new business. You can ask informed questions, challenge assumptions, and make choices that are truly aligned with your financial well-being. The seemingly simple question, “what is 8 times 3?”, thus becomes a powerful mantra for anyone seeking to build a resilient, prosperous, and independent financial future. It’s a reminder that true financial mastery begins with the basics, enabling us to multiply our understanding and divide our financial worries.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.