
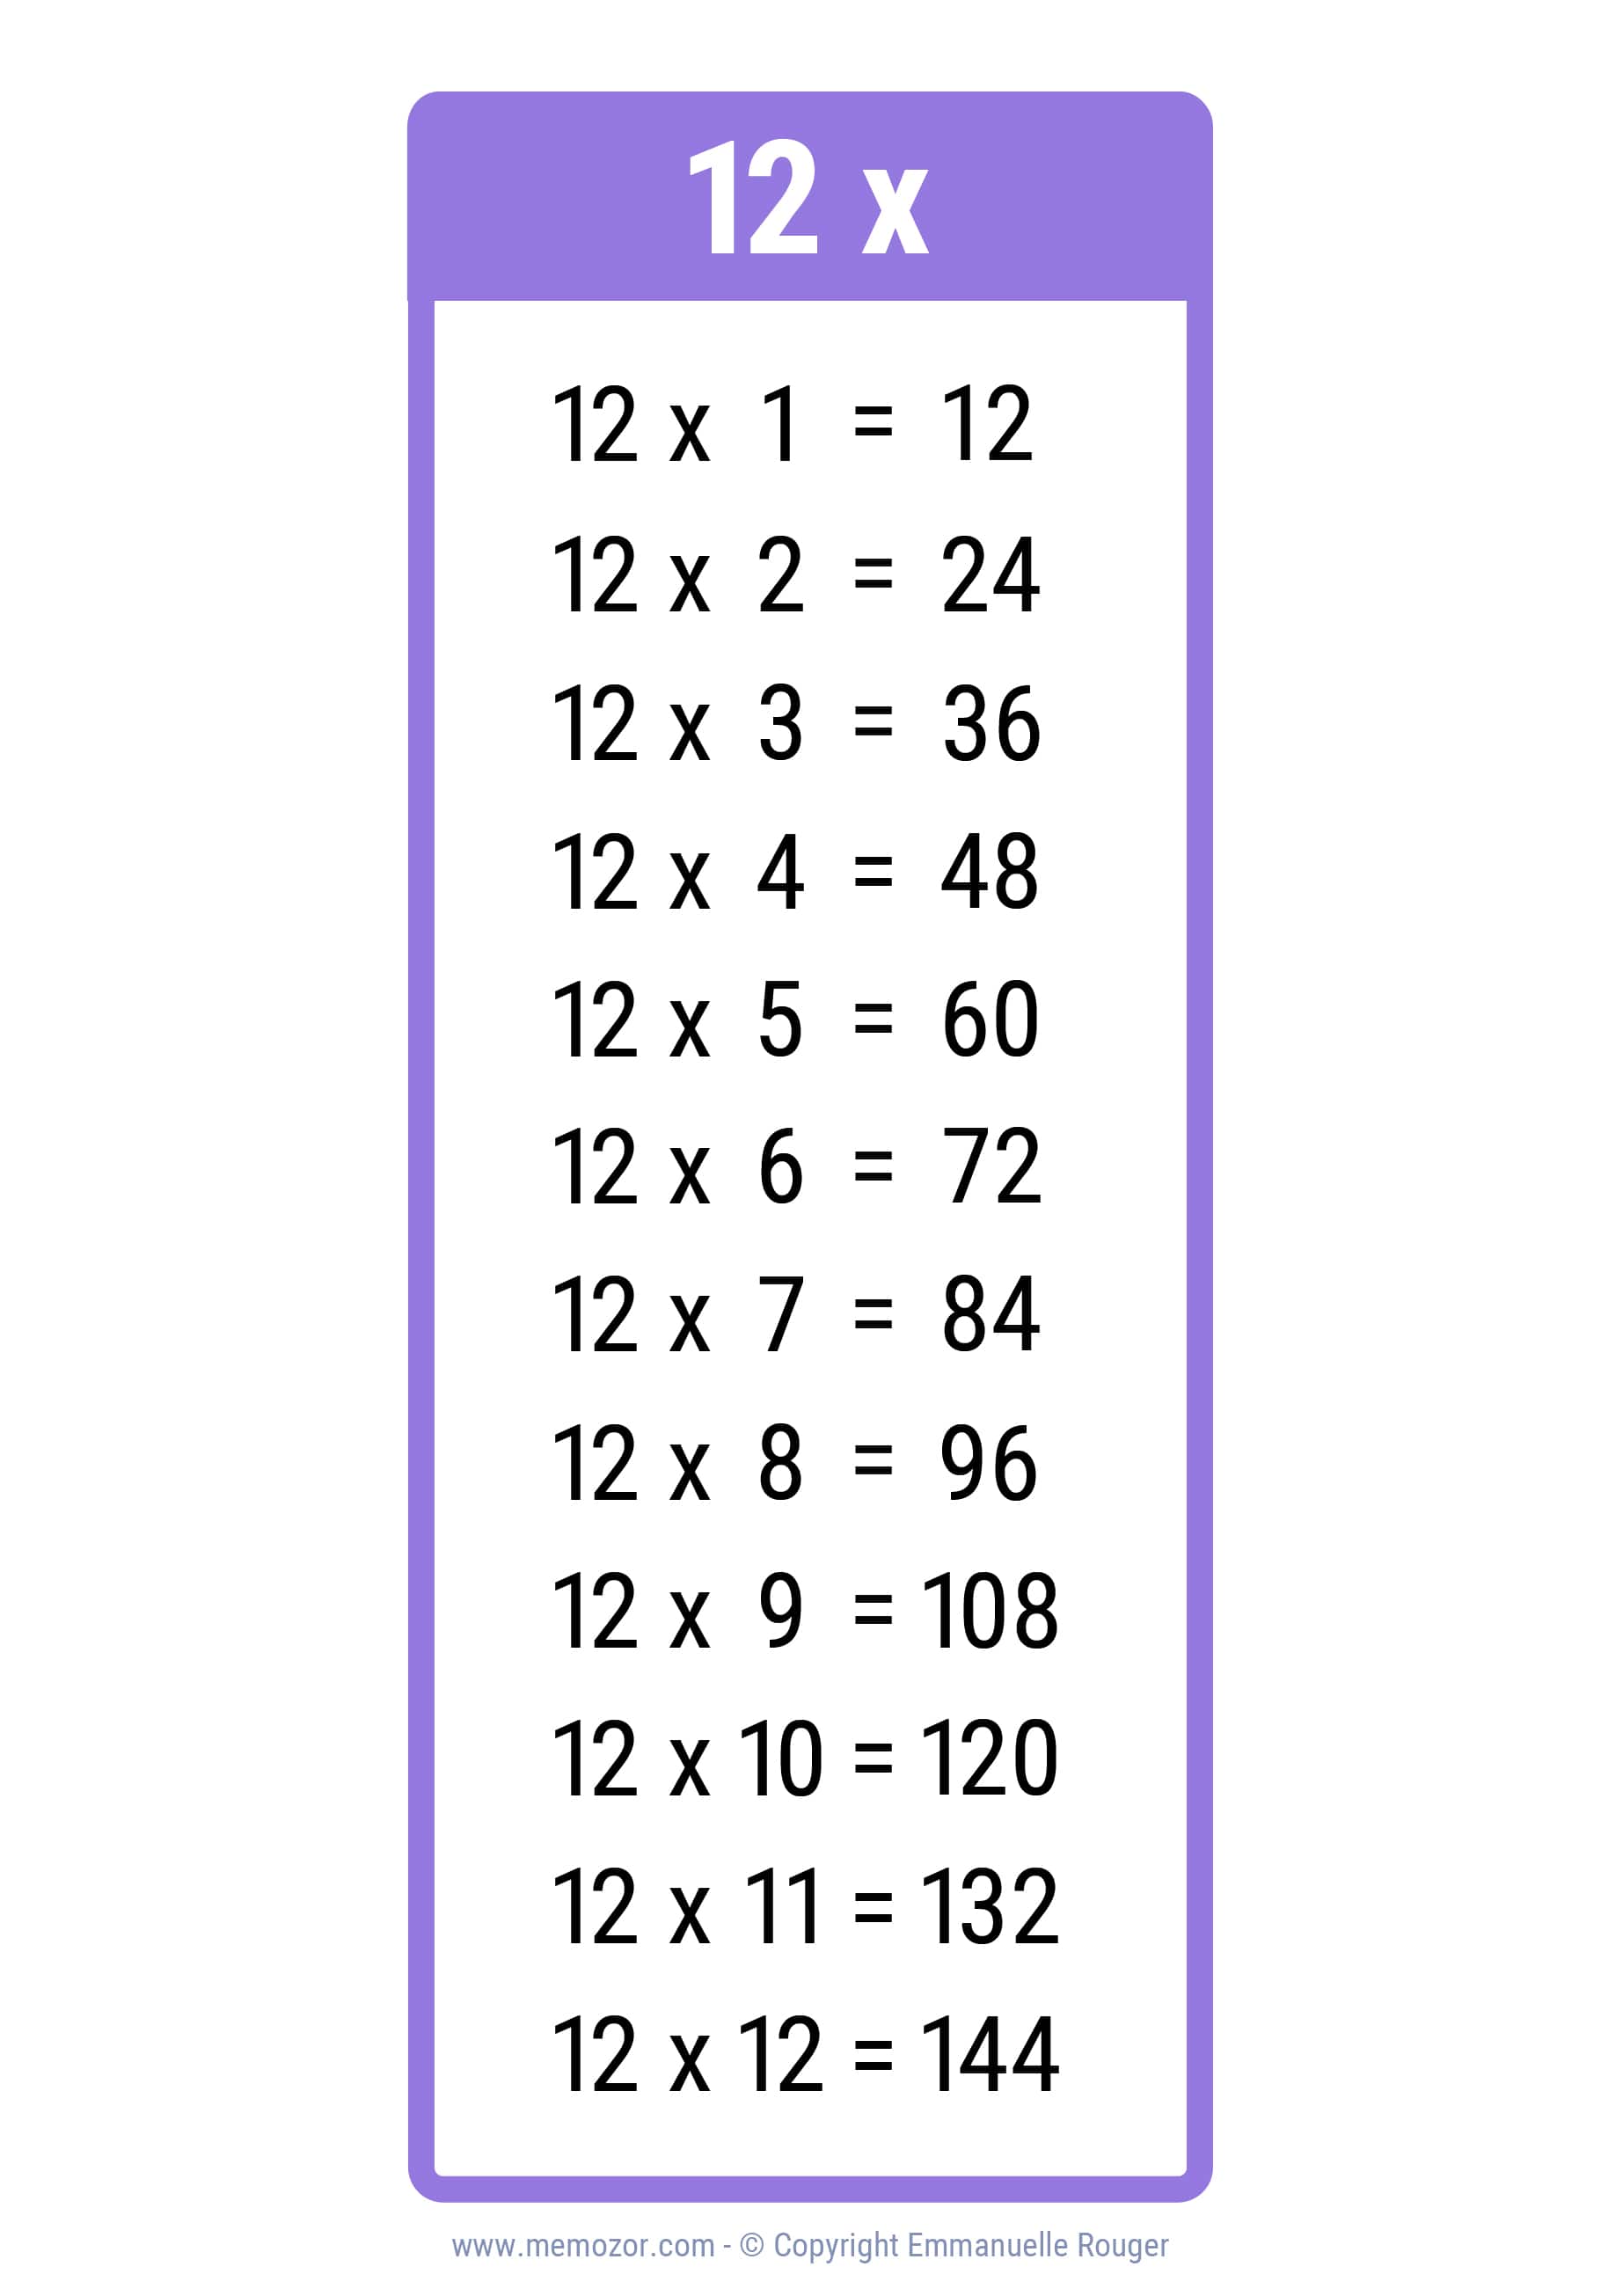
At first glance, the question “what is 12 times 5” appears to be a rudimentary arithmetic problem, the kind one might encounter in early schooling. The answer, of course, is 60. Yet, beneath this simple calculation lies a profound truth about financial literacy: every sophisticated financial concept, every savvy investment decision, and every robust personal budget is built upon a foundation of such basic arithmetic. Understanding simple multiplication isn’t just about passing a math test; it’s about equipping oneself with the fundamental tools to navigate the complex world of personal finance, investing, and business. In a financial context, “12 times 5” could represent anything from 12 months of $5 recurring expenses to 5 shares of a stock bought at $12 each, or even understanding that an annual event occurring for 5 years means 60 total occurrences. This seemingly trivial query serves as a gateway to comprehending the mechanics of money management, emphasizing that strong financial acumen begins with mastering the basics.

The Foundational Role of Basic Arithmetic in Personal Finance
Mastering elementary arithmetic is not merely an academic exercise; it is an indispensable life skill, particularly in the realm of personal finance. Without a solid grasp of basic operations like multiplication, division, addition, and subtraction, individuals are left at a disadvantage, unable to fully comprehend their financial landscape, make informed decisions, or protect themselves from potential pitfalls.
Budgeting and Expense Tracking
A personal budget is essentially a mathematical framework for managing income and expenses. The simplicity of “12 times 5” becomes evident when calculating recurring costs. Imagine a monthly subscription costing $5. Over a year (12 months), that’s 12 x $5 = $60. Extend that over 5 years, and it’s 60 x $5 = $300. Without this basic calculation, one might overlook the cumulative impact of small, consistent outflows. Similarly, if your rent is $1,200, understanding that this is $1,200 for one month, and calculating its proportion relative to your total income, requires both division and percentage understanding. Tracking daily expenditures also relies heavily on addition and subtraction; summing up your grocery bill, deducting it from your available funds, or calculating how many times you bought coffee at $5 over 12 days. These seemingly minor computations are the bedrock of effective budgeting, allowing individuals to identify spending patterns, allocate funds wisely, and ultimately save for future goals.
Understanding Interest and Returns
Interest, whether earned on savings or paid on loans, is fundamentally a mathematical concept. While complex interest calculations often employ formulas, the underlying principle is multiplication. Simple interest, for example, is calculated by multiplying the principal amount by the interest rate by the number of periods. If you have a savings account yielding a modest 5% annual interest on $1,200, after one year, your interest earned would be $1,200 * 0.05 = $60. Understanding this initial calculation is critical before delving into more complex concepts like compound interest. On the flip side, understanding how much you’re paying on a loan requires similar arithmetic. If you have a loan with 12 monthly payments of $50, knowing that you will pay $50 * 12 = $600 in that year allows for a clear picture of your financial obligations. Without this ability to quickly process these numbers, individuals are less equipped to compare loan offers, evaluate savings accounts, or truly grasp the cost of borrowing or the benefit of saving.
Managing Debt and Loans
Debt management is another area where basic arithmetic proves invaluable. When considering a loan, one must assess the total cost, not just the monthly payment. A loan with 60 payments (5 years x 12 months/year) of $120 each, for instance, totals $7,200. Comparing this total amount across different loan options, along with understanding the impact of varying interest rates and repayment schedules, is impossible without a comfortable command of multiplication and addition. Furthermore, calculating how quickly one can pay off debt by making extra payments requires mental agility with division and subtraction, illustrating the tangible benefits of applying simple math to complex financial challenges.
Leveraging Simple Math for Smarter Investing
Investing, often perceived as a domain requiring advanced financial degrees, is remarkably accessible to those who grasp basic mathematical principles. The principles of “12 times 5” — understanding quantity and accumulation — are central to making astute investment decisions.
Calculating Potential Gains and Losses
Before diving into sophisticated models, investors must be able to perform basic calculations of potential gains and losses. If you purchase 12 shares of a company stock at $50 per share, your initial outlay is $600. If the stock price rises to $60 per share, your investment is now worth 12 x $60 = $720, representing a $120 gain. Conversely, if the price drops to $45, your investment is worth $540, a $60 loss. These simple multiplications allow investors to quickly assess the immediate impact of market fluctuations on their portfolio. Beyond just share prices, understanding dividends (e.g., $1.20 dividend per share on 50 shares gives you $60) or even the implications of transaction fees also hinges on simple arithmetic.
The Power of Compounding Explained Simply
Compound interest, often hailed as the “eighth wonder of the world,” fundamentally relies on repeated multiplication. While precise calculations can be complex, understanding the concept of earning returns on your returns is a matter of basic accumulation. If you invest $1,000 and earn 5% in the first year, you have $1,050. In the second year, you earn 5% on $1,050, not just the original $1,000. This snowball effect, where your principal grows exponentially over time, is best understood through illustrative examples involving simple multiplications over several periods, reinforcing the idea that consistent, small gains (like 5% over 12 months) aggregate into significant wealth over time.
Diversification and Asset Allocation Ratios
A key tenet of intelligent investing is diversification, spreading investments across various asset classes to mitigate risk. This strategy is fundamentally mathematical. If your total investment capital is $12,000, and you decide to allocate 50% to stocks, 30% to bonds, and 20% to real estate, these percentages translate directly into simple multiplication:
-
Stocks: $12,000 x 0.50 = $6,000
-
Bonds: $12,000 x 0.30 = $3,600
-
Real Estate: $12,000 x 0.20 = $2,400

This basic arithmetic ensures that your portfolio aligns with your desired risk tolerance and financial goals, preventing overexposure to any single asset and illustrating how even abstract financial concepts boil down to foundational mathematical operations.
Building Financial Acumen: Beyond the Calculator
While calculators and financial software are invaluable tools, true financial acumen stems from an intuitive understanding of numbers. This inner calculator allows for quick assessments, informed decision-making, and a deeper connection to one’s financial reality.
Estimating On-the-Fly for Quick Decisions
Life often demands rapid financial judgments. Should you buy the 12-pack of an item for $50 or five individual items at $12 each? A quick mental calculation (12 x 5 is 60, so 5 x 12 is also 60) reveals that the individual items cost $60, making the 12-pack for $50 the better deal. Similarly, estimating a tip at a restaurant (e.g., 15% of a $60 bill is roughly $9) or quickly calculating the sales tax on a purchase prevents overspending or miscalculations. This ability to perform mental arithmetic empowers individuals to make financially sound decisions in real-time, reducing reliance on external tools and fostering self-sufficiency.
Identifying Financial Red Flags and Opportunities
A strong grasp of basic math enables individuals to scrutinize financial statements, identify discrepancies, and spot both red flags and opportunities. If a monthly subscription fee is listed as $12, and you’ve been charged for 5 months, but your bank statement shows a total of $70 ($12 x 5 = $60), you can immediately identify an overcharge. Conversely, understanding percentage discounts allows you to quickly discern a genuine bargain from a perceived one. For example, if an item usually costs $100, and a “limited-time offer” reduces it by $12, you know it’s an 12% discount. If another offer reduces it by $5, it’s 5%. Comparing these quickly helps assess value. This vigilance, born from mathematical literacy, protects against erroneous billing, hidden fees, and missed savings opportunities.
Empowering Financial Independence
Ultimately, the mastery of basic arithmetic fosters financial independence. When individuals can confidently understand their income, expenses, savings, and investments, they gain control over their financial destiny. They are less reliant on others to interpret their financial situation and more equipped to make choices that align with their long-term goals. The confidence that comes from knowing “12 times 5” is 60 translates into the confidence to build a budget, negotiate a loan, or plan for retirement, transforming abstract numbers into tangible progress towards financial freedom.
Practical Applications in Business and Side Hustles
For entrepreneurs, small business owners, or anyone engaging in a side hustle, the principles embedded in “12 times 5” are not just helpful but absolutely critical for survival and growth. Business success hinges on a deep understanding of numbers.
Pricing Strategies and Profit Margins
Setting the right price for a product or service is a delicate balance, heavily reliant on arithmetic. If a raw material for an item costs $5, and you use 12 units of it per finished product, the material cost alone is $60. Add labor, overhead, and marketing, and you begin to construct a total cost of goods sold. To achieve a desired profit margin, say 50%, you then need to multiply your total cost by 1.5. Understanding these basic calculations prevents underpricing that leads to losses or overpricing that deters customers. Similarly, calculating gross profit (revenue minus cost of goods sold) and net profit (revenue minus all expenses) requires constant application of addition, subtraction, and multiplication, ensuring the business remains viable.
Inventory Management and Cost Analysis
Efficient inventory management is vital for controlling costs and meeting customer demand. If a business orders 12 units of a component at $5 each, the total cost for that batch is $60. Tracking how many units are sold, how many remain, and when to reorder all involve basic subtraction and comparison. Furthermore, analyzing the cost-effectiveness of different suppliers or production methods often boils down to multiplying unit costs by quantities. A keen eye for these numbers can identify areas for cost reduction, improve cash flow, and prevent costly overstocking or stockouts.
Scaling Operations with Mathematical Precision
As a business or side hustle grows, scaling operations requires careful mathematical planning. If your current monthly output is 12 units, and you project a need to increase production by a factor of 5 next year, you immediately know you’ll need to produce 60 units per month. This simple multiplication then cascades into numerous other calculations: How many more raw materials will be needed? How many more hours of labor? What impact will this have on overhead costs? Projecting revenue growth, understanding break-even points for new products, or even calculating the return on investment for a new marketing campaign all depend on applying basic arithmetic to complex business scenarios. Without this numerical clarity, expansion efforts can quickly lead to unforeseen expenses and financial instability.
In conclusion, “what is 12 times 5” is far more than a simple math problem. It is a microcosm of the foundational numerical literacy essential for navigating the entire financial landscape. From personal budgeting and astute investing to managing debt and running a profitable business, the ability to confidently perform and understand basic arithmetic empowers individuals and entrepreneurs alike to make informed decisions, mitigate risks, and build lasting financial success. The journey to financial mastery begins with these fundamental building blocks, proving that even the simplest calculations hold immense power in the world of money.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.