
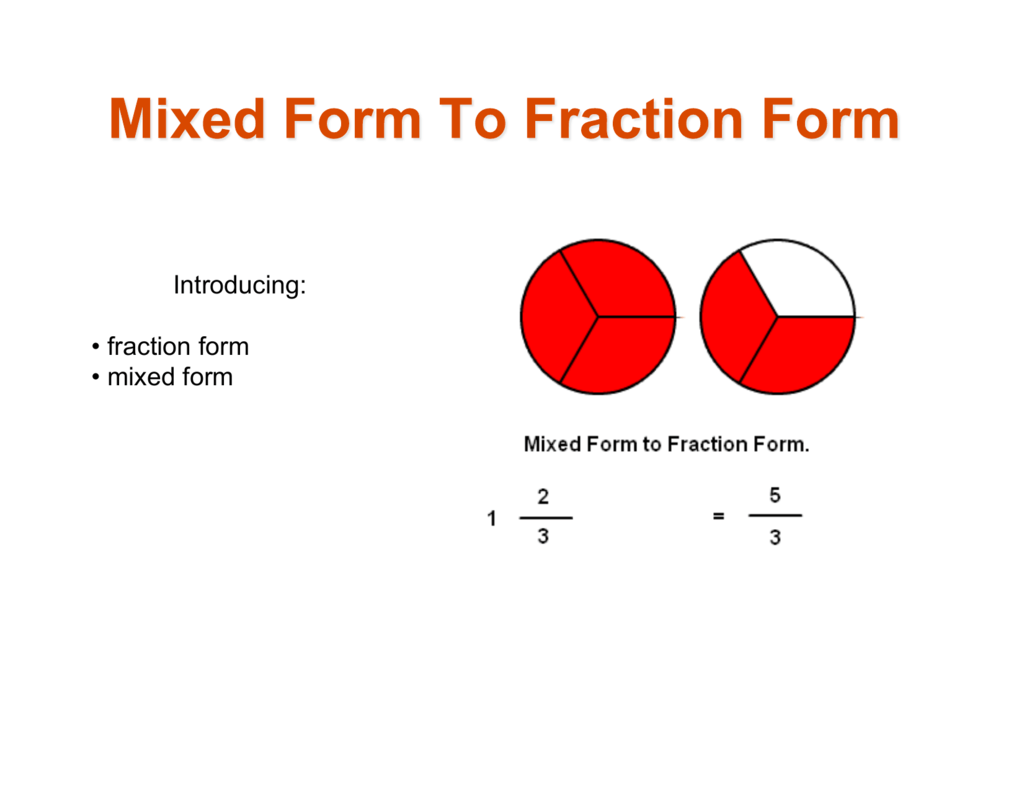
At first glance, the question “what is 1 2 1 3 in fraction form?” might seem like a simple mathematical puzzle. Is it asking for 12/13? Or perhaps 1/2 and 1/3 as separate entities? While the literal answer to this precise sequence could be debated, its deeper implication, particularly within the realm of personal finance and investing, reveals a far more critical lesson. This seemingly elementary query serves as a gateway to understanding the bedrock of financial literacy: the ability to interpret and apply fractions, ratios, and percentages in everyday financial decisions. Far from being a mere academic exercise, comprehending how parts relate to a whole is indispensable for effective budgeting, strategic investing, and sound financial planning. In the world of money, understanding “what is 1 2 1 3 in fraction form” isn’t about rote conversion; it’s about seeing the numerical relationships that govern our financial lives.
The Ubiquitous Nature of Fractions in Finance
Finance, at its core, is a discipline of measurement and comparison. Every budget, investment return, loan interest rate, or personal savings goal relies on understanding proportions—how one part relates to another, or to the total. Fractions, in their purest sense, are representations of these relationships. They are the language of division, sharing, and allocation, making them inherently woven into the fabric of financial health.
From Budgeting to Investments: Seeing the “Parts of a Whole”
Consider a personal budget. When you allocate 1/3 of your income to housing, 1/5 to savings, and the remainder to living expenses, you are operating entirely within the framework of fractions. Each category represents a fractional part of your total income. If your goal is to save “1 out of every 2” dollars for retirement, you’re looking at a 1/2 savings rate. These simple fractions provide clarity, allowing individuals to visualize how their money is distributed and identify areas for adjustment.
In the investment world, fractions manifest as asset allocation. A diversified portfolio might consist of 1/2 in stocks, 1/3 in bonds, and 1/6 in real estate. Each fraction denotes a strategic proportion designed to balance risk and return. Without a firm grasp of these fractional relationships, building a robust and resilient investment portfolio becomes a shot in the dark, rather than a calculated strategy. Understanding “1 2 1 3” in this context isn’t about specific numbers, but about the ability to break down an investment into meaningful fractional components.
Debt-to-Income and Savings Rates: Critical Ratios for Personal Finance
Beyond simple allocations, fractions are fundamental to key financial metrics that determine eligibility for loans, mortgages, and even the overall health of one’s financial standing. The debt-to-income (DTI) ratio, for instance, is a classic example of a fraction in action. It expresses your total monthly debt payments as a fraction of your gross monthly income. Lenders often look for a DTI below a certain threshold (e.g., 43% or roughly 1/2.3 of your income) to assess your ability to manage additional debt. A higher fraction indicates greater financial strain.
Similarly, personal savings rates are often expressed as fractions or percentages—what fraction of your income are you setting aside for future goals? Financial advisors frequently recommend saving 15-20% (or roughly 1/5 to 1/6) of your income for retirement. These benchmarks are powerful because they provide actionable targets rooted in simple fractional understanding. Ignoring these ratios is akin to driving without a speedometer; you might be moving, but you have no idea if you’re going too fast, too slow, or in the right direction relative to your goals.
Decoding “1 2 1 3”: Practical Applications of Numerical Relationships
Let’s use the numerical sequence “1 2 1 3” not as a single number to convert, but as distinct digits representing quantities or proportions, to illustrate practical financial applications. These seemingly arbitrary numbers can symbolize various financial relationships when viewed through the lens of fractions.
Understanding Investment Portfolios: Allocating Assets as Fractions
Imagine an investment scenario where “1” unit of capital is diversified into “2” different asset classes, with “1” portion going to one and “3” portions to another, perhaps reflecting risk tolerance. This isn’t about 1/2 or 1/3 directly, but about understanding that if you have $1000 and divide it into 1 part and 3 parts, you have 4 parts in total. So, 1/4 ($250) goes to one asset and 3/4 ($750) goes to another. This fractional distribution is crucial for managing risk and pursuing specific returns. A balanced portfolio might aim for a 1:2 ratio of bonds to stocks, meaning for every 1 part bond, there are 2 parts stock – effectively 1/3 bonds and 2/3 stocks. These aren’t just numbers; they are strategic decisions expressed fractionally.
Furthermore, consider individual stock ownership. When a company issues dividends, it’s often a fraction of its earnings per share. If a company earns $3 per share and pays out $1 in dividends, the payout ratio is 1/3. This fraction provides insight into the company’s financial health and its commitment to shareholders.
Interest Rates and Returns: The Fractional Power of Compounding

Interest rates, whether on loans, savings accounts, or investments, are inherently fractional. A 2% interest rate is simply 2/100 or 1/50. Understanding this fraction is key to grasping how quickly your money can grow or how much debt can accrue. The magic of compound interest, often hailed as the “eighth wonder of the world,” is a fractional phenomenon. Earning 1/10 (10%) interest annually means your principal grows by that fraction each year, and then the next year, you earn interest on your original principal plus the accumulated interest.
For example, if you invest $1000 at a 10% annual return (1/10), after year one, you have $1000 + (1/10 * $1000) = $1100. After year two, you have $1100 + (1/10 * $1100) = $1210. This compounding effect, driven by repeated application of a fractional rate, demonstrates the powerful long-term impact of even small percentage gains over time. Conversely, understanding the fractional burden of high-interest credit card debt reveals why it can be so detrimental to financial well-being.
Navigating Financial Products with Fractional Understanding
From the simplest bank account to complex derivatives, financial products are structured around fractional principles. Being able to dissect these products into their constituent parts, expressed as fractions or ratios, empowers consumers to make more informed choices and avoid potential pitfalls.
Stock Splits and Share Ownership: When 1 Becomes 2 (or 3)
Stock splits are a prime example of fractional dynamics in the market. When a company announces a 2-for-1 stock split, for every “1” share an investor owned, they now own “2.” While the total value of their holding remains the same immediately after the split, the share price is halved. A 3-for-1 split means 1 share becomes 3, and the price is divided by 3. This fractional adjustment impacts share count, price per share, and the liquidity of a stock, all without changing the underlying value of an investor’s total ownership fraction of the company. Understanding these mechanics prevents confusion and allows investors to adapt their strategies accordingly.
Mortgage and Loan Amortization: Breaking Down Payments into Principal and Interest
Mortgages and other installment loans are long-term commitments where each payment is meticulously divided into two fractional components: principal and interest. In the early years of a mortgage, a larger fraction of each payment goes towards interest, and a smaller fraction towards principal reduction. As the loan matures, this ratio gradually shifts, with an increasing fraction of the payment chipping away at the principal. An amortization schedule is essentially a detailed table of these evolving fractional allocations over the loan’s lifetime. Without understanding this fractional breakdown, borrowers might not grasp why their principal balance seems to decrease so slowly in the initial stages, or why making extra principal payments can significantly reduce the total interest paid (by changing the underlying fractional allocation earlier).
Empowering Financial Decisions Through Quantitative Literacy
The seemingly simple question “what is 1 2 1 3 in fraction form?” ultimately underscores the broader necessity for quantitative literacy in navigating the complexities of modern finance. It’s not just about arithmetic; it’s about critical thinking, problem-solving, and making financially intelligent decisions.
Beyond Simple Calculations: Making Informed Choices
Financial literacy extends beyond calculating a percentage or reducing a fraction. It’s about applying these foundational skills to evaluate financial products, compare investment opportunities, assess risks, and plan for the future. Understanding that a discount of “1 out of 3” (33%) is better than “1 out of 4” (25%) is simple arithmetic, but knowing when and where to apply such comparisons can save or earn significant amounts of money over time. It empowers consumers to see through misleading advertisements, identify predatory lending practices, and optimize their financial strategies.
For instance, comparing two investment options might involve understanding their expense ratios—the fraction of your investment that goes towards management fees. Even a seemingly small difference, like 1/100 (1%) versus 1/200 (0.5%), can translate to tens of thousands of dollars over a long investment horizon due to the compounding effect. These fractional differences have real-world financial consequences.
The Future of Financial Literacy: Embracing Numerical Fluency
In an increasingly data-driven world, numerical fluency, particularly the ability to understand and work with fractions, ratios, and percentages, is becoming as crucial as verbal literacy. Financial technologies and tools often present information in graphical or summary formats that require an underlying comprehension of these basic mathematical relationships. From interpreting economic indicators and market trends to personal financial dashboards, the capacity to deconstruct complex numbers into understandable fractions is invaluable. It equips individuals to participate more effectively in the economy, advocate for their financial interests, and build a secure future.

Conclusion
The unassuming question “what is 1 2 1 3 in fraction form?” serves as a powerful reminder of the fundamental role of numerical understanding in our financial lives. While the specific conversion might be straightforward depending on interpretation, the enduring lesson lies in the ubiquitous application of fractions, ratios, and percentages across every facet of personal finance and investing. From budgeting and managing debt to allocating investments and understanding loan structures, grasping how parts relate to a whole is not merely a mathematical exercise; it is an essential skill for making informed decisions, building wealth, and achieving financial independence. In a world awash with financial data, the ability to fluently interpret these numerical relationships is the cornerstone of robust financial health and a secure future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.