
Chronic acid reflux, or Gastroesophageal Reflux Disease (GERD), is more than a physical ailment; it is a significant financial burden. When you analyze the cost-benefit ratio of treatment, you quickly realize that the path to relief involves complex decisions regarding health insurance, pharmacy expenses, and long-term productivity. Managing your health is an investment, and like any investment, it requires a strategic approach to ensure you aren’t overspending on inefficient solutions while missing out on preventative measures that save money in the long run.
Assessing the True Cost of GERD Treatment
Before you can optimize your spending, you must understand where your money is going. Acid reflux treatment costs are multifaceted, often hidden within monthly grocery budgets, over-the-counter (OTC) pharmacy shelves, and mounting healthcare premiums.
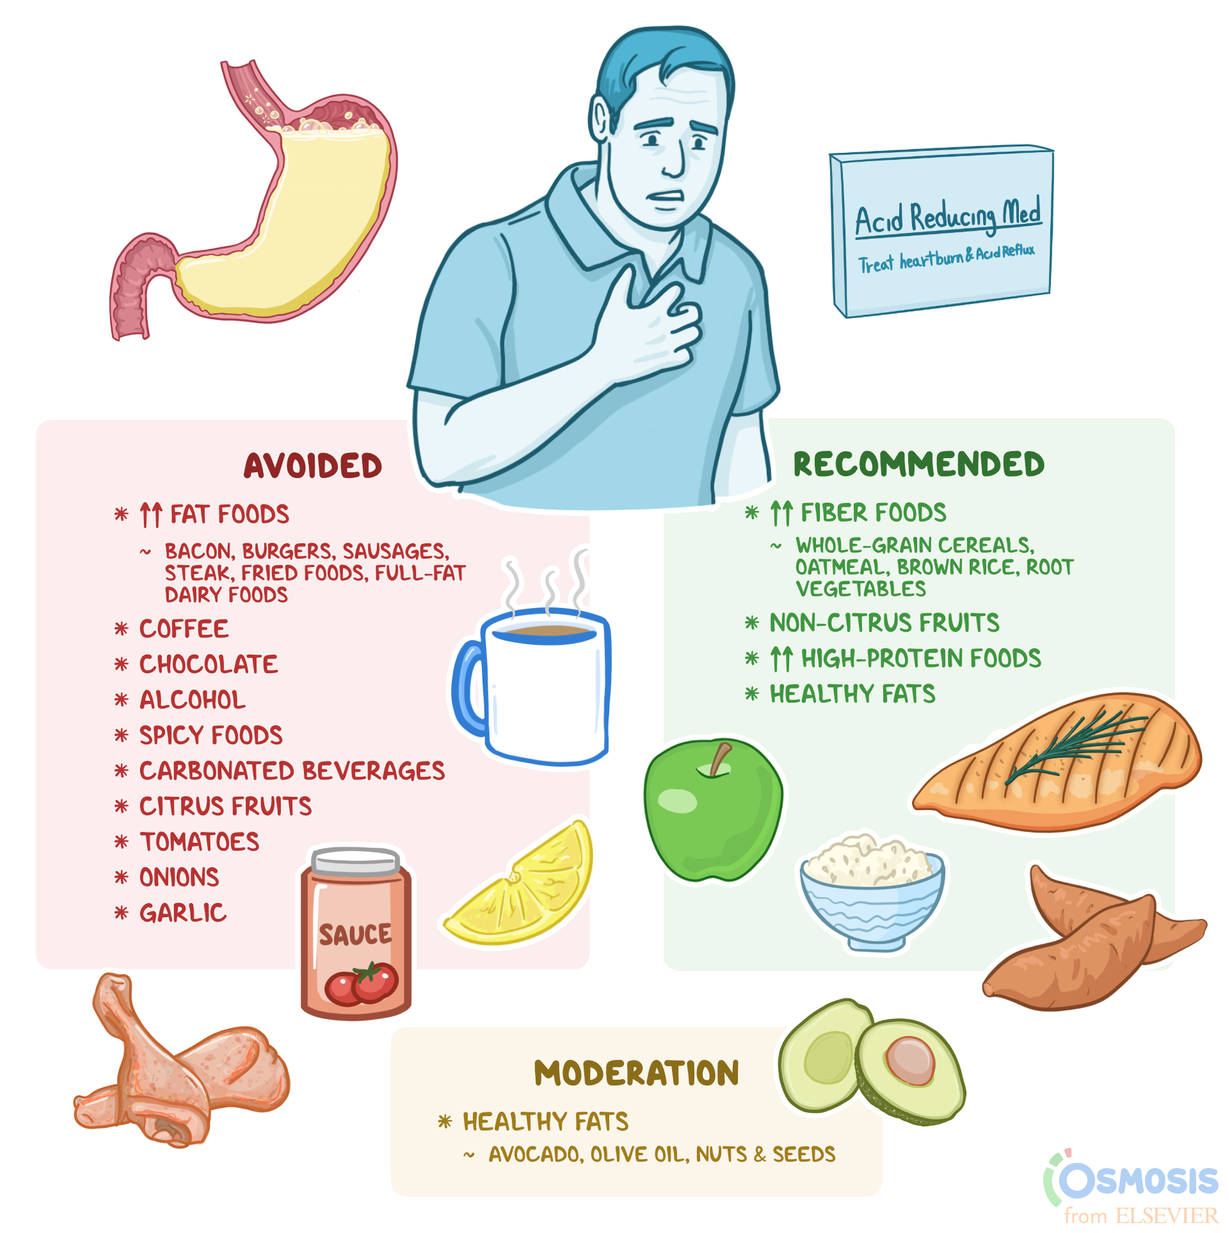
The Hidden Expenses of OTC Reliance
Many people treat acid reflux as a minor inconvenience, opting for endless cycles of antacids and H2 blockers. While a single bottle of medication seems inexpensive, the compounding effect over five or ten years represents a significant leak in your personal budget. By failing to address the root cause, you are essentially paying a “symptom tax.” Calculating your annual spend on OTC acid reducers often reveals that these recurring costs could have funded a more effective, permanent solution or contributed to a Health Savings Account (HSA) for professional intervention.
Productivity Loss as a Financial Drain
Beyond the direct cost of medication, there is the “opportunity cost” of the time lost to discomfort. Chronic reflux impacts sleep quality, which directly correlates to professional performance and energy levels. If you are operating at 80% capacity due to daily fatigue or recurring flare-ups, your earning potential is effectively reduced. Quantifying this impact is essential: treat your health as your most valuable asset. When your physical state is compromised, your ability to generate income is directly threatened.
Leveraging Financial Vehicles for Health Management
Once you have identified the drain on your finances, it is time to pivot toward tax-advantaged tools and strategic planning. Managing chronic health conditions requires a budget that accounts for high-deductible healthcare plans and elective procedures.
Maximizing Health Savings Accounts (HSAs)
For those with high-deductible health plans, the HSA is the most powerful tool in your financial arsenal. Contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses—including many GERD treatments, specific dietary consultations, and surgical interventions—are also tax-free. By shifting your “reflux budget” into an HSA, you are essentially giving yourself a discount on every dollar spent on relief. View your HSA not just as a medical fund, but as a strategic asset class that lowers your overall taxable income while securing your physical health.
Navigating Insurance and Specialist Coverage
Many patients settle for the first, least effective tier of treatment because they fear the high cost of a specialist. However, a strategic financial assessment often proves the opposite. Seeing a gastroenterologist for a definitive diagnosis and a long-term treatment plan is usually cheaper than three years of “guess-and-check” over-the-counter spending. Check your insurance plan for “Preferred Provider” rates and investigate whether your diagnostic procedures (like endoscopies) are covered under preventive care or deductible-satisfying benefits. Understanding your Explanation of Benefits (EOB) is the difference between losing thousands of dollars and staying within your annual out-of-pocket maximum.
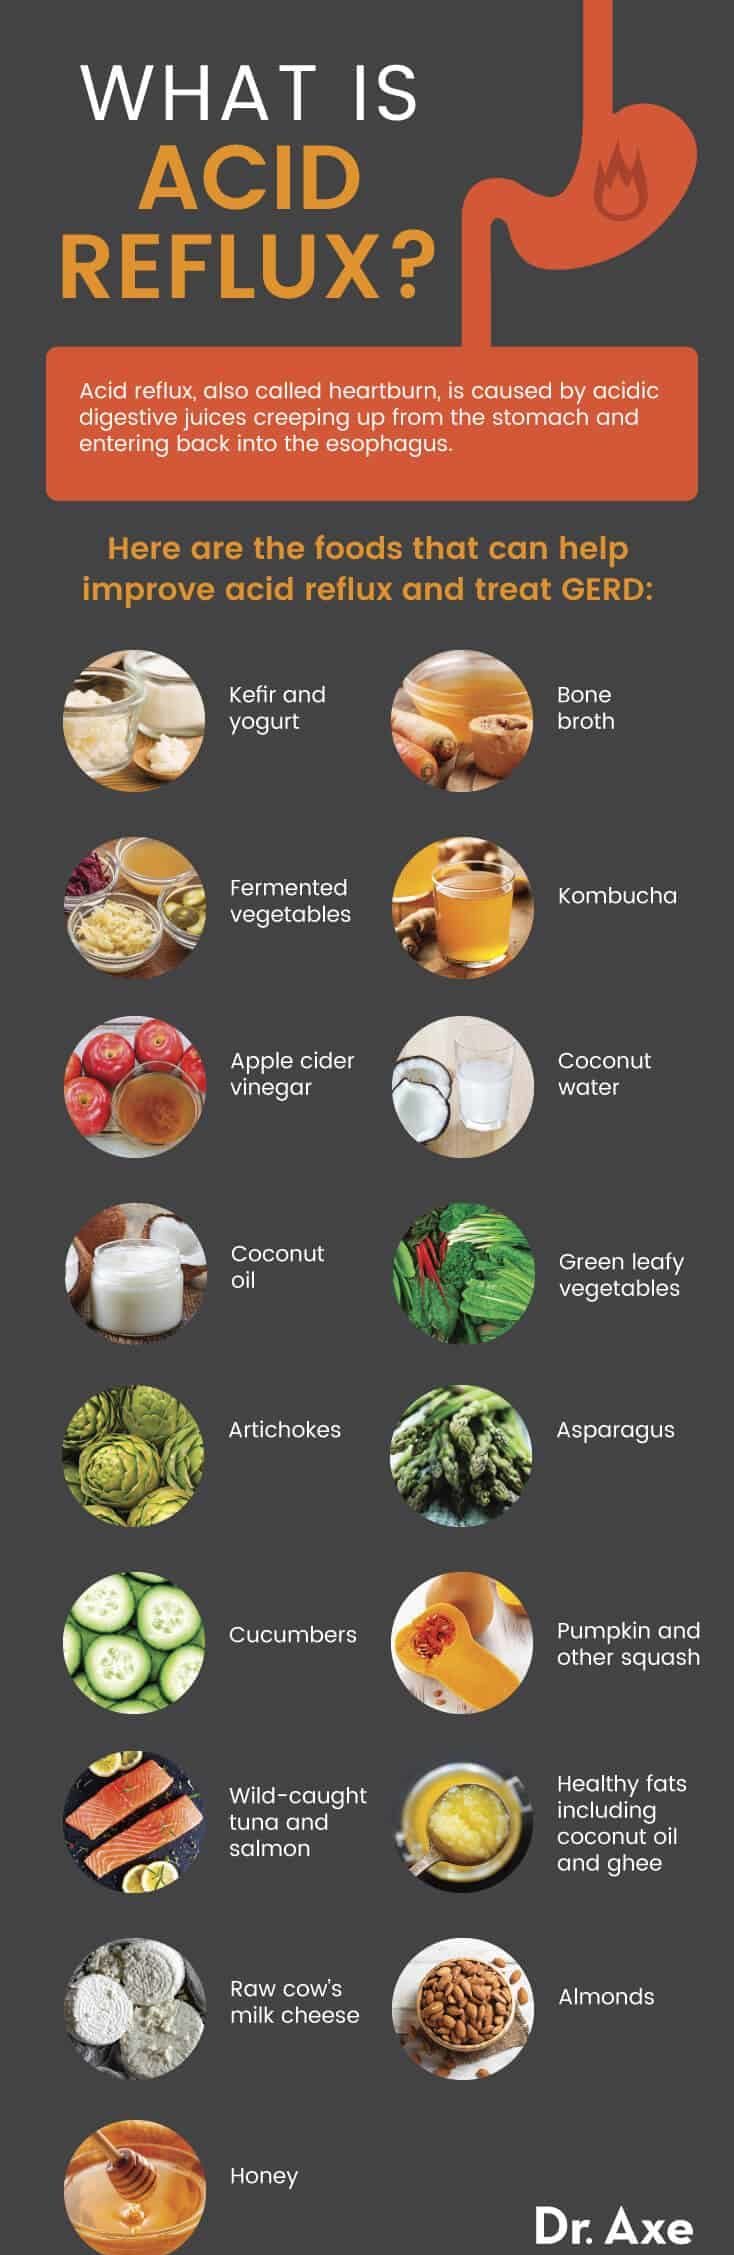
Dietary Investments: The ROI of Preventive Nutrition
The most effective “medicine” for acid reflux is often found in the grocery store. While high-quality, non-acidic foods may carry a higher price tag than processed alternatives, the return on investment (ROI) is significant when you factor in reduced medication requirements and improved systemic health.
Shifting from Reactive to Proactive Spending
Reframing your food budget is a fundamental shift in personal finance. Instead of viewing healthy, alkaline-friendly foods as a luxury, view them as a replacement for recurring pharmaceutical costs. If you can eliminate the need for daily medication by shifting your diet, you are not just spending money on food; you are essentially reallocating funds from a “symptom management” expense to a “wellness and maintenance” investment.
Long-Term Value of Preventative Care
Investing in a nutritionist or a specialized meal planning service might seem like an unnecessary expense, but these services often pay for themselves by reducing the need for emergency care or chronic medication. Many insurance providers now offer subsidies or full coverage for registered dietitians if a medical necessity (such as GERD) is documented. Research your benefits package thoroughly. Utilizing these “hidden” insurance perks is a hallmark of a financially literate approach to healthcare.
Building a Long-Term Healthcare Contingency Fund
Your financial planning should be as robust as your health management plan. Acid reflux is often a chronic condition that requires consistent monitoring, and your budget must reflect that.
The Three-Tiered Budgeting Strategy
To ensure your acid reflux management doesn’t derail your other financial goals, implement a three-tiered approach:
- The Emergency Fund: Keep a dedicated medical buffer to cover sudden spikes in diagnostic costs or insurance deductibles.
- The Maintenance Budget: Calculate the monthly cost of your required medication, supplements, and specialized food items, and allocate this as a fixed, non-negotiable expense.
- The Growth Fund: If you decide that a permanent, non-surgical, or surgical lifestyle change is necessary, start a “sinking fund” specifically for these costs. By saving $50 to $100 a month, you ensure that when you are ready to pursue a lasting solution, the cash is available without resorting to high-interest medical credit cards.
Avoiding the “Medical Debt” Trap
The greatest financial risk associated with chronic conditions like acid reflux is the tendency to turn to credit cards when an acute flare-up occurs and an unexpected procedure is needed. High-interest medical debt can erode your credit score and diminish your ability to invest in other areas. By maintaining an adequate buffer and utilizing tax-advantaged accounts like HSAs and Flexible Spending Accounts (FSAs), you protect your credit score and your future borrowing power.

Conclusion: Reflux Management as a Financial Discipline
Managing acid reflux is a masterclass in personal financial management. It requires you to audit your expenses, leverage tax-advantaged tools, maximize insurance benefits, and prioritize investments that yield long-term physical and fiscal returns. By shifting your mindset from seeing healthcare as a series of unavoidable costs to viewing it as a series of strategic decisions, you gain control over both your body and your balance sheet.
The most successful individuals are those who recognize that health and wealth are inextricably linked. Do not allow the physical discomfort of acid reflux to be compounded by the financial stress of inefficient spending. Audit your current costs, optimize your insurance usage, and start treating your health like the capital investment it truly is. Your future self—both physically and financially—will benefit from the discipline you apply today.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.