
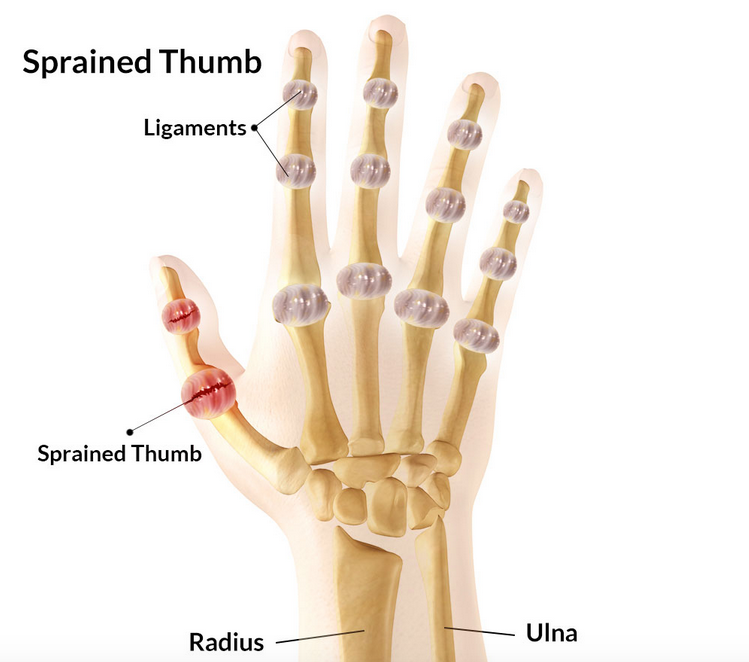
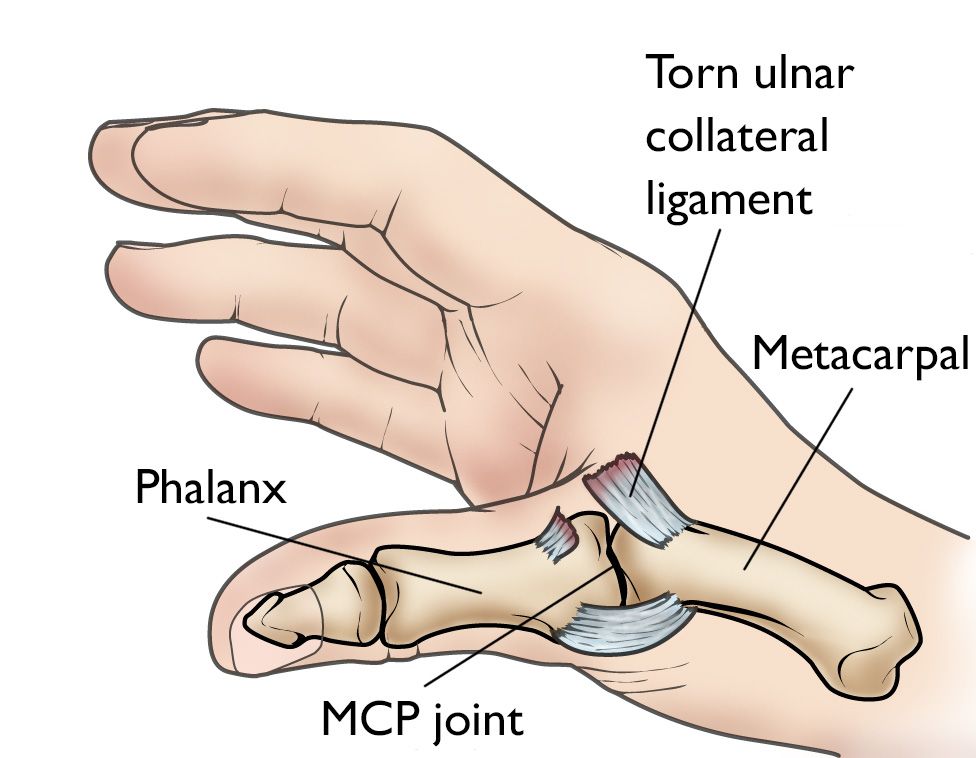
A jammed thumb might seem like a minor inconvenience—a fleeting moment of pain, a temporary impediment to daily tasks. Yet, beneath the surface of this common injury lies a surprising web of financial implications that can impact individuals, families, and even small businesses. From immediate medical costs to long-term productivity losses, understanding the monetary repercussions of such an event is crucial for robust financial planning and resilience. This article delves into the various financial dimensions of jamming your thumb, offering insights into how to prepare for, mitigate, and recover from its economic fallout.
The Immediate Financial Blow: Medical Costs and Lost Income
When an injury occurs, the first thoughts are usually about pain and recovery. However, the financial clock starts ticking almost immediately, ushering in a series of direct costs and potential income disruptions that can quickly escalate.
Understanding Direct Medical Expenses
The path from injury to recovery is often paved with medical bills, even for seemingly minor incidents like a jammed thumb. The nature of these costs can vary significantly based on the severity of the sprain or fracture and the chosen care provider.
Emergency Room vs. Urgent Care
The decision of where to seek treatment can have a profound impact on your wallet. An emergency room visit, while appropriate for severe injuries, typically comes with higher facility fees, physician charges, and diagnostic costs compared to an urgent care center. For a jammed thumb, which might require an X-ray to rule out a fracture, an urgent care clinic often provides a more cost-effective and equally effective solution. Misjudging the severity and opting for an ER when urgent care would suffice can lead to hundreds, if not thousands, of dollars in unnecessary expenses.
Imaging and Diagnostics (X-rays, MRI)
To accurately diagnose a jammed thumb, medical professionals often order imaging tests. An X-ray is standard to check for fractures, and while generally less expensive than other imaging, its cost can still range from tens to hundreds of dollars, depending on the facility and your insurance coverage. In more complex cases, or if a fracture isn’t immediately apparent but pain persists, an MRI might be ordered to assess soft tissue damage. MRIs are considerably more expensive, easily running into four figures, highlighting the escalating costs if the diagnosis isn’t straightforward.
Consultation Fees and Specialist Referrals
Initial consultations with a general practitioner or urgent care physician incur their own fees. If the injury is severe, or if the initial treatment doesn’t yield sufficient recovery, a referral to a specialist—such as an orthopedic surgeon or hand therapist—becomes necessary. Each specialist visit adds another layer of cost, including initial consultation fees, follow-up appointments, and potentially specialized procedures or therapies.
Medications and Therapeutic Devices (splints, braces)
Beyond the diagnostic and consultation fees, there are the tangible items needed for recovery. Over-the-counter pain relievers are a minor expense, but prescription anti-inflammatories or stronger pain medication will add to the bill. More significantly, a jammed thumb often requires immobilization, necessitating a splint, brace, or even a custom cast. The cost of these devices, along with any related supplies like wraps or medical tape, can quickly accumulate, particularly if custom-fitted or specialized models are required.
The Cost of Lost Productivity
Beyond the direct medical bills, a jammed thumb can significantly impact your ability to work, leading to a loss of income and productivity. The extent of this impact varies greatly depending on your employment status and the nature of your work.
Impact on Salaried Employees (Sick leave, reduced output)
For salaried employees, a jammed thumb might mean utilizing sick leave days, which can deplete a limited bank of paid time off. Even if sick leave is available, an injured thumb can drastically reduce efficiency, especially for roles requiring typing, writing, or manual dexterity. This reduced output can lead to missed deadlines, increased workload for colleagues, and potentially impact performance reviews, indirectly affecting future raises or promotions. While the direct income might be stable, the career cost can be real.
Challenges for Hourly Workers and Gig Economy Participants (No work, no pay)
The financial repercussions are often most acute for hourly workers and those in the gig economy. For these individuals, the principle is often “no work, no pay.” A jammed thumb could mean inability to perform tasks that require fine motor skills, lifting, or continuous physical activity. Missing even a few days can lead to a significant income gap, making it difficult to cover living expenses, especially for those living paycheck to paycheck. The pressure to return to work prematurely, risking further injury, becomes a dangerous financial dilemma.
Self-Employed and Business Owners: The Ripple Effect
For the self-employed or small business owners, a jammed thumb can create a devastating ripple effect. Not only do they face the direct medical costs, but their income is directly tied to their ability to perform their work. If their business relies on their manual dexterity, client meetings, or physical presence, an injury can bring operations to a standstill. This leads to lost revenue, potential client dissatisfaction, and the financial burden of still having to cover business overheads even without income. The recovery period for such individuals can be a critical test of their business’s financial resilience and continuity planning.
Beyond the Obvious: Indirect Financial Consequences
While medical bills and lost wages are the immediate concerns, the financial ramifications of a jammed thumb can extend far beyond, touching various aspects of personal finance and lifestyle.
Navigating Insurance and Claims
Successfully managing the financial fallout of an injury often hinges on adeptly navigating the complex world of insurance.
Health Insurance: Deductibles, Co-pays, Out-of-Pocket Max
Even with robust health insurance, out-of-pocket expenses can be substantial. Deductibles, which must be met before insurance coverage kicks in, can range from a few hundred to several thousand dollars. Co-pays for doctor visits and a percentage of costs (co-insurance) for diagnostics and specialist care further add to the financial burden. Understanding your plan’s out-of-pocket maximum is vital, as this represents the absolute most you will pay in a given year for covered medical expenses, providing a crucial cap on your exposure.
Workers’ Compensation: When Your Thumb Jams at Work
If the injury occurs during work-related activities, workers’ compensation insurance is designed to cover medical expenses and a portion of lost wages. However, the claims process can be intricate and sometimes contentious. Employees must report the injury promptly, follow specific procedures, and often deal with adjusters who may scrutinize the claim. Delays in approval or disputes over the severity of the injury can prolong financial hardship, making it essential to understand your rights and the reporting protocols.
Disability Insurance: Short-term and Long-term considerations
For more severe or prolonged injuries that prevent work, disability insurance becomes a critical safety net. Short-term disability typically covers a percentage of income for a few weeks to several months, while long-term disability kicks in after a waiting period and can provide income replacement for years. The availability and terms of these policies vary—some employers offer them, others require private purchase. Understanding your policy’s waiting periods, benefit amounts, and definition of “disability” is paramount before an injury strikes.
The Hidden Costs of Recovery and Adaptation
Recovery from an injury is rarely a straightforward, cost-free process. Several less obvious expenses can chip away at your financial stability.
Transportation to Appointments
Frequent visits to doctors, specialists, or physical therapists can incur significant transportation costs. Whether it’s gasoline, public transport fares, or even ride-sharing services if you’re unable to drive, these recurring expenses can add up over weeks or months of recovery.
Childcare or Elder Care if incapacitated
If the injured thumb significantly impacts your ability to perform daily tasks, you might need to hire temporary help for childcare, elder care, or even basic household chores like cooking and cleaning. These services, essential for maintaining daily life, represent an unexpected and potentially substantial expense.
Ergonomic Adjustments or Specialized Tools
For individuals whose work or hobbies heavily rely on their hands, a lingering thumb injury might necessitate ergonomic adjustments to workstations or the purchase of specialized tools and assistive devices. Adaptive keyboards, voice recognition software, or ergonomic mice, while beneficial for long-term comfort and prevention, represent an upfront financial outlay.
Psychological Impact and its Financial Strain
The stress, frustration, and anxiety associated with an injury and its financial repercussions can also take a toll. This psychological burden can lead to decreased motivation, impaired decision-making, and even require professional mental health support, adding another layer of financial strain that is often overlooked.
Proactive Financial Strategies for Unexpected Injuries
While we can’t always prevent accidents, we can certainly prepare financially for them. Proactive measures are key to mitigating the economic shock of a sudden injury like a jammed thumb.
Building a Robust Emergency Fund
An emergency fund is the cornerstone of financial resilience, acting as a buffer against unforeseen expenses and income disruptions.
The “3-6 Months of Expenses” Rule
Financial experts commonly recommend having 3 to 6 months’ worth of essential living expenses saved in an easily accessible, liquid account. This fund can cover medical deductibles, co-pays, lost wages, and other unexpected costs without forcing you into debt or derailing your long-term financial goals. For those with less stable incomes, a larger fund of 6-12 months might be advisable.
Accessing Funds: Savings Accounts, HELOCs (as a last resort)
Your emergency fund should reside in a high-yield savings account or a money market account, offering both liquidity and a modest return. While less ideal, a Home Equity Line of Credit (HELOC) can serve as a secondary emergency resource in dire situations, but it should be approached with caution due to interest payments and the risk to your home equity. Credit cards, with their high interest rates, should generally be avoided for emergency expenses if possible.
Evaluating and Optimizing Your Insurance Coverage
Insurance is your primary defense against significant financial losses due to injury. Regularly reviewing your policies is paramount.
Reviewing Health Insurance Policies Annually
Take advantage of the annual enrollment period to review your health insurance plan. Understand your deductibles, co-pays, and out-of-pocket maximum. Assess if your current plan adequately meets your needs, especially if your health status or financial situation has changed. Consider higher deductible plans with lower premiums if you have a substantial emergency fund, or more comprehensive plans if you anticipate higher medical needs.
Considering Supplemental Disability or Accident Insurance
Beyond standard health insurance, supplemental policies can provide additional layers of protection. Accident insurance pays a lump sum benefit directly to you upon diagnosis of a covered injury, which can be used for anything from medical bills to daily living expenses. Private disability insurance can bridge income gaps if your employer’s plan is insufficient or non-existent, offering crucial peace of mind for self-employed individuals or those in specialized roles.
Understanding Workers’ Comp Benefits Before You Need Them
If you’re employed, familiarize yourself with your company’s workers’ compensation policies and procedures. Know who to report an injury to, the timelines for reporting, and what benefits are typically covered. This knowledge can streamline the claims process and prevent costly delays should an workplace injury occur.
Minimizing Risk and Financial Exposure
Prevention is often the most cost-effective strategy. Investing in safety and making informed lifestyle choices can significantly reduce the likelihood and financial impact of injuries.
Workplace Safety and Ergonomics (Financial Investment in Prevention)
Employers and employees alike have a role to play in fostering a safer environment.
Employer Responsibility and Cost-Benefit Analysis of Safety Programs
For businesses, investing in robust safety programs, ergonomic assessments, and proper training isn’t just a regulatory requirement; it’s a sound financial decision. Preventing injuries reduces workers’ compensation claims, lost productivity, legal fees, and reputational damage. A small upfront investment in safety equipment or ergonomic workstations can yield substantial long-term savings.
Personal Responsibility: Awareness and Protective Gear
Employees also bear personal responsibility. Being aware of potential hazards, using protective gear (like gloves in certain occupations or sports), and following safety protocols can significantly reduce personal injury risk. Taking breaks and stretching to prevent repetitive strain injuries, which can weaken joints and make them more susceptible to acute injuries, is also crucial.
Lifestyle Adjustments and Injury Prevention
Personal habits and choices play a critical role in injury prevention.
The Cost of Neglecting Small Pains
Ignoring minor aches and pains can lead to more significant injuries down the line. A consistently sore thumb, if left unaddressed, could make it more vulnerable to a serious sprain or fracture during an otherwise minor incident. The cost of an early doctor’s visit or physical therapy session pales in comparison to the financial burden of a full-blown injury.
Investing in Physical Health (e.g., strength training, flexibility)
Maintaining overall physical health through regular exercise, including strength training and flexibility exercises, can build resilience in joints and muscles. Stronger hands and wrists are less prone to injury. This “investment” in your physical well-being translates directly into reduced healthcare costs and increased earning potential by minimizing downtime.
The Long-Term Financial Horizon: Recovering and Rebuilding
An injury’s financial narrative doesn’t end with the last medical bill. It extends into how you manage your finances during recovery and how you plan for the future.
Budgeting During Recovery
Adapting your spending habits is often necessary when facing reduced income or increased expenses.
Adjusting Spending Habits Temporarily
During a period of reduced income or increased medical bills, it’s prudent to temporarily cut back on non-essential spending. This might mean fewer restaurant meals, postponing non-urgent purchases, or reducing entertainment expenses to ensure critical needs are met.
Prioritizing Essential Expenses
Focus on covering your essential expenses first: housing, utilities, food, transportation to medical appointments, and critical debt payments. Non-essential categories can be reduced or eliminated until your financial situation stabilizes.
Financial Planning Post-Injury
An injury can be a wake-up call, prompting a re-evaluation of your financial strategy.
Reassessing Financial Goals
Take time to review your short-term and long-term financial goals. Did the injury set you back significantly? Do you need to adjust timelines for major purchases, retirement savings, or debt repayment? This reassessment allows you to create a realistic path forward.
The Value of Financial Advising in Times of Crisis
When dealing with complex financial challenges resulting from an injury—such as insurance claims, budgeting under reduced income, or managing large medical debts—seeking guidance from a qualified financial advisor can be invaluable. They can help you navigate difficult decisions, optimize your resources, and develop a robust plan for recovery and future security.
In conclusion, a seemingly innocuous jammed thumb can unravel a surprisingly intricate tapestry of financial challenges. By understanding the immediate and indirect costs, proactively building emergency funds, optimizing insurance coverage, and embracing preventative measures, individuals can significantly cushion the economic blow and maintain their financial stability even when unexpected injuries occur.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.