
Filing for divorce is a monumental life decision, often fraught with emotional turmoil. Beyond the personal and relational complexities, however, lies an equally challenging financial landscape that demands careful navigation. For many, the financial implications of divorce are overwhelming, touching every aspect of their personal economy, from assets and debts to future income and retirement. Understanding the financial process and preparing for its various stages is not just advisable; it’s essential for safeguarding your financial well-being and securing your future. This guide aims to demystify the financial journey of divorce, offering professional and insightful guidance to help you through this challenging transition.
The Immediate Financial Aftermath: Initial Considerations
The moment divorce papers are filed, a series of financial dominoes begin to fall. The initial phase is critical for establishing financial stability, gathering essential information, and understanding the immediate costs and protections in place.
Securing Your Financial Information and Assets
One of the first and most critical steps is to compile a complete and accurate picture of your financial standing. This means gathering all relevant documents before, or immediately after, filing. This includes bank statements, investment portfolios, retirement accounts, tax returns (going back several years), property deeds, mortgage statements, loan documents, and insurance policies. Digital access to shared accounts should be documented, and steps should be taken to ensure no single party can unilaterally deplete joint accounts or sell off significant assets without proper accounting. In many jurisdictions, automatic temporary restraining orders (ATROs) go into effect upon filing, preventing either party from disposing of assets without court approval, but proactive documentation remains paramount. You might also consider opening a new, separate bank account for your individual income and expenses to create clear boundaries.
Understanding Temporary Financial Orders
While the divorce process unfolds, courts often issue temporary financial orders to maintain the status quo and ensure both parties’ immediate needs are met. These orders can cover temporary spousal support (alimony), child support, and even who gets to reside in the marital home or use specific vehicles. These temporary arrangements are not necessarily indicative of the final settlement but are crucial for day-to-day financial management during the often lengthy legal proceedings. Understanding how these orders are calculated and enforced is vital. They are typically based on immediate needs and income disparities, designed to prevent financial hardship for either spouse or their children during the interim period.
The Cost of the Divorce Process Itself
Divorce is rarely inexpensive. Legal fees, court costs, and potential expert witness fees (for property appraisals, business valuations, or forensic accounting) can quickly accumulate. It’s important to discuss fee structures with your legal counsel upfront. Some attorneys charge hourly rates, others may offer flat fees for certain services, and retainers are standard practice. Beyond legal fees, there might be costs associated with moving, setting up a new household, or even therapy. Budgeting for these immediate and ongoing expenses is crucial. Exploring alternative dispute resolution methods like mediation or collaborative divorce can sometimes reduce costs compared to traditional litigation, by minimizing court appearances and fostering cooperation.
Navigating Asset and Debt Division
Perhaps the most complex financial aspect of divorce is the equitable division of marital assets and debts. The principles guiding this division can vary significantly depending on state laws, primarily whether your state is a community property state or an equitable distribution state.
Differentiating Marital vs. Separate Property
A cornerstone of asset division is distinguishing between marital (or community) property and separate property. Generally, marital property includes all assets and debts acquired by either spouse during the marriage, regardless of whose name is on the title. Separate property typically includes assets owned before the marriage, inheritances, and gifts received individually during the marriage, provided they were not commingled with marital assets. The line can become blurred when separate property is used to acquire marital assets or when marital funds are used to improve separate property. Understanding these distinctions is crucial for accurately valuing and dividing your estate.
Valuing Complex Assets (Businesses, Investments, Pensions)
While bank accounts are straightforward to divide, complex assets present significant challenges.
-
Businesses: If one or both spouses own a business, its valuation becomes a critical and often contentious point. This usually requires a qualified business appraiser to determine fair market value, considering factors like revenue, assets, liabilities, and goodwill.
-
Investments: Stocks, bonds, mutual funds, and other investment accounts need to be valued as of a specific date, often the date of separation or the trial. Capital gains taxes and liquidity should also be considered in their division.
-
Pensions and Retirement Accounts: These are often among the largest assets in a divorce. Qualified Domestic Relations Orders (QDROs) are typically required to divide 401(k)s, pensions, and other qualified plans without incurring immediate tax penalties. Dividing these assets involves complex actuarial calculations, especially for defined-benefit pensions.
-
Real Estate: The marital home, vacation properties, and other real estate assets require professional appraisals. Decisions then need to be made about whether to sell the properties and split the proceeds, or if one spouse will buy out the other’s share, often through refinancing.
Strategies for Debt Allocation and Mitigation
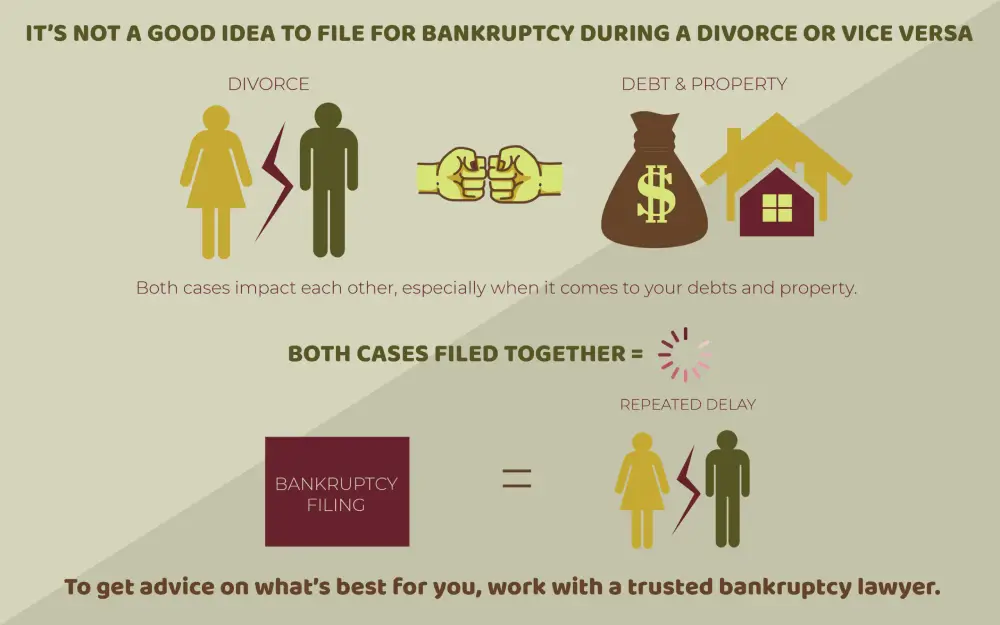
Just as assets are divided, so too are marital debts. This includes mortgages, car loans, credit card debt, and personal loans. The court’s goal is to distribute these liabilities equitably. It’s crucial to understand that even if a divorce decree assigns a debt to your ex-spouse, the original creditor may still hold you liable if your name is on the account. Strategies for managing debt include:
-
Refinancing: If one spouse keeps a property or vehicle, they might need to refinance it solely in their name to release the other from responsibility.
-
Closing Joint Accounts: Joint credit cards should ideally be paid off and closed, or at least removed from one spouse’s name, to prevent future liability.
-
Monitoring Credit Reports: Regularly checking your credit report is essential to ensure that debts assigned to your ex-spouse are being paid as agreed and to detect any unauthorized activity.
Spousal and Child Support: Long-Term Financial Planning
Beyond asset division, divorce often involves ongoing financial support obligations that significantly impact the long-term financial stability of both parties.
Determining Alimony (Spousal Support)
Alimony, or spousal support, is financial assistance paid by one spouse to the other after a divorce. Its purpose is to help the recipient spouse become self-sufficient or to maintain a lifestyle similar to that enjoyed during the marriage, especially in long-term marriages. Factors influencing alimony awards include the length of the marriage, the income and earning capacity of each spouse, the standard of living during the marriage, the age and health of each spouse, and contributions to the other spouse’s education or career. Alimony can be temporary (rehabilitative), for a fixed term, or, less commonly, permanent. The tax implications of alimony have also changed, with alimony payments no longer deductible by the payer or taxable to the recipient for divorces finalized after 2018 (federally, though state laws may vary). This change impacts net financial outcomes for both parties.
Calculating and Managing Child Support Obligations
Child support is designed to ensure that both parents contribute financially to their children’s upbringing. State guidelines typically use a formula to calculate child support, taking into account factors like each parent’s income, the number of children, the custody schedule, and expenses like health insurance and childcare. These guidelines aim to provide a fair and consistent approach to children’s financial needs. Child support payments are typically non-taxable for the recipient and non-deductible for the payer. It’s important to understand that child support orders can be modified if there’s a significant change in circumstances, such as a substantial change in income for either parent or a shift in the custody arrangement.
Adjusting Financial Plans Post-Divorce for Support Payments
Both payers and recipients of support payments must adjust their long-term financial plans accordingly. For the payer, these obligations will reduce disposable income, requiring budget adjustments and potentially impacting savings or investment goals. For the recipient, support payments provide a new income stream that needs to be factored into their budget, savings, and retirement planning. It’s crucial for recipients to view alimony, especially temporary alimony, not as a permanent solution but as a bridge to financial independence. Developing new financial goals that account for these ongoing payments is a critical step towards financial stability.
Protecting Your Financial Future Post-Divorce
Divorce is not just an ending; it’s also a new beginning. Strategically planning for your post-divorce financial future is paramount to rebuilding and thriving.
Re-evaluating Your Budget and Financial Goals
Post-divorce, your financial situation will undoubtedly look different. You may have a single income, new expenses, or different assets. Creating a new, realistic budget that reflects your current income and expenses is essential. This includes accounting for new housing costs, utilities, transportation, and personal spending. Simultaneously, it’s an opportune time to re-evaluate your financial goals. Do you need to adjust your retirement savings strategy? Are there new short-term goals, like buying a new home or investing in education? A financial planner can be invaluable in helping you craft a new financial roadmap tailored to your individual circumstances.
Rebuilding Credit and Establishing Independent Financial Identity
If your credit history was intertwined with your spouse’s, or if joint debts were mismanaged during the divorce, your credit score might take a hit. It’s crucial to actively work on rebuilding and establishing your independent financial identity. This might involve opening new credit accounts solely in your name, making timely payments, and regularly monitoring your credit report. If joint accounts could not be closed, ensure you have documentation that you are no longer responsible for those debts post-divorce, though creditors may still pursue you if your name remains. Establishing a strong credit profile independently will be vital for future loans, mortgages, or other financial endeavors.
Updating Beneficiaries and Estate Planning
Divorce legally severs many financial ties, but it doesn’t automatically update all of them. It is imperative to review and update all beneficiary designations on life insurance policies, retirement accounts (401(k)s, IRAs), and other investment accounts. Failing to do so could result in your ex-spouse receiving assets that you intended for others. Similarly, your estate plan (will, trusts, powers of attorney) must be revised to reflect your current wishes. This ensures that your assets are distributed according to your preferences and that someone you trust is appointed to make financial and medical decisions on your behalf if you become incapacitated.
Tax Implications of Divorce Settlements
The financial decisions made during a divorce have significant tax implications. Beyond alimony, the division of assets can trigger capital gains taxes if highly appreciated assets are sold. The transfer of assets between spouses “incident to divorce” is generally not a taxable event, but future sales of those assets might be. Who claims children as dependents for tax purposes can also impact tax liability and eligibility for credits. It’s crucial to consult with a tax professional or a Certified Divorce Financial Analyst (CDFA) to understand how your settlement impacts your current and future tax obligations and to structure the agreement in the most tax-efficient manner possible.
Leveraging Financial Expertise During Divorce
Given the intricate financial landscape of divorce, attempting to navigate it alone can lead to costly mistakes and long-term financial instability. Engaging financial professionals can provide invaluable support and strategic guidance.
The Role of a Divorce Financial Analyst (CDFA)
A Certified Divorce Financial Analyst (CDFA) specializes in the financial aspects of divorce. They can help you understand the long-term financial impact of different settlement proposals, analyze asset and debt division, evaluate pension and retirement plan options, assess tax consequences, and project future cash flows. A CDFA works alongside your attorney, providing a detailed financial picture that empowers you to make informed decisions and negotiate effectively, often leading to more equitable and sustainable financial outcomes. Their expertise can uncover hidden assets, ensure accurate valuations, and help prevent costly oversights.
Engaging Financial Planners and Tax Professionals
While a CDFA focuses specifically on the divorce process, a broader team of financial professionals can be beneficial. A financial planner can help you establish your new budget, set post-divorce financial goals, develop an investment strategy, and plan for retirement. They provide a forward-looking perspective, helping you rebuild your financial life. A tax professional is essential for understanding the immediate and long-term tax implications of your divorce settlement. They can help you plan for tax liabilities, optimize deductions, and ensure compliance with tax laws, especially as your filing status changes.
Utilizing Financial Tools and Software for Organization
In today’s digital age, various financial tools and software can assist in organizing your financial life during and after divorce. Personal finance management software can help track expenses, create budgets, and monitor accounts. Secure cloud storage can be used to organize and share financial documents with your legal and financial team. Spreadsheet programs are invaluable for creating detailed asset and debt inventories. While these tools don’t replace professional advice, they can significantly streamline the data collection and organization process, making it easier to manage your finances and prepare for negotiations.
Filing for divorce is a profound journey, but by approaching the financial aspects with a clear strategy, informed decisions, and the right professional support, you can emerge with a solid foundation for a secure and prosperous future. Understanding “what happens when you file for divorce” from a financial perspective is the first step towards taking control of your new beginning.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.