
The decision to use birth control is often multifaceted, encompassing personal health, lifestyle choices, and future planning. While the immediate concern when a birth control pill is missed typically revolves around health and potential pregnancy, it’s crucial to examine this common occurrence through a lens that is often overlooked yet profoundly impactful: finance. Missing a birth control pill isn’t just a medical lapse; it can trigger a cascade of financial consequences, ranging from immediate out-of-pocket expenses to monumental long-term shifts in personal and household economics. Understanding these financial implications is paramount for comprehensive financial planning and risk management in personal health.

The Immediate Financial Implications of a Missed Pill
A missed birth control pill often necessitates immediate action, and many of these actions come with a price tag. While these costs might seem minor individually, they represent unplanned expenditures that can disrupt a carefully constructed personal budget. Ignoring or underestimating these immediate financial ripples can lead to stress and force reallocations from other financial priorities.
Cost of Emergency Contraception
The most direct and immediate financial consequence of a missed birth control pill, especially if unprotected intercourse has occurred, is the potential need for emergency contraception (EC). Options like levonorgestrel-based pills (e.g., Plan B One-Step) or ulipristal acetate (e.g., Ella) vary significantly in price. Over-the-counter options can range from $40 to $60, while prescription-only EC might fall within a similar range but could be covered by some insurance plans, albeit often with a co-pay. The cost isn’t just the pill itself; it’s the urgent need to acquire it, potentially incurring transportation costs or requiring a rush trip to a pharmacy that might not be the most cost-effective option. For individuals on tight budgets, even this relatively small, unplanned expense can create financial strain, diverting funds from necessities or savings goals.
Potential Medical Consultations and Tests
Beyond emergency contraception, a missed pill may prompt a medical consultation. This could be to discuss the safest course of action, confirm the efficacy of EC, or address anxieties. A doctor’s visit typically incurs a co-pay if insured, or a full consultation fee if uninsured, which can range from $75 to $200 or more. Furthermore, if there’s a prolonged period of uncertainty, or if a pregnancy scare persists, individuals might opt for pregnancy tests. While inexpensive home kits are widely available (often $10-$20 for a pack), multiple tests over time add up. More definitive blood tests administered by a healthcare provider, while highly accurate, also carry a cost, either through co-pays or direct billing. These recurrent, potentially anxiety-driven medical expenditures, though part of necessary health management, are direct financial consequences of the original missed pill.
The Hidden Costs of Anxiety and Stress
The financial impact of a missed birth control pill extends beyond direct medical expenses to the less tangible, yet very real, “hidden costs” of anxiety and stress. The worry over a potential unplanned pregnancy can significantly impact an individual’s mental well-being and productivity. This stress can manifest as reduced focus at work, leading to decreased output or even missed workdays, translating directly into lost income or missed opportunities for advancement. For hourly workers, this impact is immediate. For salaried professionals, prolonged stress can affect job performance reviews, potentially hindering bonuses or raises. Furthermore, some individuals may seek professional help to manage this anxiety, such as therapy sessions, which, even with insurance, incur co-pays that represent an additional unplanned financial outlay. While difficult to quantify precisely, the erosion of productivity and the expense of mental health support contribute to the overall financial burden stemming from a simple missed pill.
Long-Term Financial Ramifications of Unplanned Pregnancy
While the immediate financial implications are noteworthy, they pale in comparison to the potential long-term financial ramifications should a missed pill lead to an unplanned pregnancy. This is where a seemingly small oversight can trigger a complete re-evaluation and restructuring of an individual’s or couple’s entire financial future.
The Astonishing Cost of Raising a Child
One of the most profound financial impacts of an unplanned pregnancy is the astonishing cost of raising a child. Multiple studies, including those by the U.S. Department of Agriculture (USDA) before they discontinued the annual report, estimated that raising a child from birth to age 18 could cost upwards of $233,610 for a middle-income family (excluding college expenses). Adjusted for inflation, this figure is now even higher. This figure encompasses housing, food, transportation, healthcare, childcare, education, and miscellaneous expenses. The first few years alone are incredibly expensive due to initial medical bills for delivery, nursery setup, diapers, formula, and potentially significant childcare costs. An unplanned pregnancy forces immediate financial adjustments for these expenses, often requiring individuals to dip into savings, take on debt, or significantly alter their spending habits, potentially delaying major financial goals like homeownership, retirement savings, or further education.
Impact on Career and Income Potential
An unplanned pregnancy can dramatically alter career trajectories and income potential, particularly for women. Maternity leave, while often legally protected, may be unpaid or only partially paid, leading to an immediate reduction in household income. Beyond maternity leave, the demands of childcare often necessitate career breaks, reduced working hours, or a shift to lower-paying, more flexible jobs. This “motherhood penalty” can result in significant lifetime earnings losses. For some, re-entering the workforce after an extended break can be challenging, requiring retraining or accepting entry-level positions. Even for fathers, the increased financial responsibility can lead to choices that prioritize immediate income over long-term career growth or educational pursuits, potentially limiting their earning ceiling. These career shifts are not merely temporary; they can have a compounding effect on lifetime wealth accumulation, retirement savings, and overall financial security.
Healthcare and Insurance Considerations
Adding a dependent to a health insurance plan invariably increases premiums and out-of-pocket costs. Deductibles and co-pays will apply to all healthcare services for the child, from routine check-ups and vaccinations to unexpected illnesses and emergencies. For uninsured individuals, the costs associated with pregnancy, childbirth, and infant care can be catastrophic, easily running into tens of thousands of dollars, even for an uncomplicated birth. Furthermore, an unplanned pregnancy might reveal pre-existing conditions in either the mother or the child that require specialized and expensive care. Even with robust insurance, the cumulative healthcare costs over a child’s lifetime represent a substantial financial commitment that must be factored into an already stretched budget, often requiring adjustments to other areas of personal finance.

Housing and Lifestyle Adjustments
The arrival of a child often necessitates significant housing and lifestyle adjustments, all of which have financial implications. A small apartment might no longer be suitable, leading to the need for a larger living space, which typically means higher rent or a larger mortgage payment. Renovations to existing homes to accommodate a child can also be costly. Beyond housing, lifestyle changes are inevitable. Budget lines for discretionary spending, travel, entertainment, and personal indulgences often shrink considerably to accommodate childcare costs, baby supplies, and other child-related expenses. Transportation needs may change, potentially requiring the purchase of a larger, more family-friendly vehicle, adding car payments, insurance, and fuel costs to the budget. These lifestyle shifts aren’t just about sacrificing luxuries; they can fundamentally alter the ability to save, invest, and achieve other personal financial milestones.
Proactive Financial Planning for Contraception and Beyond
Given the significant financial implications, proactive financial planning for contraception is not just wise; it’s an essential component of responsible personal finance. Integrating reproductive health decisions into one’s financial strategy can help mitigate risks and ensure greater financial stability.
Budgeting for Birth Control Methods
Different birth control methods come with varying costs, and these should be factored into a personal budget. Oral contraceptive pills typically involve a monthly co-pay or out-of-pocket expense. Long-acting reversible contraceptives (LARCs) like IUDs or implants have a higher upfront cost, potentially hundreds or even over a thousand dollars, but offer years of protection, making their annual cost lower in the long run. Barrier methods like condoms are relatively inexpensive. Understanding the cost-effectiveness of various methods over time, considering insurance coverage, and consciously budgeting for the chosen method can prevent financial surprises. For example, setting aside a small amount monthly for birth control ensures that this essential expense doesn’t become a burden when due.
Emergency Fund for Unexpected Situations
An emergency fund is a cornerstone of sound personal finance, designed to cover 3-6 months of living expenses for unexpected events. While often thought of for job loss or medical emergencies, an emergency fund also serves as a critical buffer for contraception-related mishaps. The immediate costs of emergency contraception, medical consultations, or pregnancy tests can be absorbed by an emergency fund without derailing other financial plans or forcing individuals into debt. Moreover, if an unplanned pregnancy does occur, this fund can provide initial financial stability during a highly stressful period, covering immediate needs while longer-term financial plans are adjusted. Neglecting to build or maintain an adequate emergency fund leaves one financially vulnerable to the unpredictable nature of life, including the consequences of a missed pill.
Understanding Insurance Coverage for Reproductive Health
It is critical for individuals to thoroughly understand their health insurance coverage regarding reproductive health. The Affordable Care Act (ACA) mandates that most insurance plans cover preventative services, including most forms of birth control, without co-pay. However, this coverage can vary based on the specific plan, state regulations, and type of birth control chosen (e.g., brand-name vs. generic). Understanding deductibles, co-pays for doctor visits, and specific coverage for emergency contraception or diagnostic tests (like pregnancy tests) is paramount. Proactively reviewing one’s insurance policy, or contacting the provider, can prevent unexpected bills and ensure access to necessary care without financial stress. This knowledge empowers individuals to make financially informed decisions about their contraceptive choices and subsequent actions if a pill is missed.
Financial Planning for Family Goals
Whether the goal is to remain child-free, delay childbearing, or plan for a family in the future, these intentions should be integrated into comprehensive financial planning. If remaining child-free is a priority, then consistent, effective contraception is a financial imperative to avoid the immense costs of an unplanned child. If delaying children, budgeting for robust, long-term birth control methods and having a financial safety net for potential contraceptive failures is wise. For those planning a family, financial planning should involve saving for future childcare, education, and increased household expenses. This foresight allows for gradual accumulation of funds, rather than being caught off guard by the financial demands of an unplanned arrival. Financial planning for family goals, or the absence thereof, provides a clear roadmap and helps align financial decisions with life aspirations.
Mitigating Financial Risks: Smart Practices and Resources
While no plan is foolproof, there are smart practices and resources available that can significantly mitigate the financial risks associated with birth control use, particularly the consequences of missing a pill. These strategies emphasize proactive management, informed decision-making, and leveraging available support systems.
Setting Up Reminders and Routine Habits
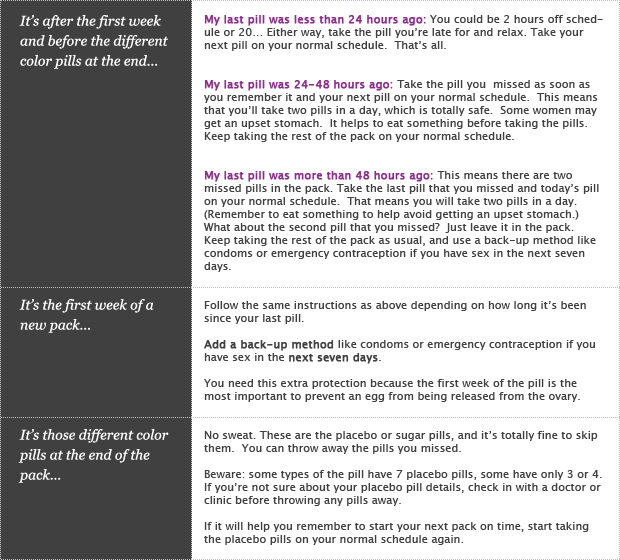
The simplest and most cost-effective way to avoid the financial repercussions of a missed pill is to prevent it from happening in the first place. This involves establishing consistent habits and utilizing readily available tools. Setting daily alarms on a smartphone, using dedicated birth control reminder apps, or integrating pill-taking into a daily routine (e.g., brushing teeth, before bed) can drastically reduce the likelihood of forgetting. These preventative measures cost nothing but save potentially hundreds or even hundreds of thousands of dollars in the long run. The financial discipline applied to budgeting and investing should extend to daily habits that protect financial well-being by preventing costly medical or life-altering events.
Consulting Financial and Healthcare Professionals
Navigating the intersection of reproductive health and personal finance can be complex. Consulting both healthcare and financial professionals is a prudent step. A healthcare provider can offer tailored advice on the most effective and appropriate birth control methods, considering personal health, lifestyle, and often, insurance coverage. They can also provide guidance on what to do if a pill is missed, potentially saving money by avoiding unnecessary EC or tests. Concurrently, a financial advisor can help integrate reproductive health costs into a broader financial plan, optimize savings strategies, and prepare for various life stages, including potential family changes. These professionals offer expert guidance that can lead to more informed decisions, cost-savings, and greater financial peace of mind.
Exploring Affordable Healthcare Options and Subsidies
Access to affordable healthcare is a significant factor in managing the financial risks of birth control. Individuals should explore all available options. Government programs like Medicaid or Title X family planning clinics often provide free or low-cost birth control, emergency contraception, and related medical services to eligible individuals, regardless of insurance status. Many pharmaceutical companies offer patient assistance programs for specific medications. Websites like GoodRx can provide coupons for prescription medications, including birth control and EC, often reducing costs significantly. Understanding and utilizing these resources can dramatically lower out-of-pocket expenses for contraception and related care, thereby protecting personal finances from the immediate and long-term costs associated with birth control use and potential failures.
In conclusion, while the immediate concern of missing a birth control pill often focuses on health, the financial implications are profound and far-reaching. From the immediate costs of emergency contraception and medical consultations to the life-altering expenses of an unplanned pregnancy, the financial stakes are exceptionally high. By adopting a proactive approach to financial planning, understanding insurance coverage, establishing robust preventative habits, and leveraging available resources, individuals can significantly mitigate these financial risks. Integrating reproductive health decisions into a comprehensive financial strategy is not merely advisable; it is an indispensable component of responsible personal finance, ensuring greater stability and control over one’s economic future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.