
The rise and fall of Fisker Inc. (formerly traded under the ticker FSR) serves as a definitive case study in the volatility of the electric vehicle (EV) sector and the inherent risks of Special Purpose Acquisition Company (SPAC) investments. Once hailed as a formidable challenger to Tesla, Fisker’s stock has plummeted from its peak valuations to essentially zero, leaving retail and institutional investors alike grappling with significant losses. Understanding what happened to Fisker stock requires a deep dive into corporate mismanagement, the breakdown of the “asset-light” business model, and the harsh realities of capital-intensive manufacturing in a high-interest-rate environment.

The Rise and Rapid Fall of a SPAC Darling
In the late 2010s and early 2020s, the financial markets were flooded with liquidity, and investor appetite for green energy was at an all-time high. Fisker Inc. took advantage of this environment by going public in October 2020 via a merger with Spartan Energy Acquisition Corp., a SPAC backed by private equity giant Apollo Global Management.
The Allure of the Asset-Light Model
What differentiated Fisker from other EV startups like Rivian or Lucid was its “asset-light” strategy. Rather than spending billions of dollars to build its own factories—a process Elon Musk famously described as “production hell”—Fisker outsourced the assembly of its flagship vehicle, the Ocean SUV, to Magna Steyr in Austria. On paper, this was a brilliant financial move. It promised to reduce capital expenditures, accelerate time-to-market, and allow the company to focus on design and software. Investors initially cheered this strategy, pushing the stock to highs near $30 per share shortly after its debut.
From Public Offering to Peak Valuation
At its height, Fisker commanded a multi-billion dollar market capitalization despite having delivered zero vehicles. This “valuation on hope” was driven by the pedigree of its founder, Henrik Fisker—a world-renowned car designer—and a massive backlog of reservations. However, the transition from a design concept to a revenue-generating entity proved to be the company’s undoing. As the macroeconomic environment shifted and interest rates began to rise, the “free money” era ended, and the market began demanding profitability over promises.
Financial Red Flags and the Liquidity Crisis
The decline of Fisker stock was not a sudden event but a slow-motion wreck fueled by a series of quarterly earnings misses and alarming financial disclosures. By 2023, the cracks in the asset-light model were impossible to ignore.
Negative Gross Margins and Cash Burn
For a manufacturing company to survive, it eventually needs to sell its products for more than they cost to produce. Fisker struggled with negative gross margins, meaning every car that rolled off the assembly line actually depleted the company’s cash reserves rather than replenishing them. Throughout 2023, the company’s cash burn reached unsustainable levels. Efforts to scale production were met with logistical nightmares, and the cost of shipping vehicles from Europe to the United States ate into any potential profits.
Regulatory Hurdles and Technical Glitches
Investor confidence was further eroded by a series of technical failures and regulatory investigations. The Fisker Ocean was plagued by software bugs, including issues with the braking system and key fobs that left owners stranded. These weren’t just “early adopter” hiccups; they were fundamental flaws that triggered investigations by the National Highway Traffic Safety Administration (NHTSA). For investors, these reports were a signal to exit. The stock began a precipitous decline as the company was forced to issue multiple recalls, further draining its dwindling cash pile.
The Final Blow: Delisting and Chapter 11 Bankruptcy
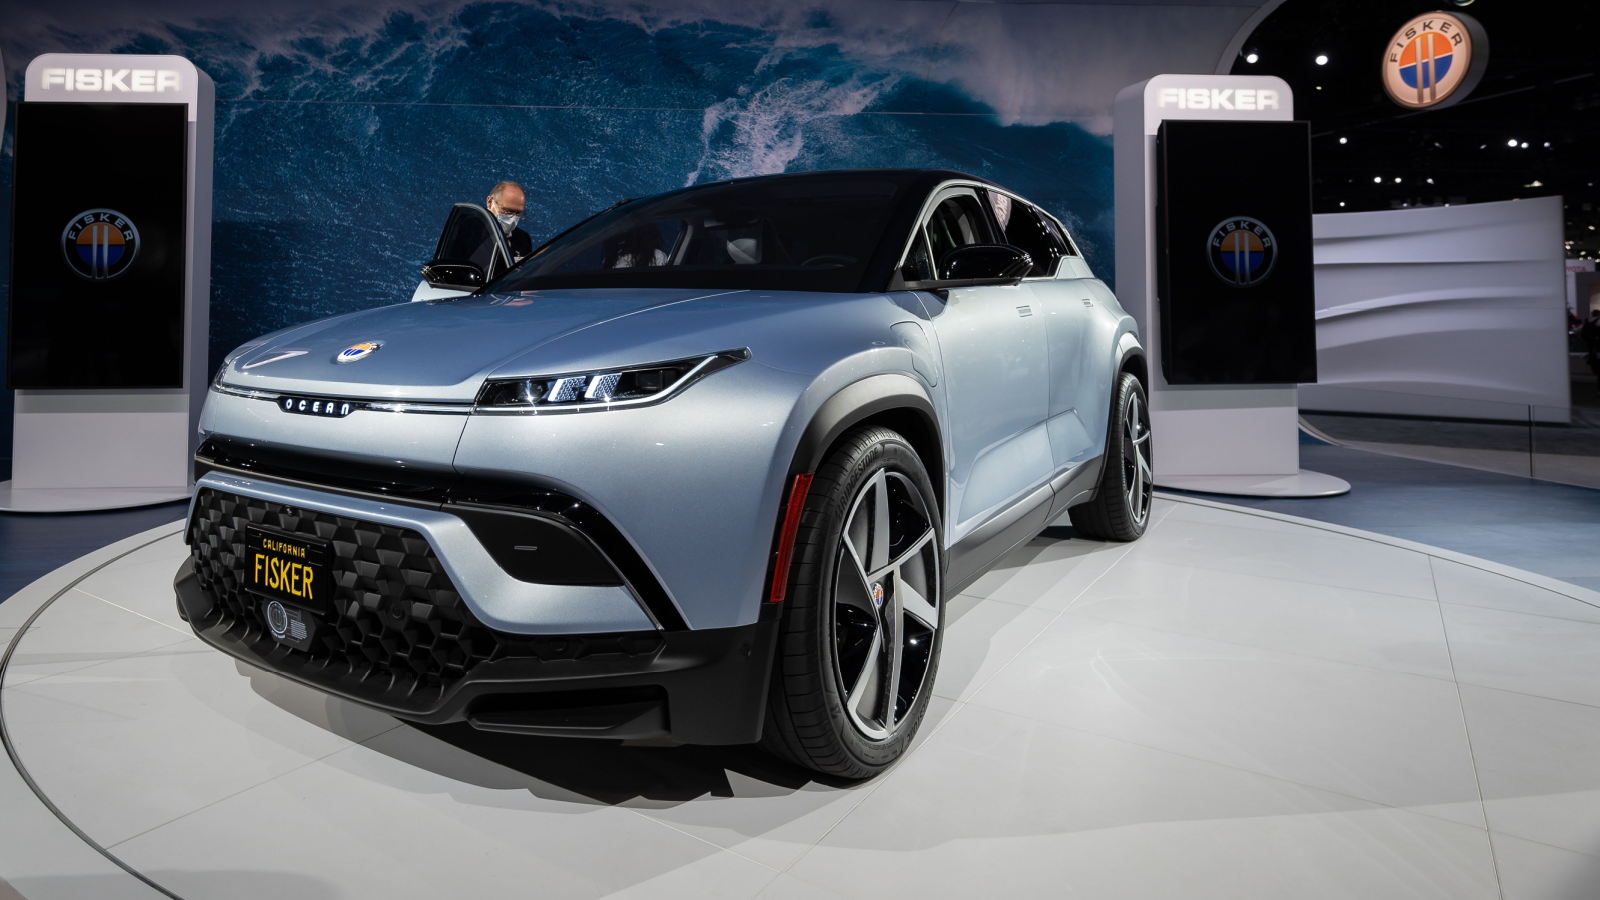
The death knell for Fisker stock came in early 2024. As the company’s share price dropped below the $1.00 threshold required by the New York Stock Exchange (NYSE), the threat of delisting became a reality.
The NYSE Exit and OTC Transition
In March 2024, the NYSE commenced proceedings to delist Fisker Inc. after the stock failed to maintain a minimum trading price and the company announced it could not secure a vital investment from a large automaker (rumored to be Nissan). When a stock is delisted from a major exchange and moved to the Over-the-Counter (OTC) markets (where it traded under the symbol FSRN), liquidity vanishes. Institutional investors, many of whom are barred from holding OTC stocks, were forced to sell their positions at any price, leading to a total collapse in value.
What Chapter 11 Means for Retail Investors
In June 2024, Fisker Group Inc. filed for Chapter 11 bankruptcy protection. In the hierarchy of corporate finance, common shareholders are at the bottom of the “absolute priority rule.” This means that in a bankruptcy restructuring or liquidation, secured creditors, bondholders, and even preferred shareholders are paid first. For Fisker stockholders, the bankruptcy filing essentially signaled that their equity was worthless. The company’s remaining assets—primarily its fleet of unsold SUVs and its intellectual property—are being liquidated to pay off a fraction of its $1 billion+ debt.
Lessons for the Modern Investor
The Fisker saga provides several critical takeaways for those navigating the modern stock market, particularly in the speculative growth and EV sectors.
The Dangers of Pre-Revenue Speculation
Fisker’s initial valuation was based entirely on projected earnings and reservations, not actual sales. Investors who bought into the hype failed to account for the “execution risk”—the difficulty of moving from a prototype to mass production. The lesson here is the importance of fundamental analysis. While it is tempting to chase the “next Tesla,” investors must scrutinize the balance sheet. A company with high debt and no path to positive cash flow is a gamble, not an investment.
Understanding Capital Structure in Distressed Scenarios
Many retail investors held onto Fisker stock as it fell to $0.10, hoping for a “meme stock” rally or a white-knight acquisition. However, understanding the capital structure would have revealed how unlikely a recovery was. When a company is burdened with senior secured debt, even an acquisition often results in the common equity being wiped out to satisfy the lenders. Recognizing the point of “no return” in a company’s financial health is vital for capital preservation.
The SPAC Warning Label
Fisker was part of the 2020-2021 SPAC boom, a period characterized by laxer regulatory oversight compared to traditional IPOs. Companies were allowed to make forward-looking statements that often proved to be wildly optimistic. The failure of Fisker, along with other SPACs like Lordstown Motors and Canoo, highlights the need for extreme caution when investing in companies that bypass the traditional IPO vetting process.

The Future of Fisker and the Market Verdict
As of late 2024, the remains of Fisker Inc. are being dismantled. A recent court-approved deal allowed a fleet leasing company to purchase thousands of remaining Fisker Oceans at a massive discount—pennies on the dollar compared to their original MSRP. This fire sale is a grim metaphor for the stock itself.
The story of Fisker is a reminder that in the world of business finance, design and vision are secondary to liquidity and operational efficiency. Henrik Fisker may be a legendary designer, but Fisker Inc. was a financial house of cards built on the assumption that capital would always be cheap and plentiful. When the market shifted, the “asset-light” model revealed its greatest flaw: without assets to leverage or cash to spend, the company had no floor to catch its fall.
For the investing community, Fisker’s ticker symbol will remain a permanent entry in the ledger of “cautionary tales.” It serves as a stark reminder that even in the most exciting and futuristic industries, the old rules of money—cash flow, debt management, and sustainable margins—eventually always win. For those who held Fisker stock to the end, the cost was the total loss of principal, a high price to pay for a lesson in the mechanics of market cycles and corporate insolvency.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.