
Understanding the clinical terminology on your laboratory reports is not merely a health endeavor; it is an essential component of personal asset management. In the same way that a savvy investor reviews a quarterly balance sheet to gauge the long-term viability of a portfolio, an individual must learn to interpret biomarkers like Mean Corpuscular Volume (MCV) to assess the “human capital” that sustains their ability to earn, save, and invest. When we talk about healthcare in the context of personal finance, we are essentially discussing the preservation of one’s primary income-generating asset: the self.
The Financial Impact of Health Biomarkers
At its core, MCV stands for Mean Corpuscular Volume. It is a measurement of the average size of your red blood cells. In a Complete Blood Count (CBC) panel, this metric serves as a diagnostic indicator of how efficiently your body is transporting oxygen throughout your system. From a financial perspective, health is the prerequisite for all wealth-building activities. Chronic fatigue, cognitive fog, or long-term illness resulting from undiagnosed anemias—often flagged by abnormal MCV levels—can act as “silent liabilities” that erode your productivity, limit your capacity for high-intensity work, and necessitate unplanned, out-of-pocket medical expenditures.
The Opportunity Cost of Neglect
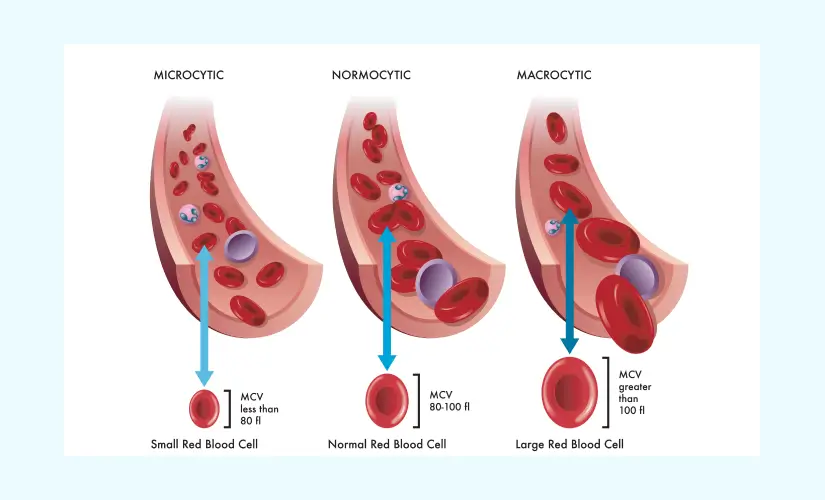
Neglecting routine blood work is akin to ignoring a deteriorating piece of machinery in a factory; it leads to increased maintenance costs down the line. When MCV levels fall outside the standard reference range (typically 80 to 100 femtoliters), it is a signal that your “operating costs”—the nutritional resources your body requires—are not being utilized effectively. By proactively understanding what these lab results mean, you transition from a reactive model of healthcare, which is notoriously expensive, to a preventative model, which protects your bottom line by catching issues before they escalate into high-cost medical events.
Interpreting MCV: Analyzing Your Biological Assets
When a blood test report reveals an MCV value, it is categorizing your red blood cells into one of three distinct classes: microcytic (small), normocytic (normal), or macrocytic (large). Much like classifying investment assets into high-risk, moderate-risk, or low-risk categories, each classification requires a different strategic response.
Microcytic MCV: The Deficit Scenario
A low MCV (below 80 fL) often indicates microcytic anemia, frequently caused by iron deficiency. In personal finance, this is analogous to a liquidity crisis. Your body lacks the “working capital” (iron) necessary to produce healthy, appropriately sized red blood cells. If left unaddressed, this deficiency can lead to reduced stamina and cognitive output, directly impacting your ability to maintain focus on complex financial tasks, career advancement, or side hustles. Addressing the underlying deficiency through diet or supplementation is a high-yield investment in your personal output.
Macrocytic MCV: The Inflation Scenario
Conversely, a high MCV (above 100 fL) suggests macrocytic cells, which are often larger than normal. This is frequently linked to deficiencies in Vitamin B12 or folate. Think of this as “biological inflation”—your cells are bloated because the DNA synthesis process required for proper cell division is failing to keep up. This can result in neurological symptoms or fatigue that significantly diminishes your “earning hours.” Managing this requires a shift in resource allocation, ensuring that your nutritional intake provides the “capital” necessary for cellular health.

Healthcare as a Long-Term Financial Strategy
Integrating medical awareness into your broader financial plan is a hallmark of sophisticated personal finance management. Many individuals meticulously track their credit scores, investment returns, and tax liabilities while remaining completely oblivious to the biomarkers that indicate their long-term health sustainability.
Risk Mitigation and Insurance Premiums
Your health metrics directly impact your financial profile. From a life and disability insurance standpoint, your lab results, including CBC markers like MCV, can influence your premiums. By maintaining a clean bill of health and addressing minor imbalances before they manifest as chronic conditions, you are essentially engaging in a form of risk mitigation. Insurance companies analyze these metrics to determine your risk profile; keeping your biological metrics within optimal ranges can be a silent factor in qualifying for “preferred” underwriting tiers, which save you thousands of dollars over the lifetime of a policy.
Budgeting for Preventive Diagnostics
While insurance often covers basic diagnostic tests, the out-of-pocket costs for advanced blood panels or follow-up consultations can be significant. Incorporating a “Health Maintenance Fund” into your monthly budget allows you to view these expenses not as losses, but as strategic investments in your primary income-generating machine. If your MCV is out of range, the cost of a specialist visit or high-quality supplements should be viewed through the lens of protecting your ability to generate long-term wealth.
The Compound Interest of Proactive Health
The concept of compound interest is the bedrock of wealth creation; it suggests that small, consistent actions lead to exponential growth over time. The same principle applies to your biology. Consistent tracking of your MCV levels provides a longitudinal data set. If you see a trend moving toward the edges of the reference range over several years, you have the opportunity to intervene early.
Data-Driven Decision Making
The modern digital landscape provides individuals with an unprecedented level of access to their own health data. Using health tracking apps, digital patient portals, and wearable technology, you can correlate your MCV readings with other lifestyle data points, such as sleep quality, exercise volume, and dietary habits. By applying a data-driven approach to your health, you remove the guesswork. You are no longer “hoping” to be healthy; you are managing your biological resources with the same rigor you apply to your investment portfolio.

Avoiding the Cost of “Systemic Failure”
If ignored, blood-related issues can lead to systemic failures that are incredibly costly. Chronic, untreated anemia can exacerbate other health conditions, leading to frequent sick days, diminished cognitive clarity during critical decision-making moments, and eventually, the potential for long-term disability. By understanding what MCV means, you are performing a “stress test” on your body. You are identifying potential weaknesses in your biological infrastructure, allowing you to rebalance your internal “portfolio” to ensure you remain high-performing, resilient, and capable of pursuing your financial objectives well into the future.
In summary, the next time you glance at your blood test results, do not see them merely as a list of cryptic clinical numbers. View them as the quarterly earnings report of your most valuable asset. The MCV reading is a critical indicator of your internal efficiency. By treating your health with the same professional, insightful, and strategic rigor as your financial investments, you secure the most important foundation for every other goal you aim to achieve. Wealth, after all, is meaningless if you lack the vitality to steward it.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.