
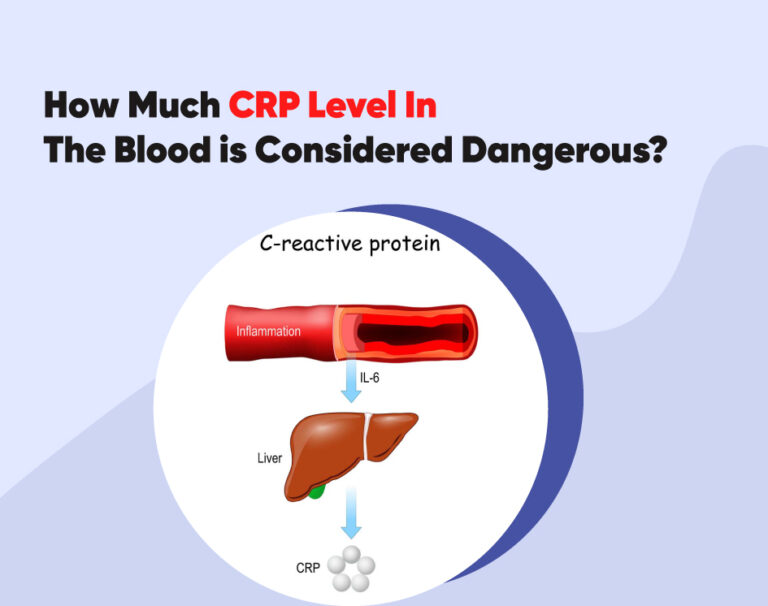
In the world of personal finance and corporate wealth management, metaphors often provide the clearest path to understanding complex systems. Just as a medical practitioner uses a C-Reactive Protein (CRP) test to measure inflammation and assess the internal health of a patient, a seasoned financial advisor uses a Capital Risk Profile (CRP) to diagnose the underlying health of an investment portfolio or a business’s balance sheet.
In a fiscal context, “CRP” is the ultimate diagnostic tool. It is the metaphorical blood test that reveals whether your capital is working efficiently or if there is “inflammation”—in the form of excessive debt, market volatility, or illiquidity—threatening your long-term financial survival. Understanding your CRP is not just about looking at a single number; it is about interpreting the vital signs of your wealth to ensure sustainable growth and resilience against economic shocks.
Decoding CRP: What Does Your Capital Risk Profile Actually Mean?
At its core, the Capital Risk Profile (CRP) is a comprehensive assessment of the riskiness of an individual’s or an entity’s capital structure. In the same way a medical blood test looks for markers of disease, the CRP looks for markers of financial instability. When we ask, “What does CRP mean in a blood test of your finances?” we are looking for the balance between equity, debt, and liquid reserves.
The Components of a Financial Health Check
A robust CRP analysis involves looking at three primary “vessels” of wealth: liquidity, leverage, and asset volatility. Liquidity represents the “blood flow” of your finances—the ease with which assets can be converted to cash to meet immediate needs. Leverage, or debt, acts like blood pressure; a certain amount is necessary for growth, but excessive levels can lead to a systemic collapse. Finally, volatility measures the heart rate of your investments—how much they fluctuate in response to market stress.
By quantifying these factors, financial analysts can assign a CRP score. A “high CRP” in finance suggests that your capital is exposed to high levels of risk, perhaps due to over-leveraging in a high-interest-rate environment or holding too many speculative assets. Conversely, a “low CRP” suggests a conservative, perhaps even stagnant, financial position that may lack the “nutrients” of growth needed to outpace inflation.
High vs. Low CRP: Assessing Your Portfolio’s Sensitivity
The interpretation of your CRP depends heavily on your stage of life or the stage of your business cycle. For a young investor, a higher CRP might be acceptable—much like a high heart rate during intense exercise—because they have the time to recover from market “inflammation.” However, for someone nearing retirement, a high CRP is a red flag, indicating that a single market downturn could cause irreparable damage to their nest egg.
For businesses, the CRP measures the sensitivity of the company’s valuation to external shocks. A company with high CRP has little margin for error; if supply chains break or consumer demand shifts, the financial “inflammation” can quickly turn into a full-scale crisis. Understanding this metric allows leaders to pivot before the damage becomes systemic.
Why CRP is the Vital Metric for Long-Term Wealth Management
In the modern financial landscape, simply tracking “Net Worth” is no longer sufficient. Net worth is a vanity metric; it tells you how much you have, but it doesn’t tell you how healthy those assets are. This is where the Capital Risk Profile becomes indispensable. It serves as a preventative measure, identifying problems before they manifest as losses on a quarterly statement.
Identifying Hidden Inflations in Business Costs
In corporate finance, CRP helps identify “hidden inflammation”—costs that are rising faster than revenue or inefficiencies that are draining capital. For example, a business might show healthy profits, but a deep dive into its CRP might reveal that those profits are being propped up by short-term debt with floating interest rates.
When interest rates rise, that hidden inflammation flares up. The CRP diagnostic allows management to see these vulnerabilities early. By monitoring the “blood test” of the balance sheet, CFOs can restructure debt or divest from underperforming assets before a liquidity crunch occurs. This proactive approach to capital management is what separates enduring brands from those that fail during economic contractions.
The Correlation Between Risk Tolerance and Asset Allocation
Every investor has a theoretical risk tolerance, but few have a quantified one. The CRP bridges the gap between how an investor thinks they feel about risk and how their portfolio will actually behave.
If your “financial blood test” shows a CRP that is out of alignment with your goals, it indicates a mismatch in asset allocation. For instance, an investor seeking “safe” income who is heavily invested in high-yield “junk” bonds may have a dangerously high CRP without realizing it. The CRP provides the empirical evidence needed to rebalance the portfolio, ensuring that the risk taken is proportional to the expected reward.
How to Run Your Own Financial CRP Test
Performing a CRP analysis does not require a laboratory, but it does require a disciplined look at your financial data. To understand what your CRP means, you must look beyond the surface level of your bank account balance and analyze the structural integrity of your wealth.
Analyzing Liquidity and Debt-to-Equity Ratios
The first step in a financial CRP test is calculating your “Liquidity Ratio.” This is your cash and cash equivalents divided by your monthly liabilities. If this number is too low, your financial system is “anemic”—you lack the circulation needed to survive a sudden loss of income.
The second marker is the Debt-to-Equity ratio. In the financial blood test, debt is a foreign agent. While some debt can be “probiotic” (helping you grow through low-interest mortgages or business loans), “pathogenic” debt (high-interest credit cards or predatory loans) increases your CRP score significantly. A high debt-to-equity ratio suggests that your “body” of wealth is supported more by borrowed strength than by actual muscle, making you vulnerable to “infections” in the credit markets.
Stress-Testing Your Portfolio Against Market Volatility
A true CRP diagnostic includes a “stress test.” This involves simulating how your assets would perform under various negative scenarios, such as a 20% market correction, a 5% spike in interest rates, or a period of hyper-inflation.
If a 20% drop in the stock market would leave you unable to meet your financial obligations, your CRP is critically high. By running these simulations, you can identify which assets are the “weak cells” in your portfolio. This allows you to cut out the “malignant” investments that provide high risk with low utility, replacing them with assets that offer better “immunity” against market fluctuations.
Optimizing Your CRP for Sustainable Growth
Once you have diagnosed your CRP, the next step is treatment. Just as a doctor might prescribe a change in diet or medication to lower biological CRP, a financial advisor prescribes specific maneuvers to lower a Capital Risk Profile. The goal is not to eliminate risk entirely—after all, a “zero-risk” portfolio usually fails to grow—but to optimize it.
Rebalancing Strategies to Lower Financial “Inflammation”
Rebalancing is the most effective “anti-inflammatory” for a bloated CRP. Over time, certain assets—usually equities—grow faster than others, causing them to take up a larger percentage of your portfolio than originally intended. This “overgrowth” increases your CRP because you are now more exposed to a specific sector or asset class.
By systematically selling a portion of your winners and reinvesting in underrepresented areas (like bonds, real estate, or international markets), you bring your CRP back to a healthy level. This “cleanse” ensures that no single market event can take down your entire financial system. It is a process of harvesting gains to protect the core health of your capital.
Leveraging Technology for Real-Time Risk Monitoring
In the past, a financial “blood test” was something you did once a year with an accountant. Today, technology allows for real-time CRP monitoring. AI-driven financial tools can now track your Capital Risk Profile daily, sending alerts when your leverage ratios or volatility markers exceed safe thresholds.
These apps and software act like a wearable heart rate monitor for your money. They provide immediate feedback on how a new investment or a large purchase will affect your overall CRP. By leveraging these tech tools, individuals and businesses can maintain “peak fitness,” making small adjustments to their financial habits rather than waiting for a major crisis to force a drastic intervention.
Conclusion: The Importance of Regular Financial Diagnostics
In the final analysis, what does CRP mean in a blood test of your finances? It means the difference between a portfolio that is fragile and one that is antifragile. It is a measure of your preparedness for the unknown and your resilience in the face of the inevitable.
Ignoring your Capital Risk Profile is equivalent to ignoring a persistent fever; the symptoms may be manageable now, but the underlying inflammation will eventually lead to a breakdown. By treating your finances with the same scientific rigor as your health, you ensure that your wealth remains robust, energetic, and capable of supporting your goals for decades to come. Regular CRP checks are not just a good habit—they are the foundation of modern financial mastery. Whether you are managing a personal household budget or a multi-million dollar corporate fund, your “CRP score” is the most honest reflection of your true financial health. Keep it balanced, keep it monitored, and your wealth will thrive.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.