
In the complex landscape of modern commerce, the acronym COI serves as a critical signpost for financial health, ethical governance, and strategic decision-making. Depending on the context—be it corporate governance, risk management, or investment strategy—COI primarily stands for three distinct but equally vital concepts: Conflict of Interest, Certificate of Insurance, and Cost of Inaction.
For the business owner, financial officer, or individual investor, understanding these three definitions is not merely an exercise in vocabulary; it is a fundamental requirement for protecting capital and maximizing returns. Each interpretation of COI carries significant weight in how money flows within and out of an organization. This guide provides an in-depth exploration of these definitions through the lens of business finance and risk mitigation.

Conflict of Interest: Navigating the Ethics of Business Finance
In the realm of corporate governance and personal finance, a Conflict of Interest (COI) occurs when an individual’s private interests interfere—or even appear to interfere—with the interests of the company or its stakeholders. From a financial perspective, a COI is a major red flag that can lead to fraud, embezzlement, and a catastrophic loss of investor confidence.
Fiduciary Duty and Financial Integrity
At the heart of the COI definition is the concept of fiduciary duty. Financial advisors, board members, and corporate executives are legally and ethically bound to act in the best financial interest of their clients or shareholders. When a COI arises—such as an executive awarding a lucrative contract to a firm owned by a family member—the fiduciary duty is breached.
The financial fallout of such breaches is often severe. When conflicts are discovered, the resulting loss of trust can lead to a sharp decline in stock prices, the withdrawal of venture capital, and expensive legal battles. In business finance, maintaining an “arm’s length” relationship in all transactions is the standard practice used to prevent these conflicts and ensure that capital is allocated based on merit and market value rather than personal gain.
Identifying and Mitigating Financial COIs
To protect the financial integrity of an organization, robust disclosure policies are essential. Many firms require annual COI disclosures where employees must list any outside financial interests that could overlap with their professional duties.
Mitigation strategies often include:
- Recusal: Removing the conflicted individual from the decision-making process.
- Blind Trusts: For high-level executives, placing personal investments in a trust managed by an independent party to prevent insider trading or biased policy-making.
- Independent Audits: Utilizing third-party financial auditors to ensure that all transactions are transparent and justifiable.
By treating COI management as a core component of financial risk management, businesses can prevent the siphoning of resources and maintain a competitive, ethical marketplace.
Certificate of Insurance: Protecting Capital and Managing Liability
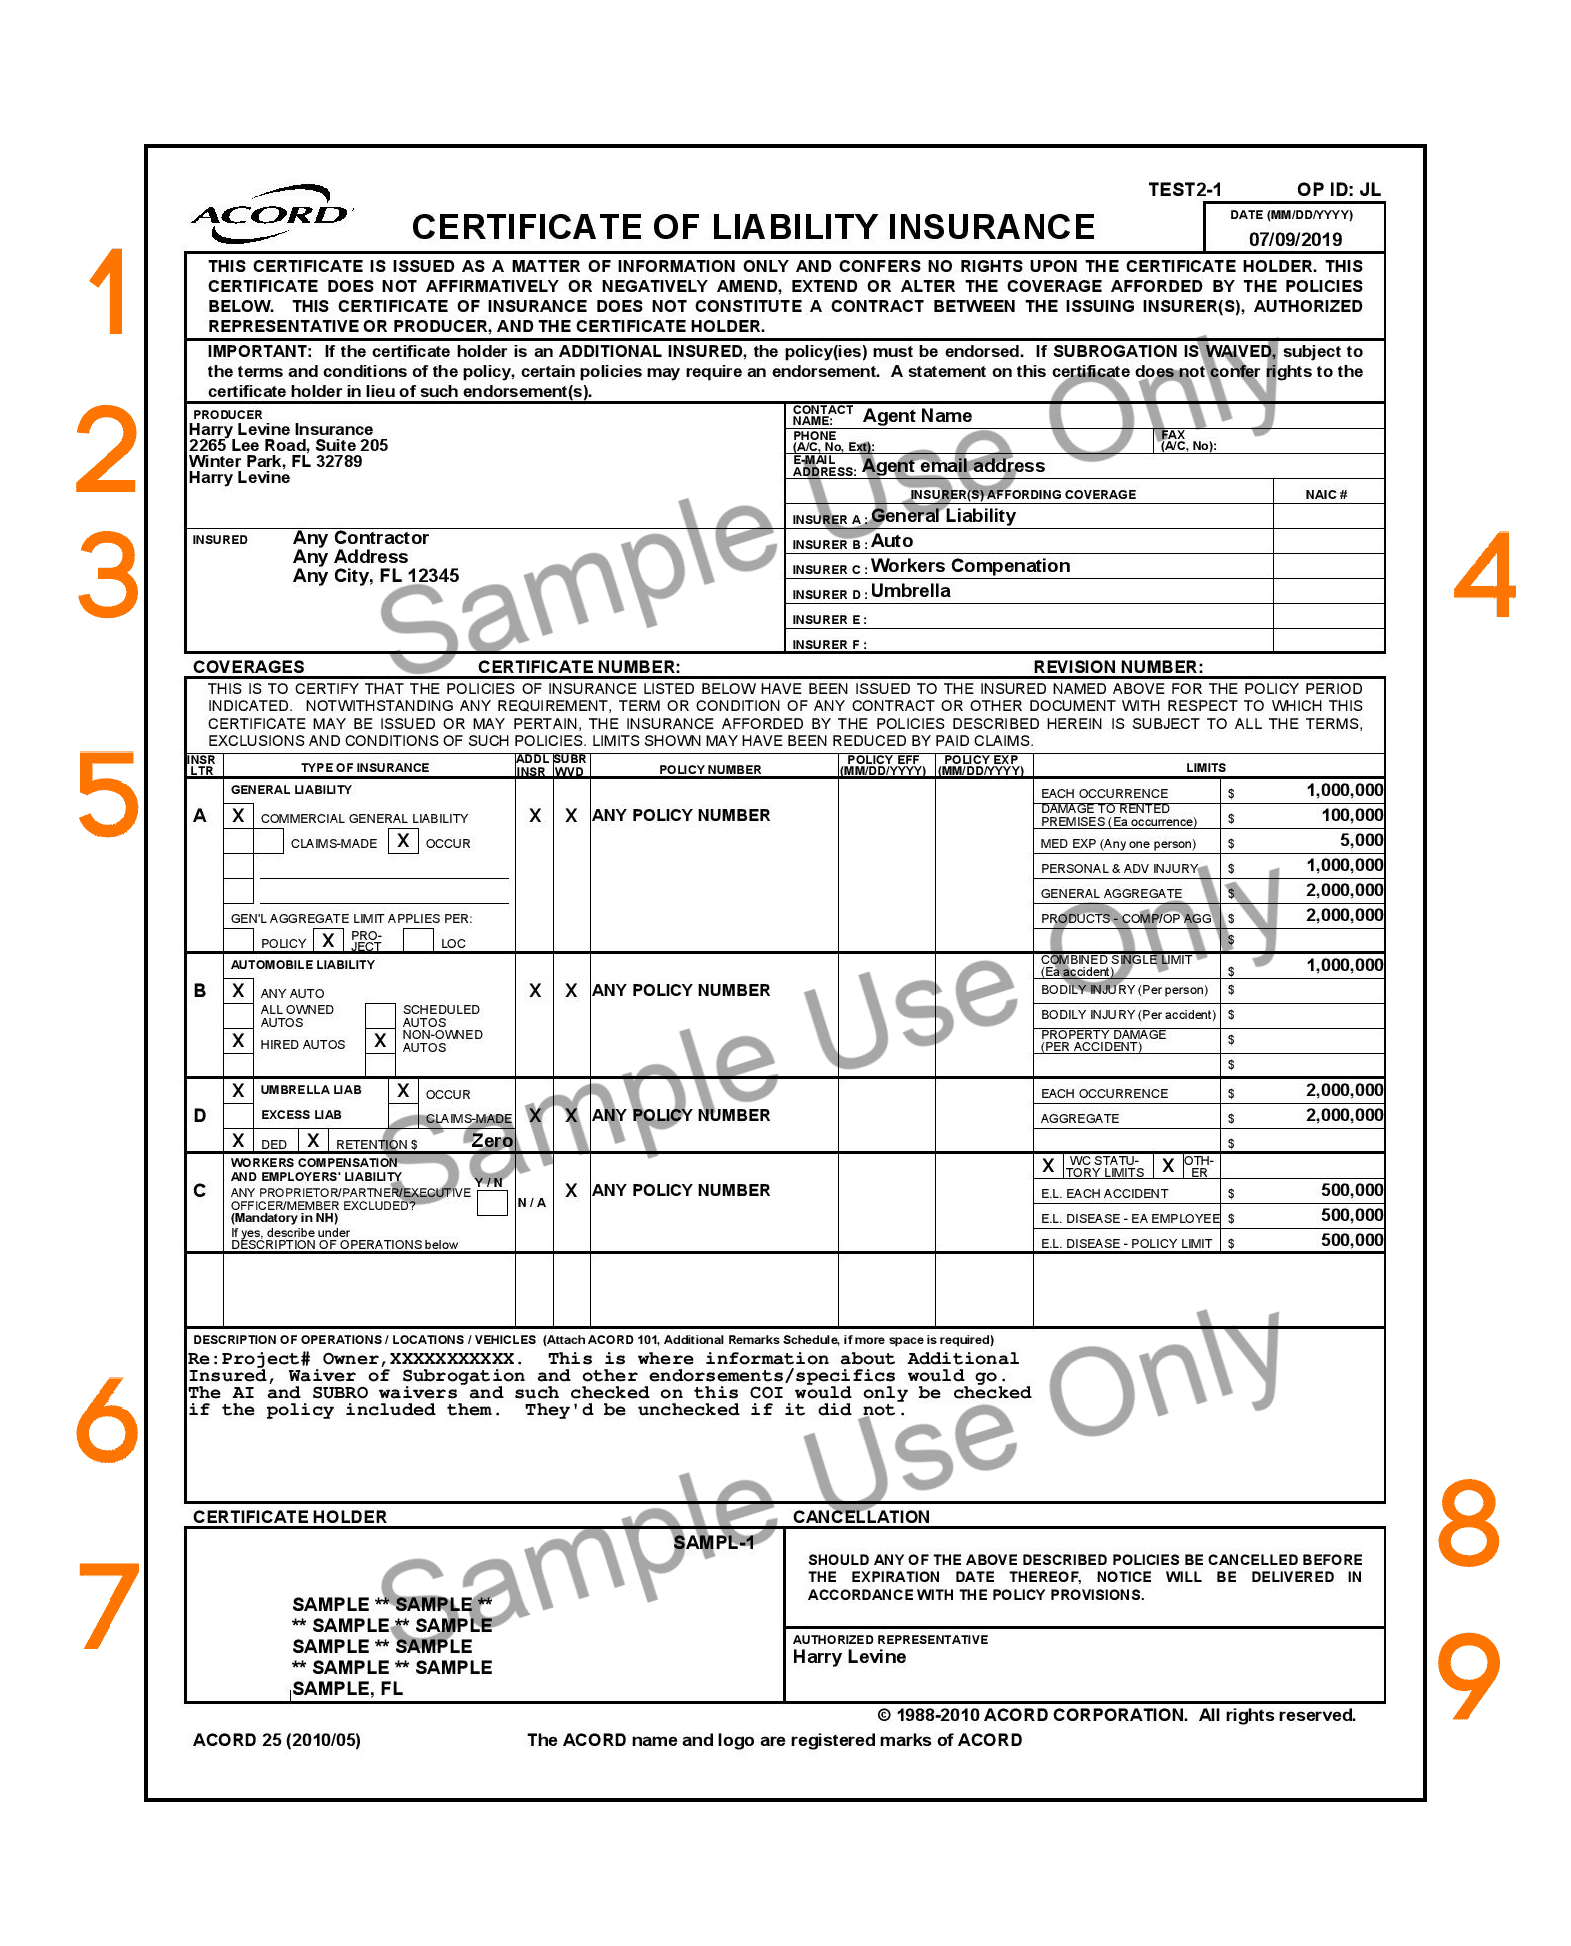
For business owners and risk managers, COI most frequently stands for Certificate of Insurance. This document is a summary of an insurance policy that provides “proof” of coverage. While it may seem like a simple piece of paper, it is a cornerstone of business finance, specifically regarding risk transfer and the protection of a company’s balance sheet.
Why COIs are Essential for Business Solvency
Every business operation carries inherent risks—property damage, professional errors, or personal injury. Without insurance, a single lawsuit or disaster could lead to insolvency. A COI is the mechanism by which a business proves to its partners, landlords, or clients that it has the financial backing to handle these liabilities.
In high-stakes industries like construction, logistics, or professional consulting, the exchange of COIs is a mandatory precursor to any financial transaction. If a subcontractor causes $1 million in damages, the general contractor needs to know that the subcontractor’s insurance company—not the contractor’s own cash reserves—will cover the cost. Therefore, the COI is a vital document in protecting the liquidity and long-term financial health of an enterprise.
Verification and Auditing Processes
Simply receiving a COI is not enough. Sophisticated financial operations implement rigorous verification processes to ensure the certificates are valid and the coverage limits are sufficient.
Key elements to verify on a COI include:
- Policy Limits: Ensuring the coverage amounts (e.g., General Liability, Workers’ Comp) meet the minimum requirements of the contract.
- Expiration Dates: Monitoring when policies lapse to ensure there is no gap in financial protection.
- Additional Insured Status: Confirming that the hiring party is listed as an “additional insured,” which grants them direct protection under the policy.
Failure to properly track these documents can result in “uninsured risk,” a state where a company is unknowingly exposed to total financial loss. Many modern firms now use specialized software to automate the tracking of COIs, treating insurance compliance as a critical line item in their financial security strategy.
Cost of Inaction: The Hidden Financial Drain on Modern Enterprises
While Conflict of Interest and Certificate of Insurance are reactive and defensive, the third meaning of COI—Cost of Inaction—is a proactive financial metric. In investment and business strategy, the Cost of Inaction represents the financial penalty a company pays for failing to make a necessary change or investment.
Calculating the COI vs. ROI
Most financial departments are obsessed with Return on Investment (ROI). They ask, “If we spend $100,000 on this new software, what will we get back?” However, the more sophisticated question is, “If we do not spend this $100,000, what will we lose?” This is the calculation of the Cost of Inaction.
For example, if a business continues to use an outdated manual accounting system, the COI might include:
- Labor Costs: The salary of three extra employees needed to process paperwork manually.
- Error Costs: The financial impact of data entry mistakes that lead to overpayment or tax penalties.
- Opportunity Costs: The revenue lost because leadership lacks real-time financial data to make quick market moves.
When the COI exceeds the cost of a new investment, the “safe” choice of doing nothing becomes the most expensive option. In the context of online income and side hustles, the COI is often the lost compounded interest or market share that results from delaying a launch.
Strategic Allocation of Resources
Understanding the Cost of Inaction shifts the focus from “saving money” to “optimizing capital.” Financial leaders use COI to justify significant capital expenditures. By quantifying the losses associated with the status quo, they can build a compelling business case for digital transformation, market expansion, or talent acquisition.
In the world of personal finance and investing, the COI is frequently seen in the delay of retirement contributions. Waiting just five years to start investing can result in hundreds of thousands of dollars in lost gains over a lifetime—a staggering Cost of Inaction that highlights the time-value of money.
Integrating COI Management into a Robust Financial Strategy
Whether you are dealing with ethical conflicts, insurance verification, or the price of stagnation, managing the “three COIs” is essential for any financially sound business. Integrating these concepts into a unified strategy ensures that an organization is protected from internal fraud, external liability, and the slow decay of inefficiency.
Implementing Internal Controls
To address Conflicts of Interest and Certificates of Insurance, a business must implement strong internal controls. This involves:
- Segregation of Duties: Ensuring no single person has total control over financial transactions, which reduces the opportunity for COIs.
- Compliance Audits: Regularly reviewing the validity of insurance certificates for all vendors and partners.
- Transparency Protocols: Making all potential financial interests public within the organization to prevent “under-the-table” dealings.
These controls act as a shield, preserving the company’s capital and ensuring that every dollar spent is a legitimate business expense.
Leveraging Technology for Financial Compliance
In the digital age, manual tracking of COIs—whether they are ethical disclosures or insurance papers—is a financial liability in itself. Leading enterprises use fintech tools and compliance software to manage these risks.
Automated platforms can:
- Flag potential conflicts of interest by cross-referencing employee data with vendor lists.
- Automatically ping vendors when their Certificate of Insurance is about to expire, preventing a lapse in coverage.
- Provide data analytics that highlight the Cost of Inaction in various departments by tracking productivity declines or rising maintenance costs of old assets.
By leveraging technology, the “COI” becomes less of a burden and more of a strategic advantage. It allows financial officers to move from a defensive posture to a proactive one, where risks are identified before they become losses and opportunities are seized before they become costs.
Ultimately, “what COI stands for” depends on the specific financial challenge at hand. However, the common thread across all definitions is the protection and growth of capital. By mastering the nuances of Conflict of Interest, Certificate of Insurance, and Cost of Inaction, business leaders can navigate the complexities of the modern market with confidence, ensuring that their financial foundations remain unshakable.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.