
In the world of finance, grades are far more than academic benchmarks; they are the fundamental language of risk, trust, and capital allocation. When an investor or a financial institution asks, “What does C stand for in grades?” they are rarely inquiring about a classroom performance. Instead, they are navigating the complex landscape of creditworthiness, bond ratings, and financial stability. In the financial sector, a “C” grade represents a specific tier of high-risk, high-reward potential that dictates how trillions of dollars flow through global markets.
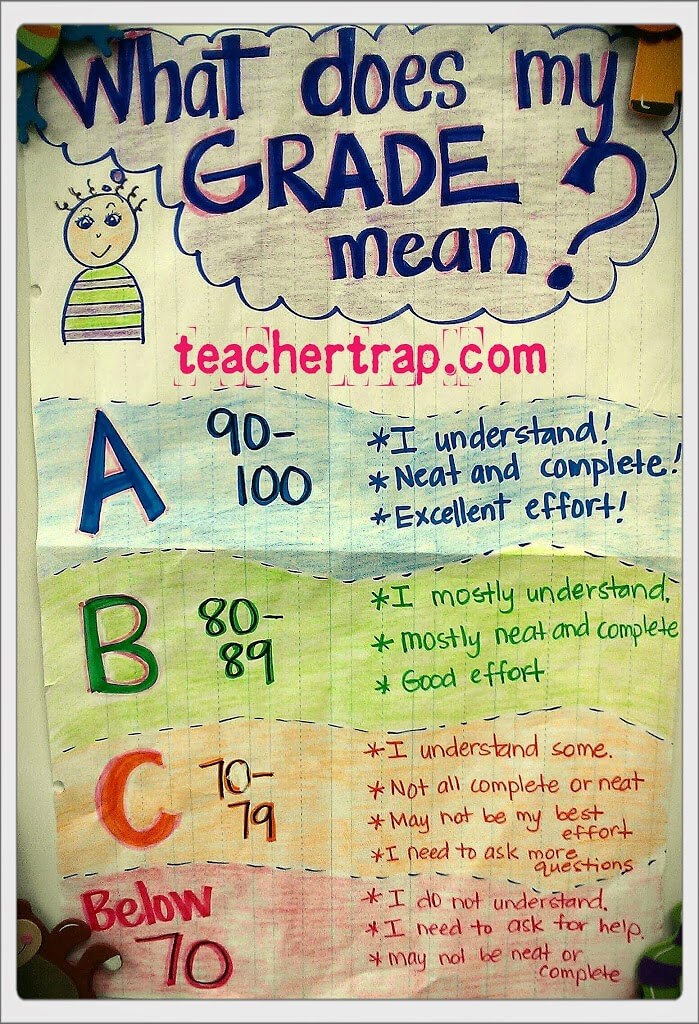
Understanding the “C” grade requires a shift in perspective from the educational “average” to the financial “vulnerable.” Whether applied to corporate bonds, sovereign debt, or individual credit scores, a C-tier rating serves as a critical indicator for lenders and investors. It marks the boundary between safety and speculation, often signaling that an entity is facing significant headwinds but may still offer unique opportunities for those with the right risk appetite.
The Financial Alphabet: Defining the “C” Grade in Global Markets
The grading systems used by major credit rating agencies—such as Standard & Poor’s (S&P), Moody’s, and Fitch—provide a standardized framework for assessing the likelihood that a borrower will fulfill their financial obligations. While an “A” grade signifies prime stability and “B” indicates a moderate degree of risk, the “C” grade is where the narrative shifts toward high speculation.
The Spectrum of Speculative Grades
In the nomenclature of S&P and Fitch, a “C” rating is often part of the “junk” or non-investment grade category. Specifically, a “C” grade usually denotes that the issuer is currently highly vulnerable to non-payment. Depending on the specific agency, the grade may be modified with plus or minus signs (C+, C-) or numbers (Ca1, Caa2) to provide more granular detail.
A “C” grade typically suggests that the entity has a high probability of default or is already in a state where default is imminent. For example, Moody’s defines a “C” rating as the lowest class of bonds, typically in default, with little prospect for recovery of principal or interest. This is a stark contrast to the academic “C,” which implies a passing, if unremarkable, effort. In finance, a “C” is a red flag, signaling that the borrower’s financial health is in a critical state.
The Role of Rating Agencies
The major agencies act as the “teachers” of the financial world, constantly grading the homework of corporations and governments. They analyze debt-to-equity ratios, cash flow projections, and macroeconomic conditions to assign these letters. When a rating drops to the “C” level, it triggers automatic responses in the market. Many institutional investors, such as pension funds, have mandates that prevent them from holding debt rated below a certain level. Consequently, a downgrade to “C” can lead to a mass sell-off, further depressing the value of the assets involved.
Corporate Credit and the High-Stakes World of Speculative Grading
When a corporation receives a “C” grade on its debt, the implications are immediate and profound. This grade informs the “cost of capital,” which is the interest rate a company must pay to borrow money. For a C-rated firm, this cost is exceptionally high because lenders demand a “risk premium” to compensate for the possibility that they may never be repaid.
Default Risk and Recovery Prospects
A “C” grade in corporate finance is often synonymous with “distressed debt.” At this level, the market is no longer asking if the company will struggle, but rather when it might default and what the recovery value will be during a restructuring or bankruptcy. For a corporation, a C-grade is a signal that the business model is under extreme pressure, perhaps due to declining industry relevance, excessive leverage, or poor management.
However, the “C” grade also attracts a specific type of financial professional: the distressed debt investor. These individuals specialize in buying the debt of C-rated companies at a steep discount—sometimes for pennies on the dollar—betting that the company will successfully reorganize and eventually see its grade improve. In this context, “C” stands for a complex calculation of survival.
The Impact on Business Operations
Beyond the balance sheet, a C-grade rating affects a company’s ability to operate day-to-day. Suppliers may become hesitant to offer favorable credit terms, requiring cash on delivery instead. Top-tier talent may view the company as a sinking ship, leading to a “brain drain.” Thus, the grade becomes a self-fulfilling prophecy in some regards; the lower the grade, the harder it becomes to secure the resources necessary to improve the grade.
The Consumer Perspective: Navigating a “C” Grade Credit Score

On a personal level, the question of what “C” stands for in grades translates directly to credit score tiers. While credit scores like FICO are numerical (ranging from 300 to 850), lenders often categorize these numbers into letter-grade equivalents. A “C” grade credit score typically falls in the “Fair” range, roughly between 580 and 669.
The “Fair” Credit Paradox
Having a “C” grade credit score is a middle-ground that can be frustrating for consumers. It is not quite “poor” (a D or F equivalent), meaning you can still get approved for loans and credit cards. However, it is far from “excellent,” meaning you will not qualify for the best interest rates. In the world of personal finance, a “C” grade means you are paying the “convenience tax” of higher interest.
For example, on a 30-year fixed mortgage, the difference between an “A” grade credit score (760+) and a “C” grade score (640) can result in tens of thousands of dollars in extra interest payments over the life of the loan. In this niche, “C” stands for “Costly.”
Bridging the Gap to Better Rates
For the individual, a C-grade is often a temporary state resulting from a high credit utilization ratio, a few late payments, or a lack of credit history. Unlike a corporate “C” which might signal impending doom, a consumer “C” is often a “work in progress” grade. Financial tools and apps now allow consumers to monitor these grades in real-time, providing actionable steps to move from the “C” tier to the “B” or “A” tiers by optimizing their financial habits.
Investing in the “C” Tier: Risks, Rewards, and Market Realities
For the sophisticated investor, “C” stands for “Contrarian.” The “C” grade represents the high-yield bond market, colloquially known as “junk bonds.” While the risk of default is high, the potential for high returns is what keeps the market for C-rated debt active and liquid.
The High-Yield Bond Market
When an investor buys a C-rated bond, they are essentially providing a high-interest loan to a company that most traditional banks won’t touch. The “yield” or interest rate on these bonds is significantly higher than that of Treasury bonds or A-rated corporate debt. If the company manages to turn its fortunes around, the bondholder stands to make a significant profit as the bond’s market price rises toward its face value.
The history of finance is filled with “fallen angels”—companies that were once high-rated, dropped to a “C” grade during a crisis, and eventually recovered. Investors who have the stomach for the volatility inherent in C-grades can find alpha (market-beating returns) that is unavailable in the safer tiers of the market.
Risk Mitigation Strategies
Investing in C-grade assets requires a diversified approach. Professional fund managers rarely bet on a single C-rated entity; instead, they invest in “High-Yield ETFs” or mutual funds that hold hundreds of different C-grade bonds. This diversification ensures that even if a few of the companies default (which is expected in this tier), the high interest payments from the others will more than compensate for the losses. In this strategic niche, “C” stands for “Calculated Risk.”
From C to A: Strategies for Elevating Your Financial Grade
Whether you are a corporate CFO or an individual looking to buy a home, moving out of the “C” grade category is a primary financial goal. The path to an “A” requires discipline, transparency, and a long-term perspective.
Deleveraging and Liquidity
The most effective way to move from a C to a B or A grade is to reduce debt—a process known as deleveraging. For a corporation, this might involve selling off non-core assets to pay down high-interest loans. For an individual, it means aggressively paying down credit card balances. Lowering the debt-to-income ratio is the fastest way to signal to grading agencies and lenders that you are becoming less risky.
Consistency and History
In finance, time is a critical component of any grade. A “C” grade often reflects recent instability. To improve the grade, one must demonstrate a consistent history of meeting obligations. For credit scores, this means making every payment on time for several years. For corporations, it means meeting quarterly earnings guidance and maintaining a stable cash flow.
In conclusion, while a “C” in a classroom might be a sign of mediocrity, a “C” in the financial world is a high-stakes marker of volatility, risk, and potential. It represents a pivot point where an entity must either restructure to survive or risk a total default. By understanding what “C” stands for in the context of grades—be it credit ratings, bond yields, or consumer scores—individuals and businesses can better navigate the economic landscape, turning a “speculative” position into a foundation for future growth. In the end, the “C” grade is not a final verdict, but a call to action for better financial management.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.