
In the world of global finance and commodity trading, “potassium”—specifically in its industrial form as potash—is often referred to as “pink gold.” While the general public views potassium through the lens of nutrition and health, the financial sector views it as a foundational pillar of the global food supply chain and a high-stakes investment vehicle. However, just as the human body suffers from hyperkalemia when potassium levels are too high, the global economy faces significant “side effects” when there is an overabundance of this mineral in the market.
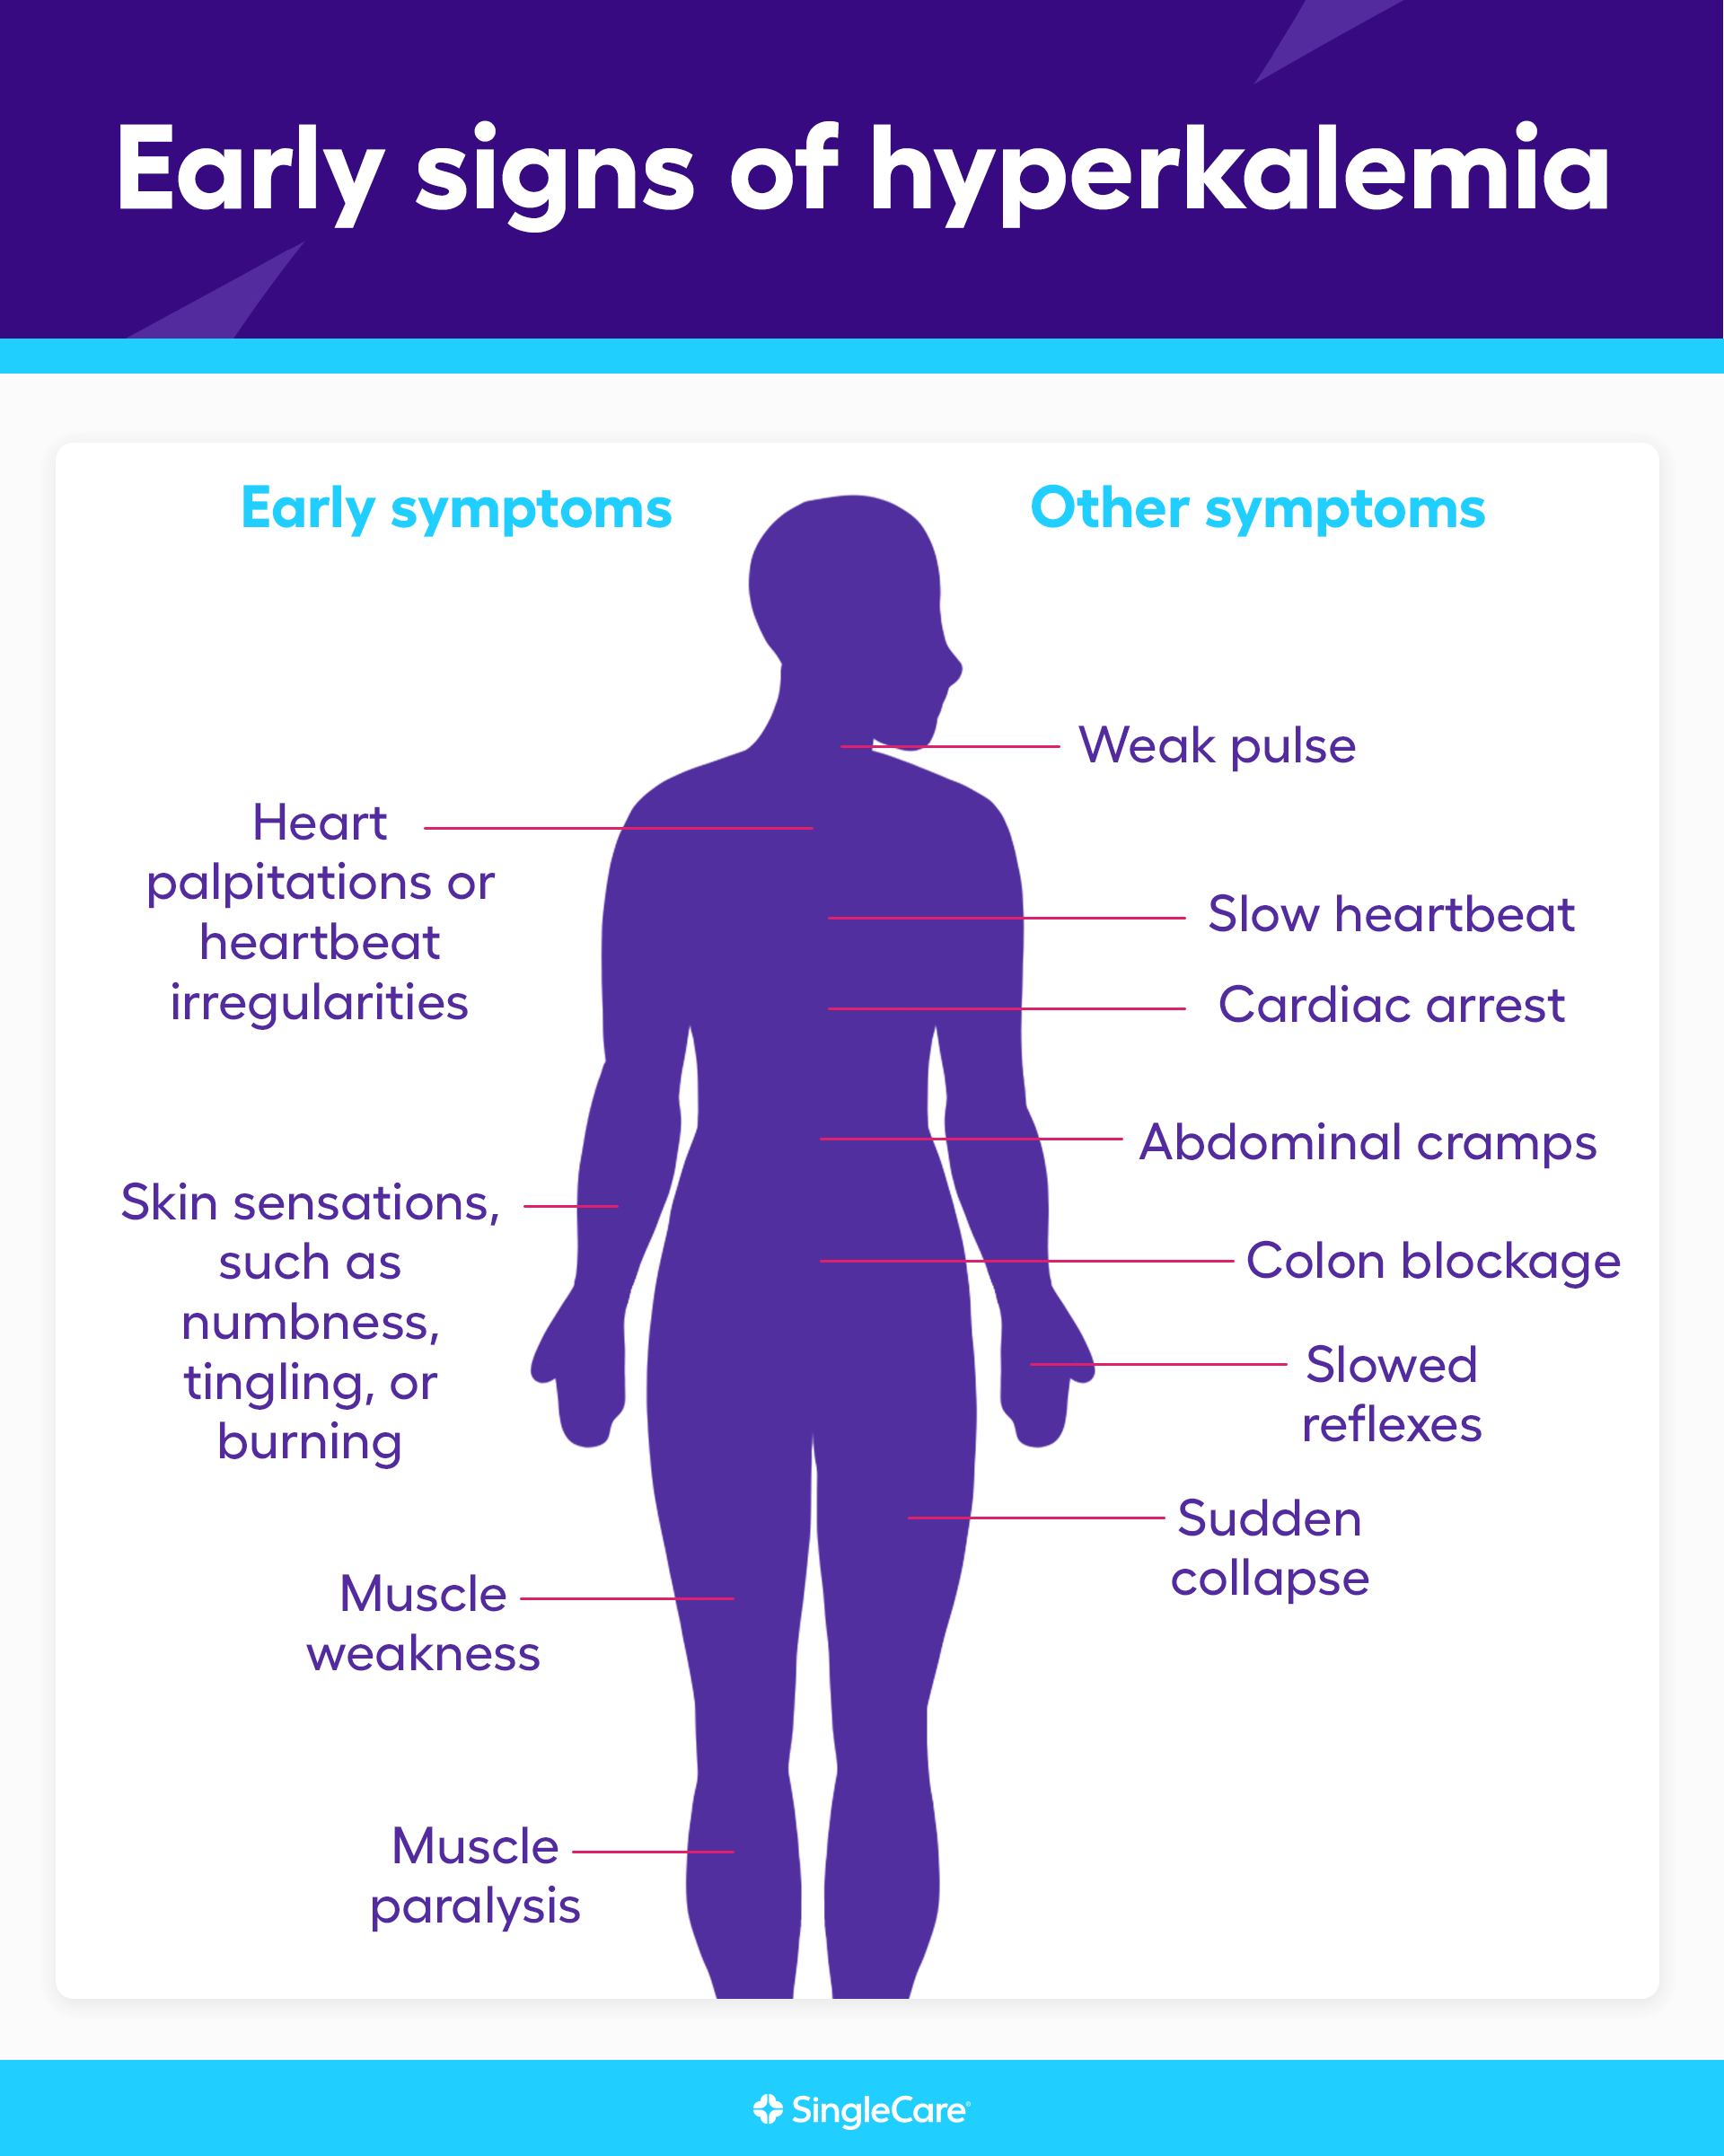
For investors, understanding the side effects of an oversupplied potassium market is crucial for portfolio management. When supply exceeds demand, the resulting price depressions, equity devaluations, and geopolitical shifts create a complex landscape that requires a sophisticated financial approach. This article explores the economic implications of potassium oversupply, the risks to personal and corporate finance, and the strategies required to navigate a market saturated with this vital commodity.
The Global Potassium Market: Understanding Potash as a Strategic Asset
To understand the side effects of “too much” potassium in a financial context, one must first recognize its role as a strategic asset. Potassium, primarily traded as potash (potassium chloride), is one of the three essential nutrients in commercial fertilizers, alongside nitrogen and phosphorus. Because it is indispensable for crop yields and food security, it is a multibillion-dollar industry dominated by a handful of major players and sovereign entities.
From Soil to Stocks: Why Investors Track Potassium
For the personal investor, potassium represents a play on global demographics. As the world population climbs toward 10 billion, the demand for high-yield agriculture increases. This makes potash mining companies—such as Nutrien, Mosaic, and K+S—staples in many commodity-focused portfolios. Investors track potassium prices not because they are interested in the mineral itself, but because those prices dictate the profitability of the agricultural sector.
When potassium levels in the market are balanced, these stocks provide steady dividends and capital appreciation. However, because potash is a capital-intensive industry with long lead times for new mines, the market is prone to extreme cycles. Identifying the transition from “not enough” to “too much” is the difference between capturing a windfall and catching a falling knife.
The Geopolitics of Potash Production
The potassium market is unique because its supply is geographically concentrated. A significant portion of the world’s potash comes from Canada, Russia, and Belarus. This concentration introduces a “geopolitical premium” to the commodity. When supply is restricted due to sanctions or conflict, prices skyrocket. Conversely, when these regions ramp up production simultaneously to capture market share, the side effect is a flooded market that can suppress global prices for years. For the macro-investor, potassium is as much a study in international relations as it is in chemistry or geology.
Side Effects of Oversupply: When the Market Hits “Hyperkalemia”
In financial terms, “too much potassium” refers to a state of chronic oversupply or “inventory glut.” When the market reaches this state, the side effects are felt throughout the entire agricultural value chain. For investors and business owners, these side effects manifest as reduced margins, dividend cuts, and increased market volatility.
Price Volatility and Margin Compression
The most immediate side effect of an oversupplied potassium market is a sharp decline in the “spot price” of potash. Because the fixed costs of operating a potash mine are incredibly high, producers are often hesitant to cut production even when prices fall. This leads to a race to the bottom.
For the investor, this results in “margin compression.” Mining companies see their revenues drop while their operational costs remain stagnant. This squeeze often leads to a revaluation of the company’s stock. If you are holding equity in a potash producer during a period of oversupply, the “side effect” is a rapid erosion of principal value. We saw this historically during the breakup of the Belarusian Potash Company (BPC) cartel in 2013, which sent global potash prices tumbling and wiped out billions in market capitalization overnight.
The Impact on Agricultural ETFs and Mining Equities
The side effects of too much potassium extend beyond individual stocks to broader financial instruments like Exchange Traded Funds (ETFs). Funds that track the global agribusiness sector (such as MOO or VEGI) are heavily weighted toward fertilizer producers. When potassium supply is too high, it drags down the performance of the entire agricultural sector.
Furthermore, oversupply can lead to a “credit side effect.” Smaller mining operations or junior explorers often rely on debt to fund their projects. When potassium prices remain low due to oversupply, these companies may struggle to service their debt, leading to credit downgrades or bankruptcies. This creates a ripple effect in the high-yield bond markets, proving that an excess of a “good” commodity can have toxic financial consequences.
Investing Strategies: Navigating the Boom-and-Bust Cycle
Given the volatile nature of the potassium market, how should a savvy investor manage the risks associated with oversupply? Navigating the side effects of “too much” potassium requires a combination of contrarian thinking and disciplined risk management.
Identifying Value in Down Cycles
While an oversupply of potassium is generally viewed as a negative for short-term traders, it creates a “value play” for long-term investors. The side effect of depressed prices is that high-quality assets often become undervalued.
In the commodity world, the cure for low prices is low prices. When the market is flooded with potassium, high-cost mines are eventually forced to shut down, and new projects are canceled. This eventually leads to a supply deficit, which triggers the next bull market. Professional investors look for “low-cost producers”—companies that can remain profitable even when potassium prices are at their floor. These companies are the “survivalists” of the financial world, capable of weathering the side effects of oversupply while their competitors falter.
Diversification and Long-Term Yields
To mitigate the risks of “too much potassium” in a portfolio, diversification is essential. An investor should not be purely exposed to potash but should balance their holdings across the “NPK” spectrum (Nitrogen, Phosphorus, and Potassium) and into downstream agricultural tech.
Additionally, investors should look at “royalty companies” in the potash space. These firms do not operate the mines themselves but instead own the land or the rights to the minerals. They receive a percentage of the revenue regardless of the mine’s profit margins. This structure provides a financial buffer against the negative side effects of price volatility, offering a more stable income stream for those looking for “Money” niche stability within a volatile “Commodity” sector.
Future Outlook: The Role of Potassium in the Green Economy
As we look toward the next decade, the “side effects” of potassium management will be influenced by new technological and environmental factors. The financial landscape for potassium is shifting from a simple bulk commodity play to a sophisticated component of the “Green Economy” and ESG (Environmental, Social, and Governance) investing.
Vertical Farming and High-Efficiency Fertilizers
One way to combat the side effects of traditional market oversupply is the development of “specialty” potassium products. The rise of vertical farming and precision agriculture requires water-soluble potassium and low-chloride variants. These are high-margin products that do not suffer from the same “inventory glut” issues as standard red potash.
Investors are increasingly looking toward AgTech companies that specialize in “potassium efficiency.” If technology can help farmers get more out of less potassium, the demand for bulk potash might stabilize, reducing the frequency of oversupply “side effects.” This represents a shift from a volume-based business model to a value-based one—a transition that is highly attractive to private equity and venture capital.
Risks of Regulatory Shifts and Environmental ESG Standards
Finally, the “side effects” of potassium production are increasingly measured in environmental terms, which has a direct financial impact. Potash mining is energy-intensive and produces significant salt tailings. As ESG mandates become more stringent, companies with high carbon footprints or poor waste management will face higher capital costs.
For the modern investor, the “side effect” of “too much potassium” production may not just be a lower price, but a “carbon penalty” that affects the company’s bottom line. Investing in 2024 and beyond requires an analysis of how potassium producers are adapting to a net-zero world. Those who fail to innovate will find their stocks “stranded assets,” regardless of how much potassium they have in the ground.
In conclusion, while potassium is essential for life, “too much” of it in the global marketplace creates a series of financial side effects that can destabilize portfolios and shift global wealth. By understanding the mechanics of oversupply, the geopolitical risks of production, and the emerging trends in AgTech, investors can turn these “side effects” into opportunities for long-term financial growth. Whether you are a retail investor or a fund manager, the lesson is clear: in the world of money, balance is just as important as it is in biology.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.