
In the intricate landscape of personal finance, few numbers hold as much sway over individual wealth and economic stability as mortgage rates. For prospective homebuyers, current homeowners considering refinancing, or even investors eyeing real estate opportunities, understanding the prevailing mortgage rates is not just a matter of curiosity—it’s a critical component of strategic financial planning. These rates dictate the cost of borrowing for what is often the largest financial commitment a person will make, directly impacting monthly payments, overall loan costs, and ultimately, purchasing power.
The market for mortgage rates is dynamic, a constantly shifting barometer influenced by a complex interplay of global economic forces, domestic monetary policy, and individual lender strategies. What might seem like a minor percentage point change can translate into tens of thousands of dollars over the lifetime of a loan, underscoring the necessity of staying informed and agile in one’s approach to home financing. This article delves into the current state of mortgage rates, exploring the factors that shape them, strategies for securing favorable terms, and what the future might hold, all within the exclusive lens of personal and business finance.
Understanding the Dynamics of Mortgage Rates
To truly grasp “what are the mortgage rates right now,” one must first appreciate the intricate web of economic indicators and policy decisions that dictate their trajectory. Mortgage rates are not set in a vacuum; they are a direct reflection of broader financial market conditions and the perceived risk associated with lending.
Key Factors Influencing Rates
Several powerful forces conspire to move mortgage rates up or down, often with surprising speed.
-
Inflation: Perhaps the most significant driver, inflation erodes the purchasing power of money over time. Lenders, to protect their future returns, demand higher interest rates when inflation is high or expected to rise. The Federal Reserve often combats inflation by raising its benchmark interest rate, which has a ripple effect across all lending products, including mortgages.
-
Federal Reserve Policy: While the Federal Reserve does not directly set mortgage rates, its actions profoundly influence them. The Fed’s primary tool is the federal funds rate, a target rate for overnight borrowing between banks. When the Fed raises this rate, it typically makes borrowing more expensive throughout the economy, pushing up mortgage rates. Additionally, the Fed’s quantitative easing or tightening policies (buying or selling government bonds) can impact long-term rates.
-
Economic Indicators: A robust economy, characterized by strong GDP growth and low unemployment, can signal inflationary pressures, often leading to higher rates. Conversely, a weakening economy might prompt the Fed to lower rates to stimulate activity. Consumer confidence, housing market data, and manufacturing reports are all closely watched for clues about the economy’s direction.
-
Bond Market (10-Year Treasury Yield): Mortgage rates, particularly for fixed-rate mortgages, are closely tied to the yield on the 10-year U.S. Treasury note. As Treasury yields rise, so too do mortgage rates, as investors demand a higher return on their mortgage-backed securities to compensate for the alternative safe investment offered by Treasuries.
-
Global Events: Geopolitical instability, international trade disputes, and global economic crises can create uncertainty in financial markets. Investors often seek safety in U.S. Treasury bonds during such times, which can paradoxically push Treasury yields down and, consequently, lower mortgage rates. However, if these events create inflationary pressures or economic downturns, the opposite can occur.
Fixed vs. Adjustable-Rate Mortgages (ARMs)
The type of mortgage chosen significantly impacts how “current” rates affect a borrower.
-
Fixed-Rate Mortgages: These loans maintain the same interest rate for the entire term of the loan (e.g., 15 or 30 years). They offer predictability and stability, protecting borrowers from future rate hikes. When rates are low, fixed-rate mortgages are highly desirable, as they lock in a favorable cost of borrowing for decades. When rates are high, borrowers might find the initial payments steeper, but they gain certainty.
-
Adjustable-Rate Mortgages (ARMs): ARMs feature an initial fixed-rate period (e.g., 3, 5, 7, or 10 years), after which the rate adjusts periodically based on an index plus a margin. While ARMs typically offer a lower initial interest rate than comparable fixed-rate mortgages, they come with the risk of future payment increases if interest rates rise. They can be attractive when rates are high and expected to fall, or for borrowers who plan to sell or refinance before the fixed-rate period ends. Understanding the “cap” structures (how much the rate can adjust per period and over the lifetime of the loan) is crucial for ARM borrowers.
How Lenders Determine Your Rate
Beyond macroeconomic factors, your individual financial profile plays a substantial role in the rate you receive.
-
Credit Score: A higher credit score (e.g., FICO score of 740+) signals to lenders that you are a responsible borrower, often qualifying you for the lowest available rates. Lower scores, indicating higher risk, lead to higher interest rates.
-
Debt-to-Income (DTI) Ratio: This ratio compares your total monthly debt payments to your gross monthly income. A lower DTI indicates that you have more disposable income to cover your mortgage payments, making you a less risky borrower and potentially eligible for better rates.
-
Loan-to-Value (LTV): The LTV ratio compares the loan amount to the appraised value of the home. A larger down payment results in a lower LTV, signifying less risk for the lender and often leading to more favorable rates.
-
Loan Type and Term: Different loan programs (e.g., conventional, FHA, VA, USDA, jumbo) have varying risk profiles and, therefore, different rate structures. A shorter loan term (e.g., 15 years vs. 30 years) typically carries a lower interest rate, though with higher monthly payments.
-
Market Competition: Lenders compete for business, and this competition can lead to slightly better rates for well-qualified borrowers. Shopping around is always recommended.
Navigating the Current Mortgage Rate Landscape
The immediate question for many is, “what are the mortgage rates right now?” While specific real-time rates fluctuate hourly and depend on individual borrower profiles, we can discuss the prevailing trends and general conditions that define today’s mortgage market.
The Current Snapshot (General Trends)
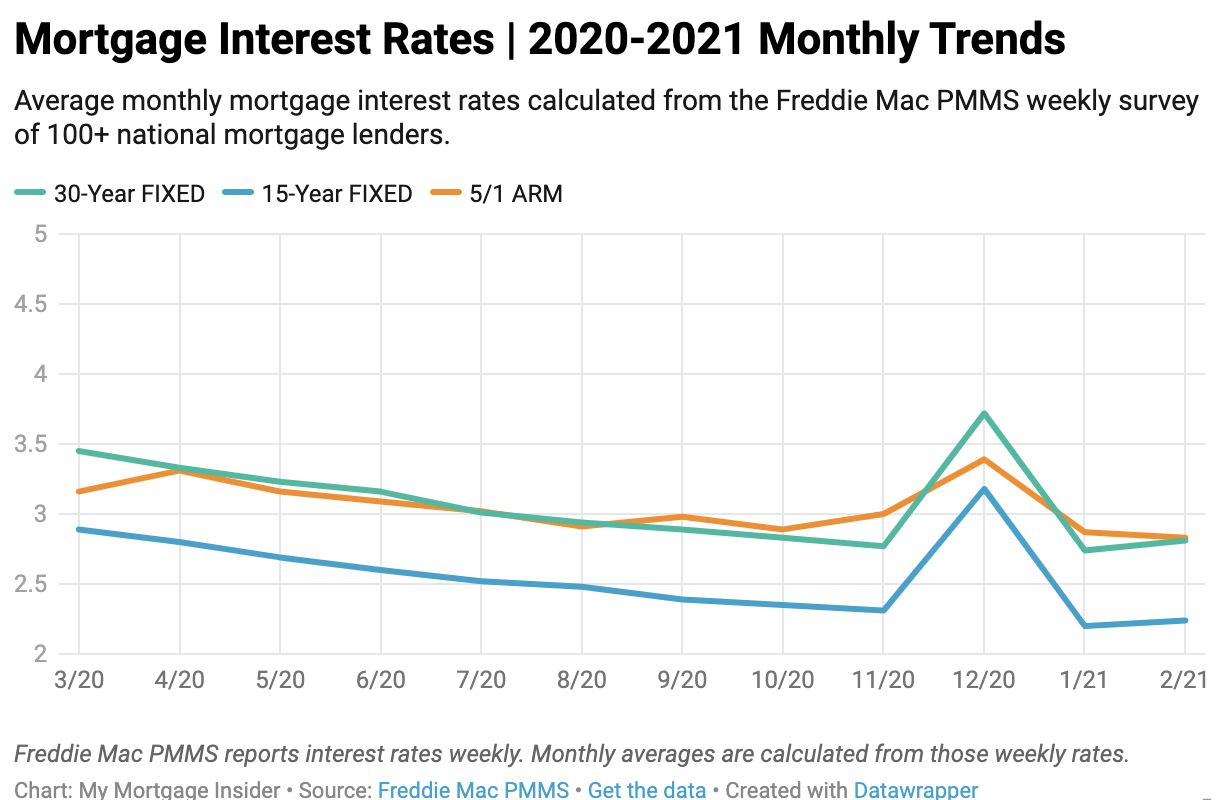
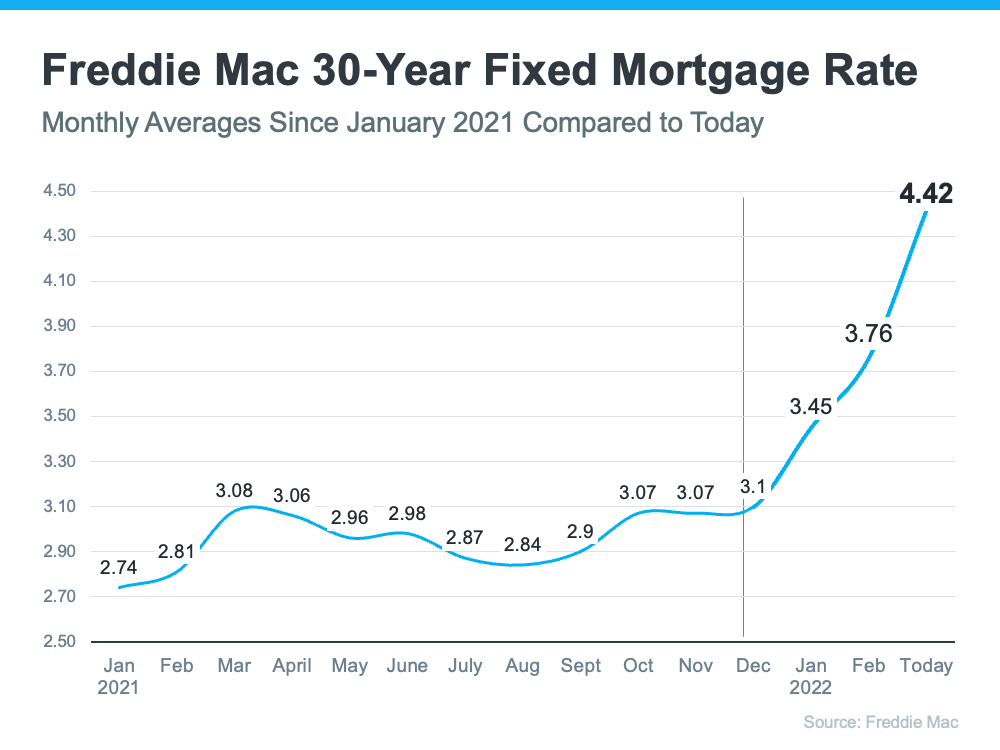
Following a period of historically low rates (particularly during the initial phases of the COVID-19 pandemic), mortgage rates have generally trended upwards, reaching levels not seen in over a decade. This ascent has largely been driven by the Federal Reserve’s aggressive interest rate hikes aimed at combating persistent inflation. The market has observed periods of significant volatility, with rates reacting sharply to economic data releases (such as inflation reports and employment figures) and signals from the Fed.
Currently, rates are often characterized as elevated compared to the lows of recent years but have shown signs of stabilizing or even moderating slightly as inflation appears to be cooling and the Fed nears the end of its tightening cycle. However, this stability is often fragile, susceptible to any new economic shocks or shifts in policy expectations. Borrowers should anticipate rates that are notably higher than those available in the early 2020s, significantly impacting affordability and monthly housing costs.
Regional Variations and Loan Types
It’s important to remember that “the” mortgage rate is a generalization. Actual rates can vary based on several nuanced factors.
-
Geographical Location: While national averages provide a benchmark, local market conditions, specific lender presence, and even state-specific regulations can lead to slight rate differences across regions.
-
Loan Programs:
-
Conventional Loans: These are the most common type, not insured or guaranteed by the government. Rates are highly sensitive to credit scores and down payments.
-
FHA Loans: Insured by the Federal Housing Administration, these offer more flexible credit requirements and lower down payments, making them accessible to a broader range of buyers. Their rates can sometimes be slightly lower than conventional loans due to the government backing, but they come with mandatory mortgage insurance premiums.
-
VA Loans: Guaranteed by the Department of Veterans Affairs for eligible service members, veterans, and surviving spouses, VA loans often boast some of the lowest interest rates on the market and typically require no down payment.
-
USDA Loans: Backed by the U.S. Department of Agriculture, these are designed for low-to-moderate-income buyers in eligible rural areas. They also offer competitive rates and often require no down payment.
-
Jumbo Loans: For loan amounts exceeding conforming limits set by Fannie Mae and Freddie Mac, jumbo loans typically come with slightly higher rates and stricter underwriting requirements due to their larger risk profile.
-
Impact on Affordability and Homeownership
The current elevated rate environment has had a profound impact on the housing market and prospective homeowners.
-
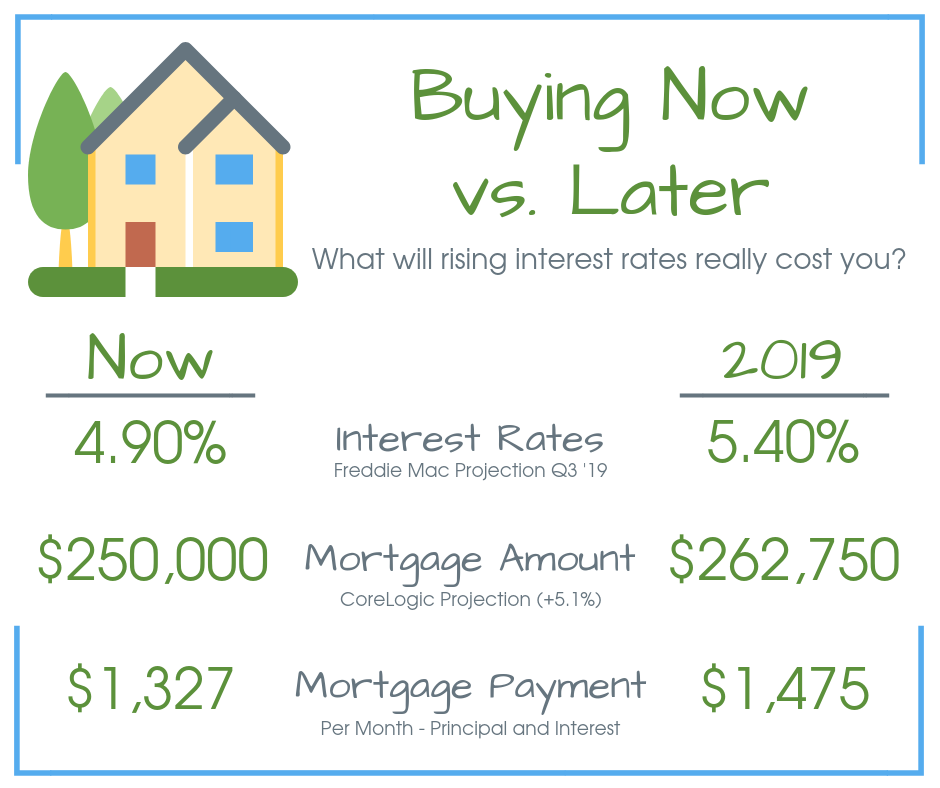
Reduced Affordability: Higher interest rates translate directly to higher monthly mortgage payments for the same loan amount. This reduces purchasing power, meaning buyers either have to settle for smaller homes, homes in less desirable areas, or significantly increase their income to qualify for the same house they could have afforded just a couple of years ago.
-
Cooling Housing Market: The combination of higher rates and still-high home prices has led to a noticeable cooling in the housing market. Demand has softened, inventory levels are slowly improving in some areas as fewer buyers can afford current prices, and some markets are beginning to see price corrections.
-
Refinancing Deterrent: For existing homeowners with mortgages locked in at much lower rates, the current environment makes refinancing unattractive unless it’s for a specific purpose like cash-out equity for home improvements, or to switch from a high-rate ARM to a fixed rate.
Strategies for Securing the Best Mortgage Rate
Even in an elevated rate environment, shrewd financial planning and proactive steps can significantly improve your chances of securing the most favorable mortgage rate available.
Improving Your Financial Profile
Your creditworthiness is paramount. Investing time in strengthening your financial standing before applying for a mortgage can yield substantial savings.
-
Boost Your Credit Score: Pay bills on time, reduce credit card balances, avoid opening new credit accounts, and dispute any errors on your credit report. A higher FICO score demonstrates reliability to lenders.
-
Lower Your Debt-to-Income (DTI) Ratio: Pay down existing debts, especially high-interest consumer debt. A DTI below 36% (with housing costs ideally below 28% of gross income) is generally considered excellent, though lenders may accept higher depending on loan type.
-
Save a Larger Down Payment: A substantial down payment (e.g., 20% or more) not only reduces your loan amount but also lowers your Loan-to-Value (LTV) ratio. A lower LTV signals less risk to the lender, often resulting in a better interest rate and avoiding private mortgage insurance (PMI) on conventional loans.
-
Build Cash Reserves: Lenders look favorably on borrowers with a healthy savings account, as it suggests financial stability and the ability to weather unexpected expenses.
Shopping Around and Comparing Lenders
This is one of the most impactful steps a borrower can take, yet it is frequently overlooked.
-
Get Multiple Quotes: Don’t just go with your current bank. Obtain quotes from at least three to five different lenders, including traditional banks, credit unions, and online mortgage brokers. Rates and fees can vary significantly.
-
Understand the Full Cost: Focus not just on the interest rate but also on the Annual Percentage Rate (APR), which includes fees and other costs associated with the loan. Compare loan estimates carefully.
-
Ask About Lender Fees: Be aware of origination fees, application fees, appraisal fees, and other closing costs. Sometimes a slightly higher rate might come with significantly lower fees, making it a better overall deal.
-
Consider Mortgage Brokers: Brokers can shop multiple lenders on your behalf, potentially finding you a better deal than you might uncover on your own. However, ensure you understand how they are compensated.
Locking in Your Rate
Once you find a rate you’re comfortable with, securing it becomes crucial.
-
What is a Rate Lock?: A rate lock guarantees a specific interest rate for a defined period (e.g., 30, 45, or 60 days) while your loan application is processed. This protects you from rate increases before closing.
-
When to Lock: If you believe rates might rise in the near future, or if you’ve found a rate you’re happy with, locking it in makes sense. However, if you anticipate rates dropping, you might choose to float the rate (not lock it) and potentially secure a lower rate later, though this carries risk.
-
Lock Period: Ensure the lock period is long enough to cover your expected closing date, with a buffer for potential delays. Longer lock periods can sometimes come with a slightly higher rate or an associated fee.
Considering Refinancing
For existing homeowners, the current rate environment might still present opportunities for strategic refinancing, though it’s less about lower rates than about specific financial goals.
-
Cash-Out Refinance: If home equity has grown substantially, a cash-out refinance allows you to tap into that equity, often for home improvements, debt consolidation, or other large expenses, even if the new rate is higher than your existing mortgage.
-
ARM to Fixed Refinance: If you currently have an Adjustable-Rate Mortgage (ARM) and are concerned about future rate increases, refinancing into a fixed-rate mortgage, even at a higher rate than your initial ARM rate, can provide long-term payment stability.
-
Shorter Term Refinance: Even with higher rates, some homeowners might refinance into a shorter-term mortgage (e.g., from 30 to 15 years) to pay off their home faster, if their budget allows for the higher monthly payments. This typically results in significant interest savings over the life of the loan.
The Future Outlook: What to Expect
Predicting the precise movement of mortgage rates is challenging, even for seasoned economists. However, by understanding prevailing market sentiments and potential economic trajectories, borrowers can better prepare for what lies ahead.
Expert Predictions and Market Sentiments
Most financial analysts and economists closely monitor the Federal Reserve’s stance on inflation and monetary policy. The general consensus often revolves around the expectation that the Fed may be nearing the end of its rate-hiking cycle, potentially leading to a period of rate stability or even modest declines if inflation continues to recede towards its target.
However, several factors could alter this outlook:
-
Resurgent Inflation: Unexpected geopolitical events, supply chain disruptions, or stronger-than-anticipated economic growth could reignite inflationary pressures, forcing the Fed to resume rate hikes.
-
Economic Downturn: A significant recession could prompt the Fed to cut rates more aggressively, leading to a notable decline in mortgage rates.
-
Fiscal Policy: Government spending and deficit levels can also influence inflation and bond yields, thereby impacting mortgage rates.
It’s crucial to acknowledge the inherent uncertainty. While projections offer guidance, they are not guarantees. Rates could remain elevated for longer than anticipated or experience more volatility than expected.
Preparing for Rate Fluctuations
In this dynamic environment, adaptability is key.
-
Stay Informed: Regularly check reputable financial news sources, listen to central bank announcements, and monitor economic data releases. Websites of major financial institutions and government agencies (like Freddie Mac and Fannie Mae) often provide weekly rate averages and market insights.
-
Maintain Financial Health: Continuously work on improving your credit score, managing debt, and building savings. A strong financial profile gives you more options and leverage, regardless of market conditions.
-
Consult a Professional: A qualified mortgage lender or financial advisor can provide personalized insights, help you assess your options, and navigate complex market conditions. They can explain the nuances of different loan products and help you understand the true cost of borrowing.
Long-Term Financial Planning
Mortgage decisions are not isolated events; they are integral to a broader financial plan.
-
Housing as an Investment: While a home is primarily a place to live, it also represents a significant asset. Understanding how current and future rates impact your equity growth and overall wealth accumulation is crucial.
-
Budgeting for Flexibility: Build flexibility into your budget to account for potential payment changes if you opt for an ARM, or simply to free up capital for other investments or savings goals.
-
Diversify Your Investments: Don’t put all your financial eggs into real estate. Ensure your overall investment portfolio is diversified to mitigate risks and achieve long-term financial security, complementing your mortgage strategy.
In conclusion, knowing “what are the mortgage rates right now” is about more than just a number; it’s about understanding the complex economic machinery that generates it, and critically, how it impacts your personal financial journey. The current landscape demands diligence, strategic planning, and a willingness to adapt. By staying informed, optimizing your financial profile, and diligently comparing options, you can make empowered decisions that align with your housing goals and contribute to your long-term financial well-being.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.