
In the complex ecosystem of global finance and corporate architecture, the term “daughter cells” serves as a powerful metaphor for the process of organizational reproduction. Just as biological organisms divide to grow, adapt, and ensure survival, modern corporations frequently undergo structural divisions to unlock shareholder value, streamline operations, or pivot toward new market demands. In the financial world, these daughter cells are more commonly known as subsidiaries, spinoffs, or carve-outs. Understanding the mechanics of how these entities are formed, how they operate, and how they impact a portfolio is essential for any serious investor or business strategist.
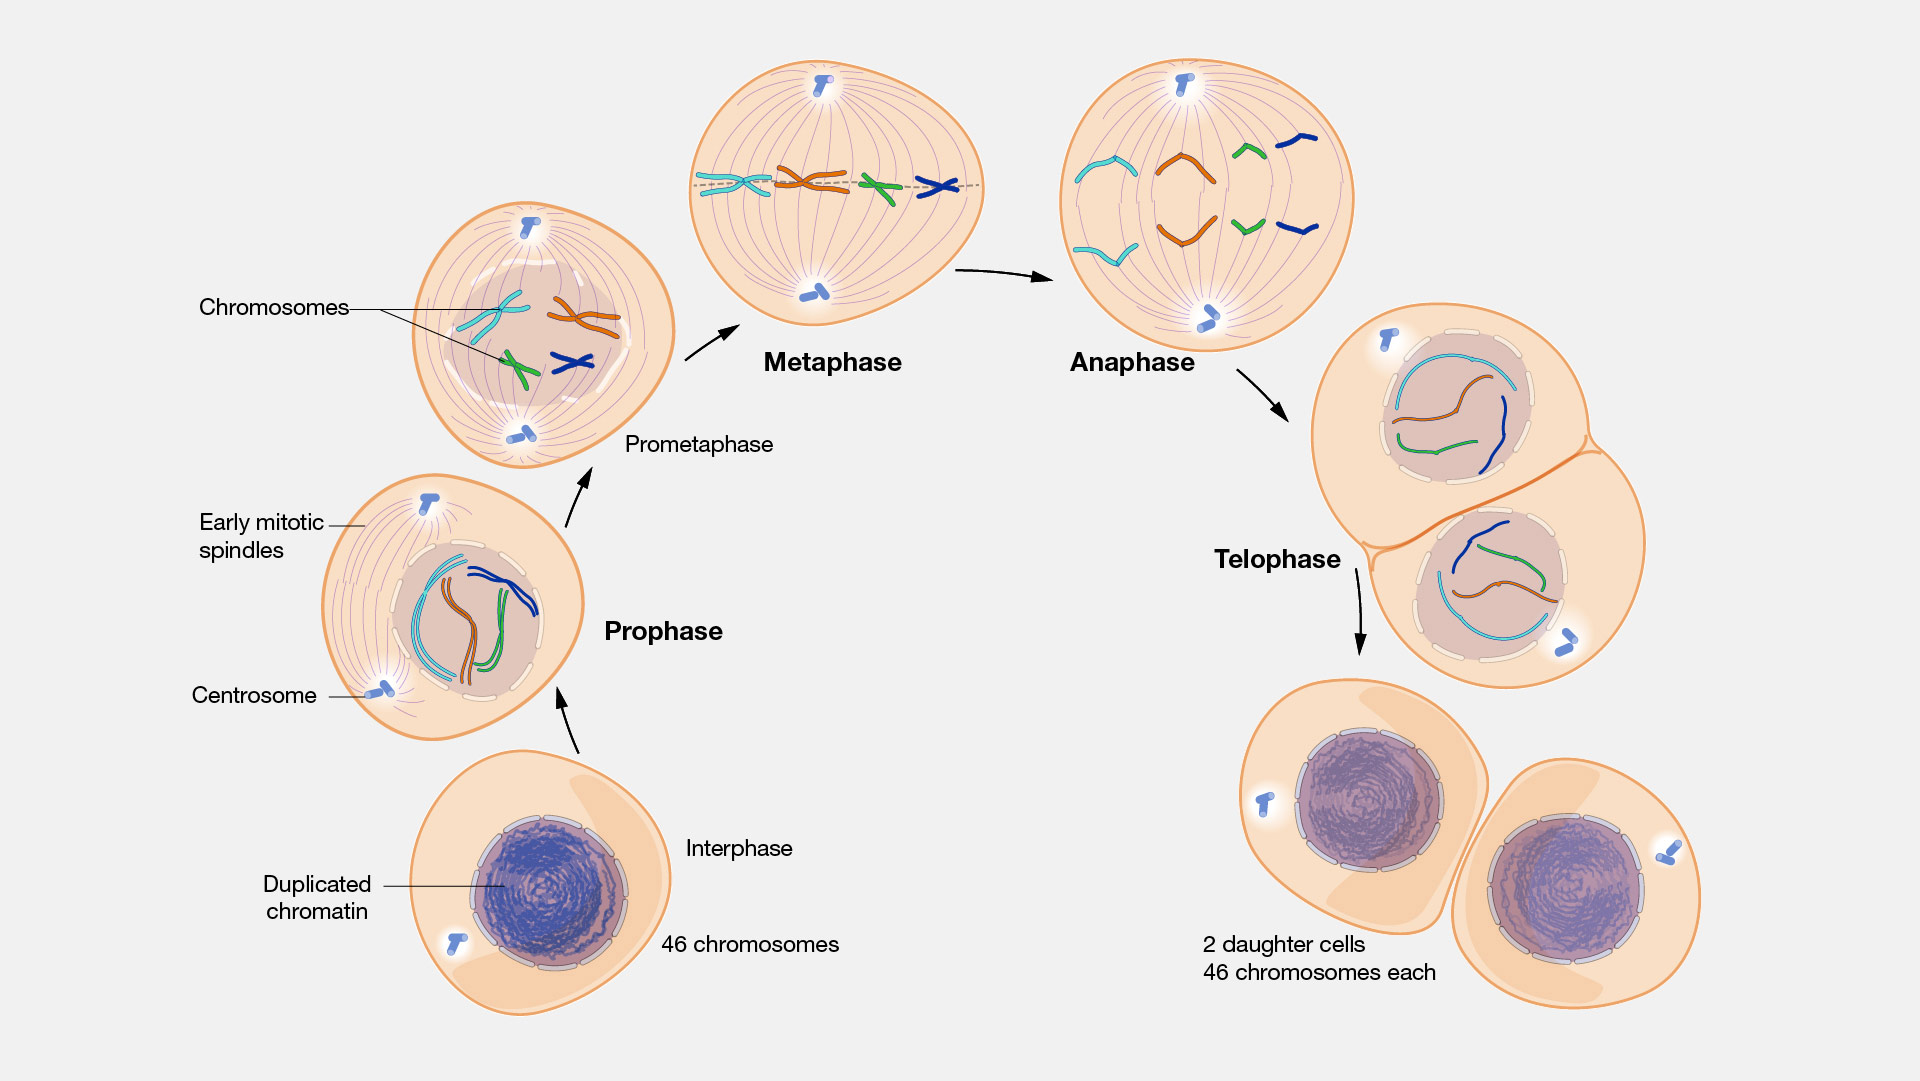
The Anatomy of Corporate Reproduction: Defining the Daughter Cell in Business
To understand a daughter cell in a financial context, one must first look at the “mother” or parent company. A parent company is a single entity that has a controlling interest in another company, giving it the legal power to elect the board of directors and influence management decisions. When a parent company decides to partition a segment of its business into a separate legal entity, it creates a daughter cell.
From Parent to Subsidiary: The Mechanics of Control
A daughter cell often begins its life as a subsidiary. In this arrangement, the parent company retains a significant, often 100%, stake in the new entity. This structure is frequently utilized to isolate risk. For instance, a large multinational may create a daughter cell to house its riskier research and development projects or its operations in a volatile foreign market. By doing so, the parent protects its primary balance sheet from the potential liabilities of the subsidiary.
From a financial reporting perspective, the performance of these daughter cells is typically consolidated into the parent company’s financial statements. However, they maintain their own management structures, localized goals, and often, a distinct corporate culture that allows them to move faster than the larger, more bureaucratic parent.
Why Companies “Divide”: The Strategic Rationale
The decision to create a daughter cell is rarely accidental. It is a calculated move driven by the need for specialization. In a diversified conglomerate, different business units often compete for the same pool of capital. A high-growth tech division might be starved of resources because the parent company is prioritized toward maintaining its legacy industrial manufacturing base.
By “dividing” and creating a dedicated entity, the parent company allows the daughter cell to seek its own funding, establish its own credit rating, and pursue a strategy that is not diluted by the parent’s broader objectives. This process is the financial equivalent of mitosis, where the goal is not just growth, but the creation of a functional, independent unit capable of thriving in its specific niche.
The Spinoff Strategy: Creating Independent Value
While a subsidiary remains under the wing of the parent, a spinoff represents the point where the daughter cell becomes fully independent. In a spinoff, the parent company distributes shares of the daughter cell to its existing shareholders on a pro-rata basis. Suddenly, what was once a department or a division becomes a standalone, publicly traded company.
Unlocking Trapped Value for Shareholders
One of the primary drivers of spinoffs in the world of high finance is the “conglomerate discount.” Historically, the market tends to value a large, multi-industry corporation at less than the sum of its individual parts. This happens because it is difficult for analysts to accurately price a company that does everything from insurance to snack foods.
When a daughter cell is spun off into its own entity, it allows the market to price it based on its own merits. Pure-play companies—those focused on a single industry—typically command higher valuation multiples than conglomerates. For the investor, the “daughter cell” represents a sudden realization of value that was previously “trapped” or hidden within the parent’s complex financial statements.
Operational Focus and Agility
Once a daughter cell is independent, it is no longer beholden to the parent company’s capital allocation committee. It can reinvest its own profits, issue its own debt, and create incentive structures (like stock options) that are tied directly to its own performance rather than the parent’s stock price.
This agility is particularly crucial in tech-heavy or rapidly evolving sectors. A daughter cell that is free to innovate without the oversight of a conservative parent can often outmaneuver larger competitors. This independence fosters an entrepreneurial spirit that is frequently lost in large-scale corporate structures.
Tax Advantages and Financial Engineering
From a business finance perspective, the “reproduction” of a company through a spinoff is often motivated by tax efficiency. In many jurisdictions, if certain criteria are met, the distribution of shares in a daughter cell to shareholders can be structured as a tax-free transaction. This allows the parent company to divest an asset without triggering the massive capital gains taxes that would accompany a straight sale to a third party.
Investing in Daughter Cells: Risks and Opportunities

For the individual investor or the institutional fund manager, the emergence of a new daughter cell presents a unique set of opportunities and challenges. Spinoffs have historically outperformed the broader market over the long term, but the initial period following the “birth” of the new company can be volatile.
The Performance of Spun-off Entities
Studies of market history show that daughter cells often experience a period of selling pressure immediately after they are created. This is frequently due to “institutional churn.” For example, if a large-cap index fund receives shares of a small-cap spinoff, it may be legally required to sell those shares because the new company does not fit the fund’s investment mandate.
This forced selling can drive the price of the daughter cell down to attractive levels, creating a “buying opportunity” for value investors. Once the initial selling pressure subsides, the newly independent management team often finds ways to cut costs and drive growth that were impossible under the parent company’s rule.
Evaluating the Management Team of the New Cell
When a daughter cell is formed, the quality of its leadership is the single most important factor for its future success. Investors must ask: Did the parent company “export” its best talent to the new entity, or is it using the spinoff as a way to offload underperforming executives?
A strong daughter cell will have a management team that is deeply incentivized through equity stakes. When the CEO’s personal wealth is tied directly to the performance of the new company, they are more likely to make the difficult decisions required to ensure the entity’s long-term viability.
Debt Loading and Financial Health
A common pitfall in the creation of daughter cells is the “debt dump.” Parent companies may occasionally load the new entity with a disproportionate amount of the group’s total debt before the spinoff. This cleans up the parent’s balance sheet but leaves the daughter cell struggling with high interest payments from day one.
Before investing in a newly formed daughter cell, it is imperative to analyze the pro-forma financial statements. An entity that is born with an unsustainable debt-to-equity ratio faces an uphill battle, regardless of how innovative its product line may be.
Case Studies: Successful and Failed Corporate Divisions
To understand the lifecycle of daughter cells, we must look at real-world examples where these financial divisions have reshaped entire industries.
Tech Giants and Their Progeny
In the technology sector, the creation of daughter cells is often a response to regulatory pressure or the need to separate high-growth software divisions from legacy hardware businesses. A classic example is the Hewlett-Packard split, which resulted in HP Inc. (focused on PCs and printers) and Hewlett Packard Enterprise (focused on servers and cloud services). This division allowed two very different businesses to pursue their own capital structures and R&D paths, resulting in more focused entities that could better serve their respective markets.
Lessons from Industrial Conglomerates
Perhaps the most famous recent example of corporate “mitosis” is the three-way split of General Electric (GE). For decades, GE was the ultimate parent, a sprawling conglomerate with its hands in everything from jet engines to television networks and subprime mortgages. The weight of this complexity eventually became a liability.
By dividing into three distinct “daughter cells”—GE Aerospace, GE Vernova (energy), and GE HealthCare—the company effectively ended the conglomerate era. Each of these entities now operates with its own balance sheet and strategic focus. This massive restructuring was designed to prove that the “cells” are more valuable when they are allowed to function independently than when they are forced into a single, massive organism.

Future Trends: The Evolution of Lean Corporate Architectures
As we look toward the future of business finance, the trend toward smaller, more specialized daughter cells is likely to accelerate. The rise of “platform” companies—which provide the infrastructure for many smaller entities to operate—is changing how we think about corporate parentage.
In the digital economy, we are seeing the rise of “micro-spinoffs,” where companies use blockchain and decentralized finance (DeFi) tools to create autonomous daughter cells that operate with minimal human intervention. These entities may hold their own digital assets, execute contracts automatically, and return value to “parent” token holders without the need for traditional corporate overhead.
Furthermore, as ESG (Environmental, Social, and Governance) investing becomes the standard, parent companies are increasingly spinning off “brown” assets (such as coal or oil divisions) into separate daughter cells to improve the parent’s ESG rating. While this practice is controversial, it underscores the role of the daughter cell as a tool for financial and reputational engineering.
Ultimately, the daughter cells of the corporate world represent the ongoing cycle of renewal in the global economy. Whether they are created to isolate risk, unlock value, or simplify a complex organization, these entities are the primary drivers of structural change. For the investor who knows how to identify a healthy daughter cell from a burdened one, the process of corporate division offers some of the most lucrative opportunities in the financial markets. Understanding that a company is not a static object, but a living system capable of reproduction, is the first step in mastering the art of modern business finance.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.