
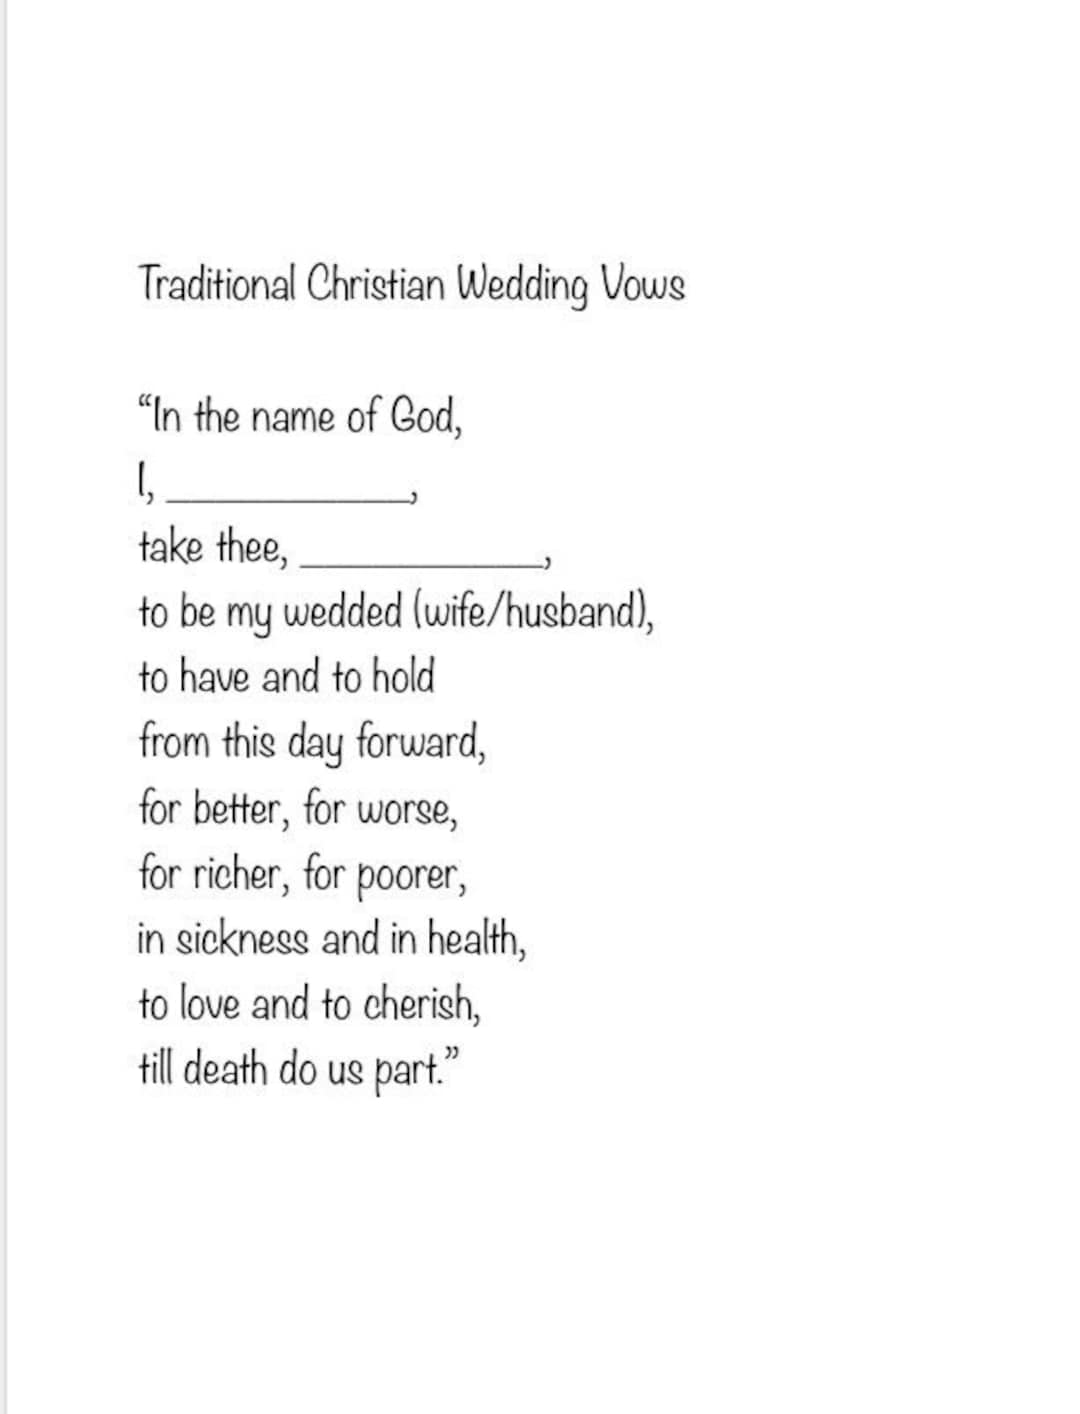
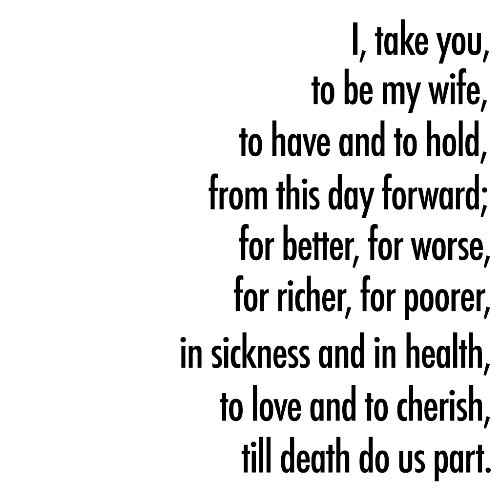
When we examine the concept of wedding vows, we often view them through a lens of sentimentality, tradition, and romance. However, from a strictly financial and professional perspective, basic wedding vows represent the most significant contractual agreement most individuals will ever sign. They are the foundational bylaws of a domestic partnership that functions as a micro-corporation. In this context, “for richer, for poorer” is not merely a poetic sentiment; it is a declaration of asset consolidation and a commitment to shared liability management.
To understand the basic wedding vows in a fiscal context, one must look past the ceremony and into the structural impact these commitments have on personal finance, wealth accumulation, and risk mitigation. This article explores the core components of these “vows” as they relate to the business of building a life together, treating the marriage union as a strategic financial merger.

The Financial Covenant: Deconstructing “For Richer, For Poorer”
The phrase “for richer, for poorer” is the quintessential financial vow. In a modern economic landscape, this translates to a comprehensive agreement on how a couple will navigate the fluctuations of the market, career shifts, and economic cycles. It is the verbal equivalent of a joint venture agreement where both parties commit to maintaining the stability of the enterprise regardless of external economic pressures.
Asset Consolidation and Liability Management
At its core, the basic financial vow is a commitment to the pooling of resources. When two individuals marry, they are often merging two distinct financial portfolios. This includes liquid assets, real estate, retirement accounts, and human capital. The “basic” vow implies that these assets will be managed for the benefit of the collective unit rather than the individual.
Liability management is the darker side of this merger. By vowing to stay “for poorer,” partners are essentially agreeing to take on the “bad debt” or financial setbacks of the other. Whether it is student loan debt, credit card balances, or a failing business venture, the basic wedding vow serves as a guarantee that the partner will not liquidate their interest in the relationship when the balance sheet turns negative. This provides a unique form of social and financial insurance that is difficult to replicate in any other legal structure.
The Socio-Economic Impact of Income Pooling
Research consistently shows that married couples tend to accumulate more wealth over their lifetimes than single individuals or those who cohabitate without legal ties. The basic vow facilitates this through the “power of two.” Dual-income households benefit from economies of scale—sharing a single mortgage, one set of utility bills, and potentially lower insurance premiums.
Furthermore, the commitment inherent in wedding vows allows for long-term financial specialization. One partner may take a high-risk, high-reward career path while the other provides a stable income and health benefits. This diversification of income streams is a direct result of the security provided by the basic wedding vow, allowing the “corporate entity” of the family to take calculated risks that an individual might find too perilous.
Establishing the Fiscal Framework of a Modern Marriage
While traditional vows provide the overarching philosophy, the modern “basic” vows require a more granular level of financial transparency. In the 21st century, the commitment to share a life implies a commitment to share a ledger. Financial infidelity—the act of hiding debt or spending from a partner—is often cited as a leading cause of the dissolution of these partnerships. Therefore, the contemporary basic vow includes several unwritten but essential financial pillars.
Transparency and the Disclosure of Debt
Before the “I do,” there is an implicit vow of full financial disclosure. In a professional financial setting, this would be known as the due diligence phase of a merger. Each partner must bring their financial history to the table, including credit scores, outstanding obligations, and spending habits.
The basic vow of honesty in a marriage extends to the ongoing management of the household budget. Establishing a baseline of trust regarding how money is earned, saved, and spent is vital. When this vow is upheld, it creates a stable environment for capital allocation. Without it, the “merger” is built on a foundation of hidden liabilities that can lead to catastrophic failure during an audit (or a divorce).
Aligning Investment Philosophies
One of the most critical “basic” vows for a financially successful marriage is the alignment of risk tolerance. If one partner is a conservative investor focusing on treasury bonds and savings accounts, while the other is an aggressive speculator in high-volatility tech stocks or cryptocurrency, the partnership will face constant internal friction.
A successful financial union requires a unified investment policy statement (IPS). This involves vowing to discuss and agree upon major financial milestones: when to buy a home, how much to save for children’s education, and what the retirement timeline looks like. By aligning these philosophies early, the couple ensures that their shared capital is working toward a singular vision rather than being tugged in competing directions.
The Legal Vow: Pre-Nuptial Agreements and Protective Asset Allocation
While the spoken vows are the moral framework, the legal “vows” are found in the statutes of the jurisdiction where the couple resides. In many ways, the government provides a “default” set of vows regarding property division and spousal support. For many high-net-worth individuals or those with complex business interests, these default vows are insufficient.
Defining Separate vs. Marital Property
In the eyes of the law, the basic wedding vow triggers a transition from “mine” to “ours.” However, the distinction between separate property (assets owned before the marriage) and marital property (assets acquired during the marriage) is a frequent point of contention.
A pre-nuptial agreement is not a sign of a lack of trust; rather, it is a sophisticated refinement of the basic wedding vows. It provides a clear roadmap for asset allocation and protection, ensuring that the “merger” has a clear operating agreement. This level of clarity can actually strengthen a marriage by removing the financial ambiguity that often leads to anxiety and conflict.
Managing Risk in the Context of a Legal Union
The legal vows also encompass the protection of the estate. This includes the creation of wills, trusts, and power of attorney documents. A commitment to “care for one another” is professionally expressed through comprehensive estate planning. This ensures that in the event of the “sickness” or “death” mentioned in traditional vows, the surviving partner is not left with a legal and financial quagmire. Managing risk through insurance—life, disability, and long-term care—is the practical application of the vow to protect the partner’s well-being.
Long-Term Financial Planning: From Vows to Estate Strategy
The true test of the basic wedding vows is found in the long-term compounding of shared decisions. A marriage is a multi-decade investment horizon. The promises made at the altar serve as the initial capital injection into a project that is expected to yield dividends for forty, fifty, or sixty years.
Beneficiary Designations and Life Insurance
One of the most practical ways to uphold the vow of protection is through the strategic use of beneficiary designations. Upon marriage, the “basic” action is to update life insurance policies, 401(k) accounts, and IRAs to reflect the new partnership. This is a transfer of potential wealth that secures the future of the entity. In a professional sense, this is the ultimate act of fiduciary duty to one’s partner. It ensures that the “business” of the family continues even if one of the founding partners is no longer present.
Building a Generational Legacy Through Shared Fiscal Discipline
The final stage of the financial wedding vow is the transition from wealth accumulation to wealth transfer. The “basic” vows lay the groundwork for how a couple will interact with the next generation. Whether through funding education for descendants or establishing a charitable foundation, the way a couple manages their surplus capital is a reflection of their shared values.
A couple that adheres to the fiscal discipline implied by their vows—living within their means, avoiding destructive debt, and investing for the long term—is capable of building a generational legacy. This legacy is the ultimate Return on Investment (ROI) of the wedding vows. It proves that the union was not just a social arrangement, but a highly effective financial strategy that multiplied the impact of two individuals into something far greater than the sum of its parts.
In conclusion, “what are the basic wedding vows” is a question that can be answered through the lens of romance, but it is best understood through the lens of commitment and capital. By treating these vows as a professional and financial covenant, couples can build a foundation that is not only emotionally fulfilling but fiscally invincible. The merger of two lives is, at its heart, the merger of two financial futures, and the basic vows are the terms upon which that future is built.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.