
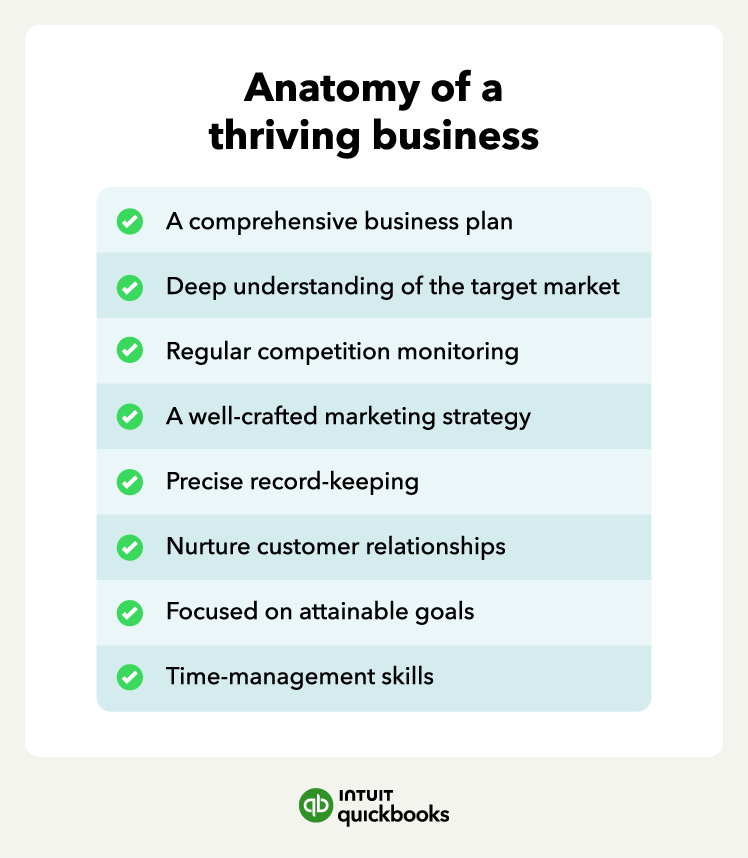
Running a good business is often framed as a matter of passion or product quality, but at its core, a truly successful enterprise is built on the foundation of sound financial management. While vision provides the direction, financial discipline provides the fuel. A good business is one that is not only profitable today but is structured to sustain that profitability through market cycles, competitive shifts, and internal growth. To achieve this, a business owner must transition from a “practitioner” mindset to a “financier” mindset, focusing on cash flow, capital allocation, unit economics, and long-term enterprise value.
The Foundation of Financial Health: Mastering Cash Flow Management
The most common reason for business failure is not a lack of revenue, but a lack of liquidity. A “good” business is defined by its ability to generate consistent, predictable cash flow that exceeds its operational requirements. Understanding the distinction between accounting profit and actual cash flow is the first step toward professional business management.
Understanding the Velocity of Capital
Profit is an opinion; cash is a fact. A business can report significant earnings on an income statement while simultaneously starving for cash because that capital is tied up in accounts receivable, inventory, or prepaid expenses. To run a good business, leadership must monitor the “Cash Conversion Cycle” (CCC). This metric measures how fast a dollar spent on inputs returns as a dollar of revenue.
By shortening the CCC—negotiating better payment terms with suppliers, incentivizing early payments from customers, and optimizing inventory turnover—a business increases its internal rate of return. A high velocity of capital allows a business to fund its own growth without relying on expensive external debt or diluting equity through venture capital.
The Necessity of Liquidity Buffers
A good business is also a resilient one. Financial stability requires a disciplined approach to cash reserves. Many entrepreneurs make the mistake of reinvesting every spare cent back into growth, leaving the company vulnerable to a single bad month or a sudden economic downturn.
Maintaining a “Fortress Balance Sheet” involves keeping a minimum of three to six months of operating expenses in highly liquid accounts. This buffer serves two purposes: it acts as insurance against volatility, and it provides “opportunistic capital.” When competitors are struggling during a recession, the business with high liquidity can acquire talent, inventory, or even other companies at a discount.
Strategic Capital Allocation and Reinvestment
Once a business is cash-flow positive, the primary responsibility of the owner shifts to capital allocation. How you spend the money you make determines whether the business stagnates, grows at a moderate pace, or scales exponentially.
Optimizing Return on Invested Capital (ROIC)
Every dollar that stays in the business should be viewed as an investment. A good business operator evaluates potential expenditures based on their expected Return on Invested Capital (ROIC). If a business spends $50,000 on a new piece of equipment or a marketing campaign, it must have a clear path to generating a return that exceeds the cost of that capital.
To run a business effectively, one must rank opportunities by their “hurdle rate.” If the business can earn a 15% return by expanding into a new geographic territory but only an 8% return by upgrading an office space that is already functional, the capital must flow to the expansion. This level of objectivity prevents “ego spending” and ensures that the business’s resources are always deployed in their highest and best use.
Managing Debt as a Strategic Lever
While many small business owners fear debt, a good business uses it as a strategic tool. The key is distinguishing between “consumptive debt” and “productive debt.” Consumptive debt is used to cover operational losses or lifestyle expenses; this is a path to insolvency. Productive debt, such as a low-interest loan to purchase an asset that generates high-margin revenue, can accelerate growth.
Using leverage allows a business to increase its Return on Equity (ROE). However, a well-run business never over-leverages. The Debt-to-EBITDA ratio should remain at a level where the business can comfortably service its interest payments even if revenue drops by 20% or 30%. Financial prudence in good times creates the capacity for strategic borrowing in times of expansion.
Analyzing Unit Economics for Scalability
A business that is small and profitable is not necessarily a “good” business if it cannot scale. Scaling requires that the underlying unit economics—the financial performance of a single customer or a single transaction—remain healthy as the volume increases.
The LTV to CAC Ratio: The Ultimate Growth Metric
In the modern business landscape, the relationship between Lifetime Value (LTV) and Customer Acquisition Cost (CAC) is the ultimate indicator of business quality. A good business aims for an LTV:CAC ratio of at least 3:1. This means that for every dollar spent on marketing and sales to acquire a customer, the business expects to earn three dollars in gross profit over that customer’s lifespan.
If the CAC is too high, the business is “buying” its revenue at a loss, which is unsustainable. If the LTV is too low, the business is a “leaky bucket,” losing customers before it can recoup the cost of acquiring them. Running a good business involves constant experimentation to lower acquisition costs while simultaneously increasing customer retention and upsell opportunities to drive LTV higher.
Protecting Profit Margins in a Competitive Market
Revenue is often a vanity metric; margins are the reality. A $10 million business with a 5% net margin is significantly more fragile than a $2 million business with a 35% net margin. A good business focuses on protecting its gross and operating margins through operational efficiency and pricing power.
Operational efficiency isn’t just about cutting costs; it’s about eliminating “waste” in the value chain. This might involve automating repetitive financial tasks, renegotiating bulk contracts, or utilizing software to track labor productivity. Pricing power, on the other hand, comes from brand equity and the perceived value of the offering. A business that can raise its prices by 5% without losing customers has a “moat” that protects its bottom line from inflation and rising supply costs.
Financial Governance and Risk Mitigation
As a business grows, the complexity of its financial operations increases. Running a good business requires moving away from informal “shoebox” accounting toward rigorous financial governance and proactive risk management.
Implementing Robust Internal Controls
Financial integrity is the bedrock of a good business. This means implementing internal controls to prevent fraud, errors, and mismanagement. Segregation of duties—ensuring that the person who approves an invoice is not the same person who signs the check—is a fundamental practice.
Regular financial audits, even if not required by law, provide a “health check” for the company. These audits ensure that the books are accurate, which is essential for making informed decisions. Furthermore, clear financial reporting allows the business owner to see trends before they become crises. A monthly “dashboard” of Key Performance Indicators (KPIs) such as the current ratio, burn rate, and accounts receivable aging should be reviewed religiously.
Hedging Against Macroeconomic Instability
A good business does not operate in a vacuum. It is subject to interest rate fluctuations, currency risks, and changes in tax law. Part of running a high-level business is identifying these external financial risks and mitigating them.
This might involve “fixing” interest rates on variable-rate debt when rates are low, or using forward contracts to hedge against currency volatility if the business deals with international suppliers. Tax planning is also a critical component of risk mitigation. By working with tax professionals to utilize legal incentives, R&D credits, and efficient corporate structures, a business can significantly increase its after-tax cash flow, providing more capital for reinvestment.
Maximizing Enterprise Value for Long-Term Success
The ultimate test of a good business is its “Enterprise Value”—what the business would be worth if it were sold today. Even if the owner has no intention of selling, running the business as if it were always “for sale” ensures that it remains organized, profitable, and efficient.
Improving Quality of Earnings
Investors and buyers look for “Quality of Earnings.” This refers to how much of the reported profit is actually repeatable and cash-based. A business with high quality of earnings has recurring revenue (subscriptions or contracts) rather than one-off sales. It has a diversified customer base, meaning no single client accounts for more than 10-15% of total revenue.
A good business focuses on building these “valuation drivers.” By shifting from a transactional model to a relationship or subscription model, a business owner can dramatically increase the multiple at which the business is valued. Recurring revenue provides a “floor” for the business’s valuation and makes financial forecasting significantly more accurate.
Preparing for a Future Exit or Acquisition
A business that is dependent on the owner for its daily operations is not a “good” business; it is a high-paying job. To build enterprise value, the business must be an asset that can function independently of its founder. This requires investing in a professional management team and documented systems.
From a financial perspective, this means having “clean” financials. Personal expenses should never be mixed with business accounts. There should be a clear trail of contracts, intellectual property filings, and tax compliance. When a business is run with this level of financial transparency and professional rigor, it becomes an attractive target for acquisition or an ideal candidate for transition to the next generation of leadership.
In conclusion, running a good business is a continuous exercise in financial stewardship. It requires a balance between aggressive growth and defensive stability. By focusing on cash flow velocity, disciplined capital allocation, healthy unit economics, and robust governance, an entrepreneur can transform a simple operation into a high-value, sustainable financial engine. Success is not found in the “big win,” but in the hundreds of small, sound financial decisions made every single day.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.