
The American Express Platinum Card occupies a unique position in the landscape of personal finance. It is frequently cited not just as a payment method, but as a lifestyle ecosystem and a marker of financial stability. Unlike traditional credit cards, the Platinum Card was historically structured as a charge card—meaning the balance is expected to be paid in full each month—though modern iterations offer “Pay Over Time” features. Because of its premium nature, high annual fee, and the significant perks it offers, the qualification process is more rigorous than that of a standard entry-level card.
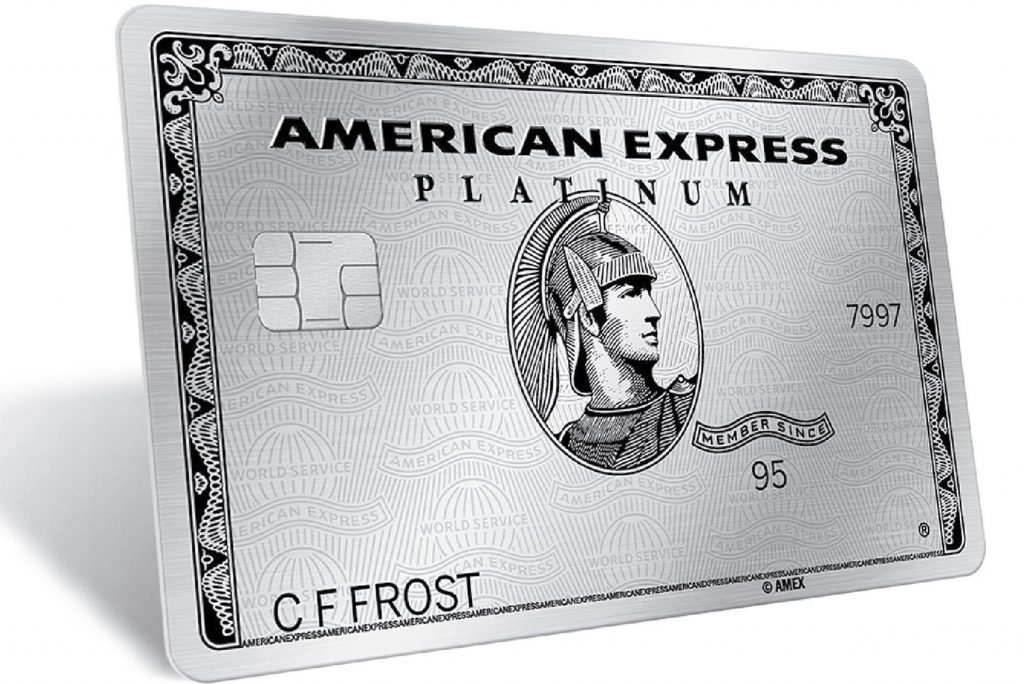
Qualifying for this card requires a strategic alignment of creditworthiness, income transparency, and a demonstrated history of responsible financial management. For high-achieving individuals and those looking to optimize their travel and lifestyle spending, understanding the nuances of the American Express approval algorithm is the first step toward securing this metal card.
The Financial Benchmarks: Credit Scores and History
The primary gateway to any premium financial product is the credit profile. American Express does not publicly disclose a “hard minimum” credit score for the Platinum Card, but historical data and industry trends suggest a clear threshold for success.
The Ideal Credit Score Range
Generally, an applicant should possess a “Good” to “Excellent” FICO score to be considered a viable candidate. While some individuals have reported approvals with scores in the high 600s, the safest margin for approval typically begins at 700. For those seeking a near-guaranteed approval (provided other factors are in order), a score of 740 or higher puts the applicant in the strongest possible position.
American Express primarily pulls data from Experian, though they may occasionally check TransUnion or Equifax depending on the applicant’s geographic location. It is essential to ensure that your credit report is free of recent delinquencies, bankruptcies, or significant late payments. A single “30-day late” in the last twelve months can be a significant red flag for a premium issuer that prides itself on the reliability of its member base.
Depth and Breadth of Credit History
A high score alone is sometimes insufficient if the credit file is “thin.” American Express looks for a history of managing multiple types of credit over several years. If you have a 750 score but only one year of credit history with a single $500 limit card, the issuer may view you as an unproven risk for a card that has “No Preset Spending Limit.”
The ideal candidate has at least two to three years of clean credit history and experience with revolving credit lines that have substantial limits. If you have successfully managed a credit card with a $5,000 or $10,000 limit, it signals to American Express that you are prepared for the higher spending capacity associated with the Platinum tier.
Managing the Debt-to-Income Ratio
Your Debt-to-Income (DTI) ratio is a critical component of the “Money” aspect of your application. This ratio compares your monthly debt obligations (rent/mortgage, car loans, student loans, minimum credit card payments) against your gross monthly income. Even a high-income earner may be rejected if their monthly obligations consume too high a percentage of their earnings. Keeping your revolving credit utilization below 10% across all cards before applying can provide a temporary boost to your score and demonstrate that you are not “credit hungry.”
Income Requirements and the Definition of Ability to Pay
While the Platinum Card is often associated with high-net-worth individuals, the actual income requirement is more flexible than many realize. However, transparency and the ability to justify your spending are paramount.
Disclosing Total Annual Income
When applying for the Platinum Card, American Express asks for your total annual income. It is important to remember that for individuals over the age of 21, “income” can include more than just a base salary. You may legally include:
-
Bonuses and commissions.
-
Investment dividends and interest.
-
Rental property income.
-
Retirement benefits or social security.
-
Spousal or partner income, provided you have a “reasonable expectation of access” to those funds for the purpose of paying bills.
While there is no official income floor, an annual income of $50,000 to $60,000 is often cited as the baseline for a successful application, though higher amounts significantly improve the odds and the subsequent “Pay Over Time” limit assigned to the account.
The Role of Financial Reserves
American Express occasionally utilizes “Financial Review” processes for both new and existing members. If your spending patterns suddenly spike or if your income disclosure seems inconsistent with your profession, they may request tax returns (Form 4506-C) to verify your earnings. Maintaining a healthy relationship with liquidity—having savings or brokerage accounts that can be verified if necessary—adds a layer of security to your financial profile that premium issuers value.
Navigating the American Express Ecosystem
American Express values loyalty and existing relationships. If you are already within the Amex ecosystem, the path to the Platinum Card is often smoother.
The “Apply with Confidence” Feature
One of the most significant shifts in the application process is the “Apply with Confidence” tool. This allows prospective members to find out if they are approved for the card with a “soft” credit pull, which does not impact their credit score. A “hard” pull only occurs if the applicant is approved and chooses to accept the card. This feature is invaluable for those who are on the fence regarding their qualification status, as it removes the risk of a wasted hard inquiry.
Existing Cardmember Advantage
If you already hold a lower-tier American Express card, such as the Gold or Green card, or even a co-branded card like the Delta SkyMiles or Hilton Honors cards, Amex has internal data on your spending and payment habits. If you have been a member in good standing for at least six months to a year, you may find “pre-approved” offers in your online portal. In many cases, existing members can add a Platinum Card to their wallet without an additional hard inquiry on their credit report at all, as Amex relies on their internal monthly snapshots of your credit profile.
The “Once Per Lifetime” Rule and Strategic Timing
In the world of personal finance, timing is everything. American Express typically has a “once per lifetime” rule regarding the introductory “Welcome Offer” (the bonus points earned after meeting a spending requirement). To truly qualify for the value of the card, you should apply when the welcome offer is at an all-time high—often ranging from 80,000 to 150,000 Membership Rewards points. Furthermore, be aware of the “1 in 5” and “2 in 90” rules: generally, Amex will only approve one card in a 5-day period and no more than two cards in a 90-day period.
Optimizing Your Profile for Approval
If you do not currently meet the criteria, there are several tactical financial moves you can make to “groom” your profile for a successful application in three to six months.
The Authorized User Strategy
If your credit history is short, being added as an authorized user on another person’s American Express Platinum or Gold account can be beneficial. While this doesn’t guarantee your own approval, it begins your relationship with the brand and can help build the “age” of your credit file, provided the primary account holder has a perfect payment history.
Strategic Credit Limit Increases
Requesting credit limit increases on your existing cards (with other issuers) can lower your overall utilization ratio. Lower utilization signals to American Express that you are not under financial stress and that you use credit as a tool rather than a crutch. Aim to keep your utilization under 5% in the two months leading up to your Platinum application.
Audit Your Credit Report
Before applying, pull your free annual credit reports from all three bureaus. Look for “zombie” debts, incorrect addresses, or misreported late payments. Disputing and removing even one minor error can result in a 20-to-30-point swing in your score, which could be the difference between an automated rejection and an immediate approval.

Maintaining Qualification: The Charge Card Discipline
Qualifying for the Platinum American Express is only the first half of the journey; maintaining the account requires a specific type of financial discipline. Because the card is designed to be paid in full, it demands a high level of cash flow management.
The Platinum Card is a tool for those who treat their personal finances with the rigor of a business. The $695 annual fee (as of current market rates) must be justified through the utilization of its various credits—digital entertainment, hotel credits, airline fee statements, and lounge access. To truly “qualify” in a practical sense, an individual should have a lifestyle where these expenditures are already occurring.
Using the card responsibly—paying on time, every time, and not over-leveraging the “Pay Over Time” feature—ensures that your internal “Internal Credit Score” with American Express remains high. This internal score is what allows for the “No Preset Spending Limit” to grow, sometimes allowing for six-figure individual purchases that would be impossible on a standard credit card. By mastering these financial pillars, the Platinum American Express transitions from a goal to a powerful asset in one’s broader financial portfolio.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.