
In the modern financial landscape, your debit card is more than just a piece of plastic; it is the primary gateway to your liquid assets and a critical tool for daily money management. Chase, as one of the largest financial institutions in the world, provides a robust infrastructure for managing these tools, but navigating the replacement process requires an understanding of both the technical steps and the security implications. Whether your card has been compromised, damaged, or simply reached its expiration date, knowing how to efficiently order a replacement is essential for maintaining your financial momentum.
The Strategic Process of Replacing Your Chase Debit Card
When you realize you need a new debit card, the first step is determining the reason for the replacement. This distinction is vital because it dictates how Chase handles your account security. If your card is physically damaged, the bank will typically issue a new card with the same account number. However, if the card is lost or stolen, Chase must issue a completely new card number to prevent unauthorized access to your funds.
Ordering via the Chase Mobile App
For most consumers, the mobile app is the most efficient way to handle banking tasks. To order a new card through the app, follow these steps:
-
Log in to your Chase Mobile app using your biometric data or credentials.
-
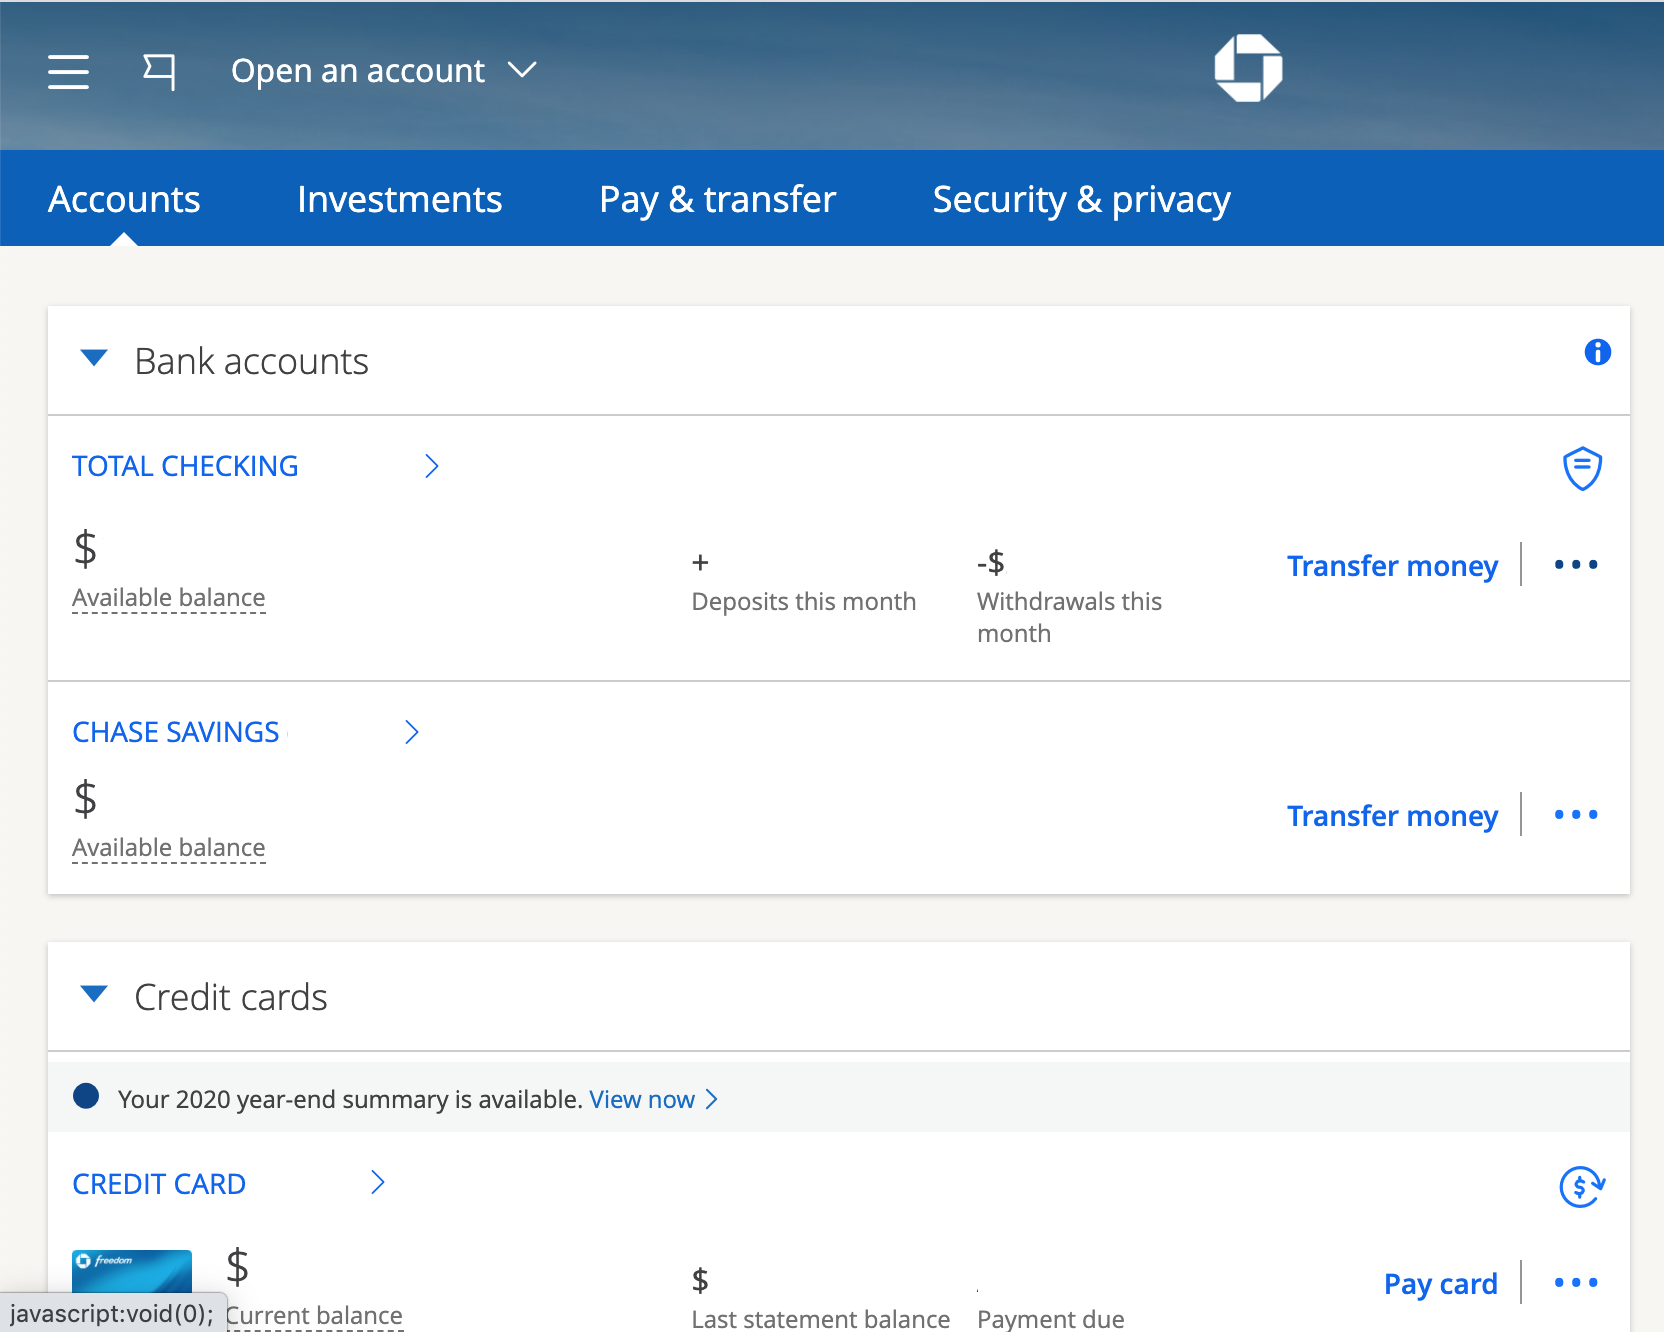
Select the specific checking account associated with the card you need to replace.
-
Scroll down to the “Account services” section and tap on “Replace a card.”
-
Choose the reason for the replacement (e.g., damaged, lost, or stolen).
-
Review your mailing address to ensure the card arrives at the correct location.
-
Select your preferred shipping method and submit the request.
Utilizing Chase Online Banking
If you prefer a desktop interface, the Chase website offers a similar, streamlined experience. After logging into your profile, navigate to the “Open menu” (the three horizontal lines) and select “Protect & report.” From there, you can choose “Report lost or stolen card” or “Replace a damaged card.” The online portal often provides more detailed information regarding the status of your current cards and allows you to manage multiple accounts simultaneously, making it a preferred choice for business owners or those with complex personal finance structures.
In-Person and Phone Support
While digital methods are faster, there are instances where speaking to a professional is beneficial. If you have concerns about fraudulent activity that goes beyond a single lost card, visiting a local Chase branch allows you to speak with a personal banker. They can often provide a temporary card on the spot in some locations, which is an invaluable service if you are traveling or have immediate expenses. Alternatively, calling the customer service number on the back of your statement provides a direct line to the security department for immediate card cancellation.
Security Protocols and Financial Safeguards
The moment you realize your debit card is missing, your priority shifts from convenience to security. In the realm of personal finance, the speed of your response is the greatest factor in limiting liability. Chase offers several high-tech features designed to protect your capital during the transition period between your old card and your new one.
The Power of the “Freeze” Feature
Before you even order a new card, you should utilize the “Freeze” function available in the Chase app. Freezing your card is a temporary measure that prevents new purchases or ATM withdrawals from being processed. This is particularly useful if you have misplaced your card in your home and believe you might find it. If you do find it, you can “Unfreeze” it instantly. If you determine it is truly gone, you can proceed with the replacement order while the card remains frozen, ensuring no one else can use it in the interim.
Transitioning to Digital Wallets
One of the most significant advancements in modern banking is the ability to use a new card before the physical plastic arrives in the mail. Once you request a replacement card through Chase, you can often add the new card details to your digital wallet (Apple Pay, Google Pay, or Samsung Pay) immediately via the app. This allows you to continue making point-of-sale purchases using your smartphone’s NFC technology. This continuity is vital for maintaining your budget and ensuring that your daily financial life is not disrupted by a shipping delay.
Monitoring for Fraudulent Activity
During the window of replacement, it is your responsibility to monitor your “Pending” transactions closely. Check for small, “test” transactions that hackers often use to verify if a card is active. If you see any activity you do not recognize, report it to Chase immediately. Their $0 Liability Protection is a cornerstone of their service, but it relies on timely reporting from the account holder to be most effective.
Understanding Timelines, Fees, and Shipping Logistics
In personal finance, time is often equated with money. Understanding the logistics of how your new card reaches you can help you plan your cash flow and spending accordingly.
Standard vs. Expedited Shipping
Chase typically offers standard shipping for free, which usually takes 5 to 7 business days. However, if you are in a situation where you cannot rely on digital wallets—such as traveling to an area where NFC payments are not widely accepted—you may want to opt for expedited shipping. Expedited shipping often carries a fee (usually around $5), but it can get the card to your door in 1 to 2 business days. For premium account holders, such as those with Chase Sapphire or Private Client status, these fees are frequently waived as part of the account’s value proposition.
Activation Procedures
Once your new card arrives, it will come in a discreet envelope for security purposes. You must activate the card before it can be used. This can be done in three ways:
-
Online/App: Entering the card details and CVV code into the secure portal.
-
ATM: Inserting the card and entering your existing PIN (if the card number remained the same) or setting a new one.
-
Phone: Calling the activation number provided on the sticker affixed to the card.
Updating Recurring Payments
A common oversight in the replacement process is the failure to update recurring bills. If your card number has changed, your Netflix subscription, gym membership, and utility auto-pays will fail. Take an hour to list your recurring monthly expenses and update the payment information as soon as your new card is activated. Some merchants use a “billing updater” service that automatically receives your new card info from Chase, but you should never rely on this exclusively.
Maximizing the Value of Your Chase Banking Experience
Ordering a new debit card is an opportune time to evaluate whether your current checking account still aligns with your financial goals. Chase offers a variety of account tiers, each with different benefits regarding card replacements and fees.
Account Tier Comparisons
-
Chase Total Checking: The standard account for most consumers. It provides all the essential tools for card replacement but may charge for expedited shipping.
-
Chase Premier Plus Checking: Offers more perks, including waived fees for some money orders and cashier’s checks, and often provides better support for card issues.
-
Chase Sapphire Banking: Geared towards higher-balance clients, this tier offers no-fee ATM withdrawals worldwide and premier protection features.
Leveraging Financial Tools
While waiting for your card, take advantage of the “Insights” tool within the Chase app. This feature categorizes your spending and provides a holistic view of your financial health. Use this period of “manual” spending (since you might be more conscious of your transactions without a physical card) to recalibrate your budget. Many users find that the temporary inconvenience of a lost card leads to a deeper dive into their transaction history, revealing unnecessary subscriptions or spending habits that can be optimized.
Conclusion: The Lifecycle of Financial Management
The process of ordering a new debit card from Chase is a microcosm of effective personal finance: it requires a blend of technological savvy, proactive security measures, and organized planning. By leveraging the mobile app for quick requests, utilizing the freeze feature for security, and immediately integrating the new card into a digital wallet, you transform a potential financial headache into a seamless transition.
Remember that your debit card is the primary link between your labor and your lifestyle. Treating the replacement process with the professional attention it deserves ensures that your assets remain secure and your purchasing power remains uninterrupted. In a world that is increasingly moving toward a cashless society, the ability to manage your digital and physical access points to your money is one of the most important skills you can maintain.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.