
The digital finance landscape has revolutionized how individuals and businesses manage their money, with platforms like Cash App leading the charge in simplifying transactions. While the ease of use is a major draw, the need often arises for users to manage their finances with a greater degree of separation and specificity. This frequently leads to the question of how one might create and effectively utilize multiple Cash App accounts. The aspiration isn’t merely about having another digital wallet; it’s about strategic financial management, robust budgeting, and clear segregation of funds for different purposes.
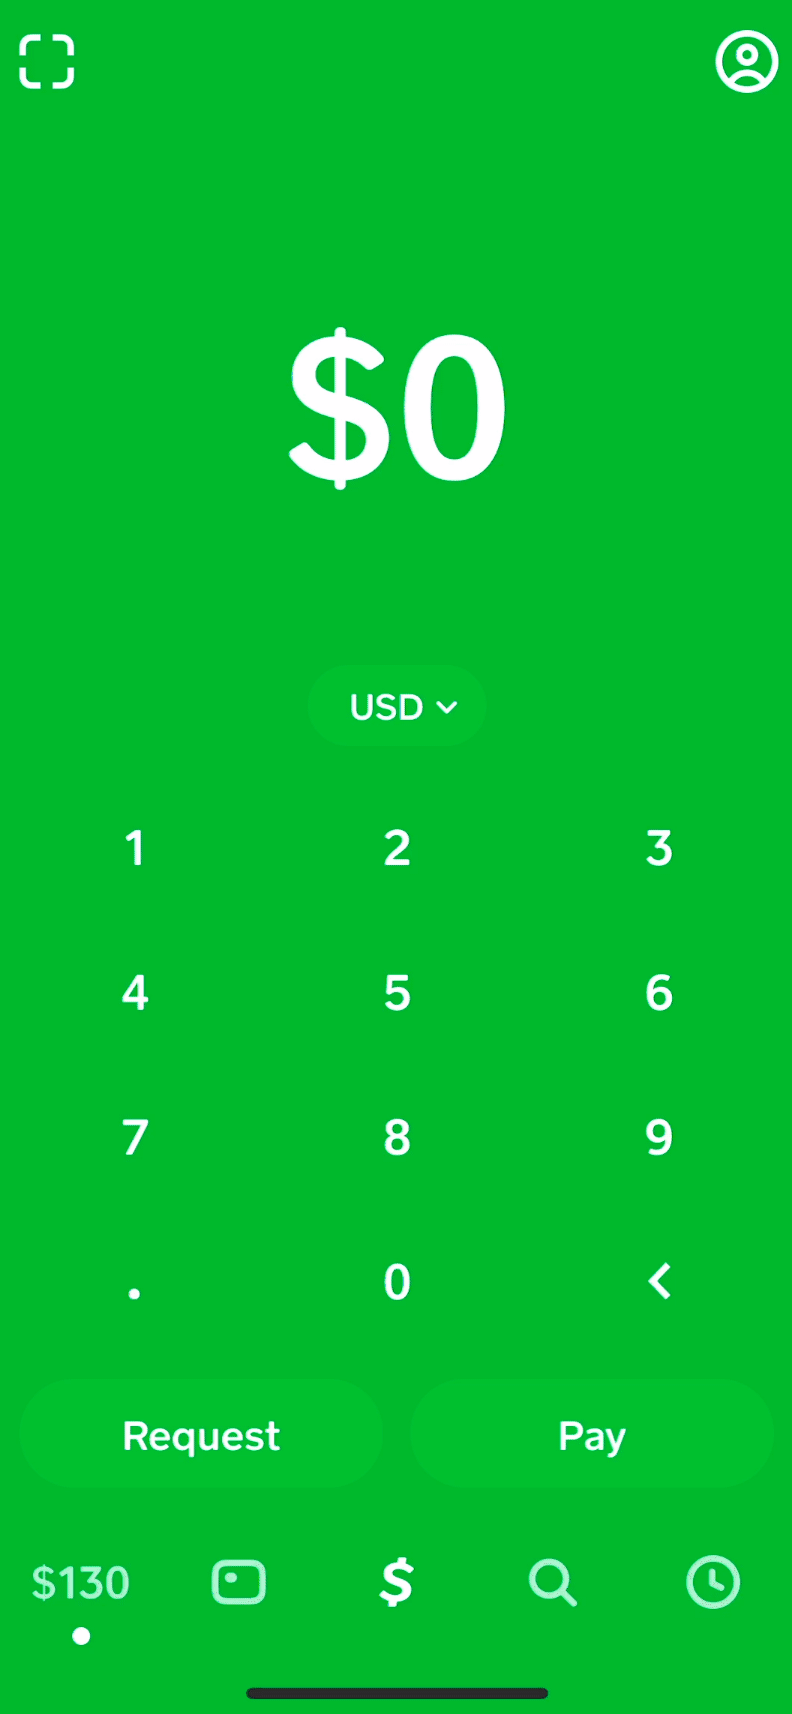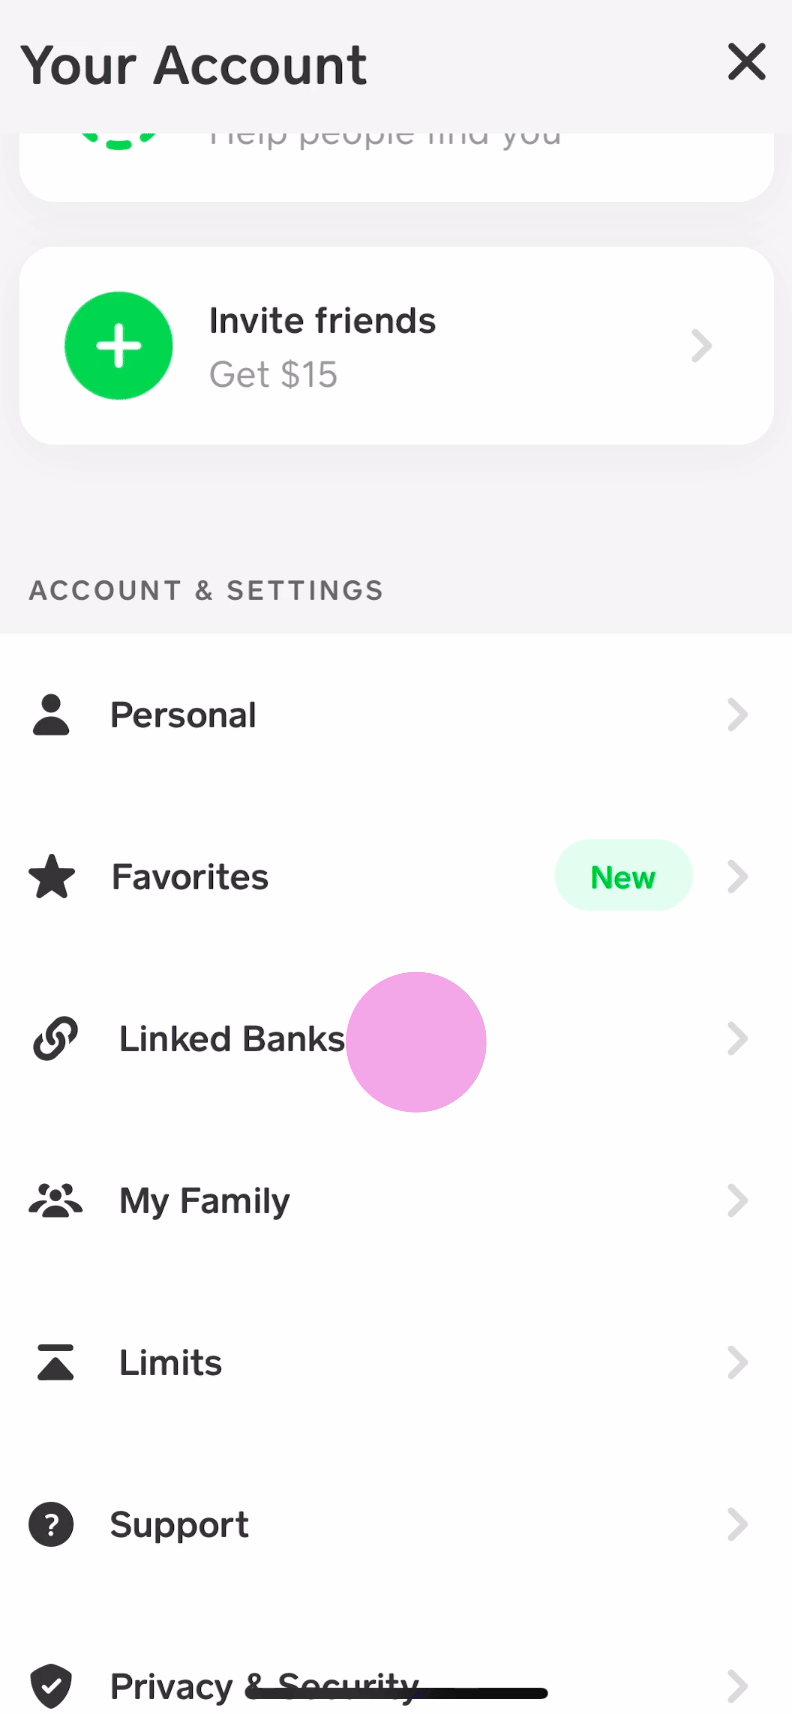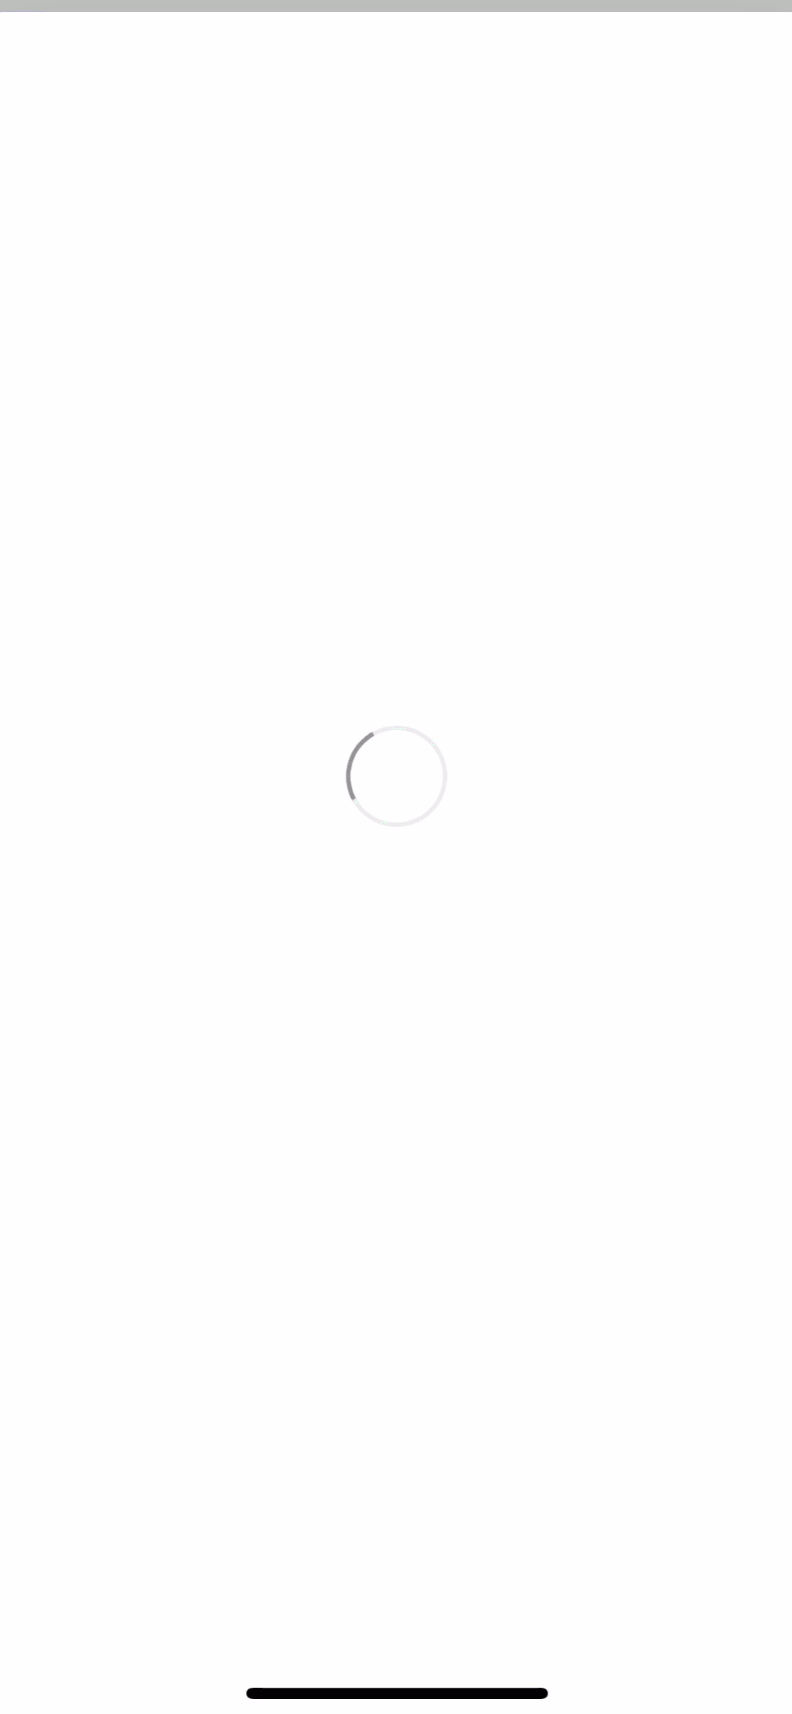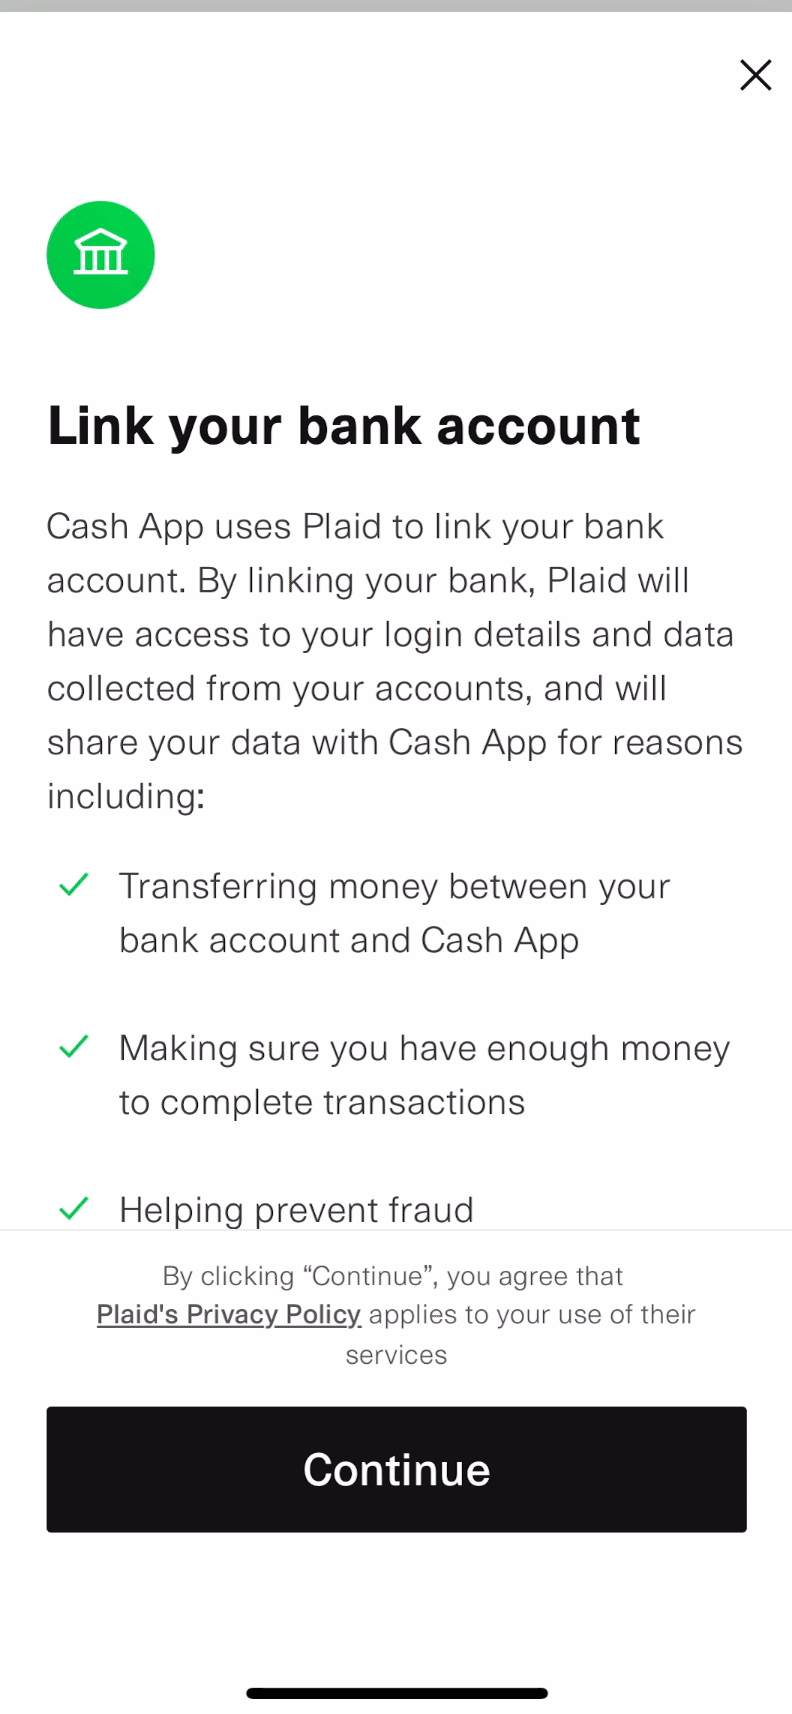
Understanding the Need for Multiple Cash App Accounts
The decision to establish an additional Cash App account typically stems from a well-defined financial strategy aimed at enhancing organization, control, and sometimes, compliance. For many, a single financial portal, while convenient, can become a bottleneck when diverse income streams or spending categories need distinct handling.
Segregating Personal and Business Finances
One of the most compelling reasons to consider a second Cash App account is the imperative to separate personal spending from business operations. For entrepreneurs, freelancers, or small business owners, commingling funds can lead to a labyrinthine mess at tax time, obscure the true financial health of a venture, and complicate expense tracking. A dedicated business Cash App account allows for clear delineation of income generated from sales, services, or contractual work, alongside dedicated tracking of business-related expenditures. This separation is not just a matter of convenience; it’s a critical best practice for financial accountability, audit readiness, and accurate profit analysis. It supports a professional approach to business management, enabling better insights into cash flow and operational costs, which are vital for sustainable growth.
Managing Multiple Income Streams or Side Hustles
The modern economy often encourages individuals to cultivate multiple sources of income, whether through gig work, online sales, or various side hustles. Each of these ventures might have its own rhythm of income and expenditure, and lumping them all into a single personal account can quickly become overwhelming. Creating distinct Cash App accounts for each significant side hustle or income stream provides an elegant solution. For instance, a user might have one account for their primary employment direct deposits and everyday spending, another for income and expenses related to their online art sales, and yet another for earnings from ride-sharing or delivery services. This strategy not only simplifies the tracking of profitability for each endeavor but also aids in allocating funds back into specific business growth or savings goals related to that income source.
Budgeting and Financial Separation
Beyond business needs, multiple accounts can serve as powerful tools for personal budgeting and financial goal achievement. By assigning different Cash App accounts to distinct budgetary categories or savings objectives, users can enforce stricter discipline over their spending and saving habits. For example, one account could be designated for essential household expenses, another for discretionary spending, and a third for a specific savings goal, like a down payment or vacation fund. This “envelope system” approach, adapted for digital platforms, helps prevent overspending in one category by visually and practically separating funds. It fosters a more mindful approach to money management, where funds are allocated and consumed with purpose, reducing the temptation to dip into funds earmarked for other critical objectives.
Privacy and Security Considerations for Specific Transactions
In certain scenarios, individuals may seek an additional Cash App account for enhanced privacy or security surrounding specific types of transactions. While Cash App is generally secure, having a separate account for transactions with less familiar parties or for highly sensitive payments can add an extra layer of comfort. This might involve using a dedicated account for online purchases from new vendors, managing shared expenses within a specific group, or handling contributions to a joint venture without fully exposing one’s primary financial details. The rationale here is to compartmentalize potential risks; if one account were ever compromised, the exposure to other, more critical funds would be limited, thereby containing any potential damage.
The Practicalities of Setting Up a Secondary Account
Successfully establishing an additional Cash App account requires a clear understanding of the platform’s operational rules and an appreciation for the financial implications of managing multiple digital identities. Cash App, like most regulated financial tools, operates under strict guidelines designed to prevent fraud and ensure compliance with financial regulations.
The “One Account Per Phone Number/Email” Rule
Fundamentally, Cash App is designed around the principle of “one unique identifier per account.” This means that each Cash App account must be linked to a distinct mobile phone number and a unique email address. This is a critical barrier for users attempting to create a second account using their existing credentials. To circumvent this, an individual needs access to a different phone number (which could be a secondary personal phone, a business line, or even a virtual number service, though the latter might have compatibility issues) and a different email address. This requirement underscores Cash App’s commitment to user authentication and account security, ensuring each account is independently verifiable. It’s crucial to maintain access to these unique identifiers, as they are essential for account recovery, password resets, and two-factor authentication.
Utilizing Distinct Identities for Multiple Accounts
For individuals, creating a truly separate Cash App account under their own name is generally not supported if they have already verified their primary account with their Social Security Number (SSN). Cash App’s Know Your Customer (KYC) protocols are designed to link an individual’s verified identity to a single primary account to comply with financial regulations. Therefore, the most straightforward and compliant path to a “second” Cash App account often involves creating an account for a legitimate, separate entity—such as a registered small business or sole proprietorship that has its own Employer Identification Number (EIN) or operates under a distinct legal structure. In this scenario, the business itself would be the account holder, with the individual acting as an authorized user. This requires the business to be legally recognized, allowing it to satisfy Cash App’s verification requirements independently of the individual’s personal account.
Navigating Identification Requirements for Account Verification
When setting up any Cash App account, whether personal or business, full functionality typically requires identity verification. This involves providing personal details such as full name, date of birth, mailing address, and the last four digits of your SSN, or for a business account, an EIN. For a second personal account under the same individual’s identity, this is where the system flags duplicate verification attempts. However, for a legitimate business account, the verification process will pertain to the business entity itself. It’s imperative that all submitted information is accurate and verifiable to ensure the account is fully functional and not subject to limitations or closure. Misrepresenting identity or business status can lead to permanent account restrictions, loss of funds, and potential legal repercussions.
Linking Unique Bank Accounts and Debit Cards

Just as with phone numbers and emails, each Cash App account needs to be linked to unique external financial instruments. This means a separate bank account and/or debit card that has not been previously linked to another Cash App account. For individuals with multiple bank accounts (e.g., a personal checking account and a business checking account), this is feasible. For a business account, it is critical to link it exclusively to the business’s bank account to maintain the financial separation crucial for accurate accounting and tax purposes. Attempting to link the same personal bank account or debit card to multiple Cash App profiles will likely result in error messages or account limitations, as the system is designed to prevent such overlaps to maintain financial integrity and security.
Best Practices for Managing Multiple Cash App Accounts
Operating multiple Cash App accounts, while offering significant financial benefits, also introduces a layer of complexity that necessitates diligent management. Adopting a structured approach ensures that the benefits of segregation are fully realized without introducing undue risk or confusion.
Clear Documentation and Record-Keeping
The cornerstone of effective multi-account management is meticulous record-keeping. Each Cash App account should be treated as a distinct financial entity, complete with its own records of transactions, transfers, and balances. This includes maintaining digital or physical ledgers, categorizing expenses, and reconciling statements regularly. For business accounts, this aligns directly with accounting principles, facilitating accurate profit and loss statements and balance sheets. For personal budgeting accounts, it helps track spending against allocated budgets, preventing financial leakage and ensuring goals are met. Consistent documentation not only provides a clear financial picture but is also invaluable during tax preparation or in the event of a dispute or audit. Utilizing spreadsheets, dedicated accounting software, or even specific budgeting apps that can integrate with multiple financial sources can greatly streamline this process.
Strategic Allocation of Funds
Having multiple accounts allows for a highly strategic approach to fund allocation. Instead of a single pool of money, funds can be deliberately channeled to specific accounts based on their intended purpose. For instance, upon receiving payment for a side hustle, a portion could be immediately transferred to a dedicated tax savings account, another to an emergency fund, and the remainder allocated for operational expenses within that side hustle’s specific Cash App account. This proactive allocation prevents funds from being inadvertently spent on other categories and ensures that money is working towards its designated objective. It requires foresight and a disciplined approach to transferring funds efficiently between accounts, always aligning with pre-defined financial goals and budgets.
Understanding Tax Implications for Each Account Type
The tax implications of managing multiple Cash App accounts can be significant, especially when some accounts are used for business or income-generating activities. Income received through Cash App for goods or services is typically taxable, and users are responsible for reporting these earnings to the relevant tax authorities. Cash App may issue Form 1099-K to users who receive over a certain threshold in payments for goods and services, but even below this threshold, income is still taxable. With multiple accounts, it becomes even more crucial to understand which income streams are subject to which tax rules. Segregating business income and expenses into a dedicated account simplifies the preparation of Schedule C (for sole proprietors) or other relevant business tax forms. Consulting with a tax professional is highly recommended to ensure compliance and optimize tax strategies when operating multiple income-generating accounts.
Regular Review and Reconciliation
Periodically reviewing and reconciling each Cash App account is essential for maintaining accuracy and detecting discrepancies. This involves comparing transaction histories with personal records, ensuring all payments sent and received are correctly recorded, and verifying account balances. Regular reconciliation, perhaps weekly or monthly, helps in quickly identifying unauthorized transactions, errors, or forgotten expenses. It also provides an opportunity to assess the effectiveness of current budgeting strategies and make necessary adjustments. This proactive oversight is a fundamental aspect of sound financial hygiene and is critical for both personal financial security and business solvency. It transforms passive financial management into an active, informed process that empowers the user with greater control and insight.
Mitigating Risks and Ensuring Financial Security
While the strategic benefits of multiple Cash App accounts are clear, their management inherently introduces new security considerations. Ensuring the safety of funds and personal information across these accounts requires a heightened level of vigilance and adherence to robust security practices, extending beyond just the application itself.
Robust Password Practices and Two-Factor Authentication
The first line of defense for any digital financial tool is strong authentication. For each Cash App account, it is imperative to use a unique, complex password that combines letters, numbers, and symbols, and to avoid easily guessable combinations. Reusing passwords across different accounts is a critical vulnerability. Beyond strong passwords, enabling Two-Factor Authentication (2FA) for every Cash App account is non-negotiable. 2FA adds an extra layer of security by requiring a second form of verification—such as a code sent to the linked phone number or email—in addition to the password. This significantly reduces the risk of unauthorized access, even if a password is compromised. Regularly updating passwords and reviewing 2FA settings for all accounts should be a routine security habit.
Vigilance Against Scams and Fraud
The proliferation of digital payment apps has unfortunately also led to an increase in phishing attempts, social engineering scams, and other fraudulent activities. Managing multiple Cash App accounts requires an enhanced awareness of these threats. Users must be wary of unsolicited requests for money, suspicious links in emails or messages, and individuals impersonating Cash App support. Never share passwords, 2FA codes, or sensitive account information with anyone, regardless of how convincing they may seem. Cross-verify payment requests with the sender through an alternative, trusted communication channel before authorizing any transaction. Since each account may have different contacts or transaction patterns, maintaining a consistent level of skepticism across all accounts is paramount to avoiding financial loss.
Understanding Cash App’s Terms of Service and Limitations
Operating multiple accounts means a deeper responsibility to understand and adhere to Cash App’s Terms of Service (ToS). Violations of the ToS, such as misrepresenting identity, using the platform for prohibited activities, or engaging in fraudulent behavior, can lead to severe consequences, including account suspension or permanent closure, and the potential forfeiture of funds. It’s crucial to be aware of transaction limits, daily sending/receiving caps, and any restrictions on specific types of transactions that might apply to different account verification levels. Understanding these limitations helps in planning financial operations effectively and prevents unexpected disruptions in service. Ignorance of the ToS is not a defense and can jeopardize access to all managed accounts.

When to Consider Alternative Financial Tools
While Cash App offers immense convenience, it may not always be the most suitable tool for every financial scenario, especially when dealing with complex business operations, large transaction volumes, or highly specialized financial needs. For certain business structures or substantial financial flows, traditional banking services, dedicated business payment processors, or more feature-rich accounting software might offer greater security, robust reporting, and better integration with broader financial ecosystems. If managing multiple Cash App accounts becomes overly cumbersome, difficult to reconcile with tax obligations, or encounters frequent limitations, it may be a clear indicator to evaluate whether alternative financial tools or a more sophisticated payment infrastructure would better serve the overall financial strategy. The goal is always to align the chosen financial tools with the specific demands and scale of one’s financial activities.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.