
Securing a prescription for Adipex (phentermine) is more than a medical decision; for many, it is a significant financial commitment and a strategic move toward long-term fiscal health. In the complex world of modern healthcare, “how to get Adipex” is a question that requires a deep understanding of pharmaceutical economics, insurance navigation, and the ROI of personal wellness. As healthcare costs continue to climb, consumers must treat their medical weight loss journey with the same level of due diligence they apply to their investment portfolios or real estate ventures.

This guide explores the financial mechanisms behind obtaining Adipex, from the raw cost of the medication to the intricate dance of insurance approvals and the long-term economic benefits of metabolic health.
Understanding the Cost Structure of Phentermine and Brand-Name Adipex
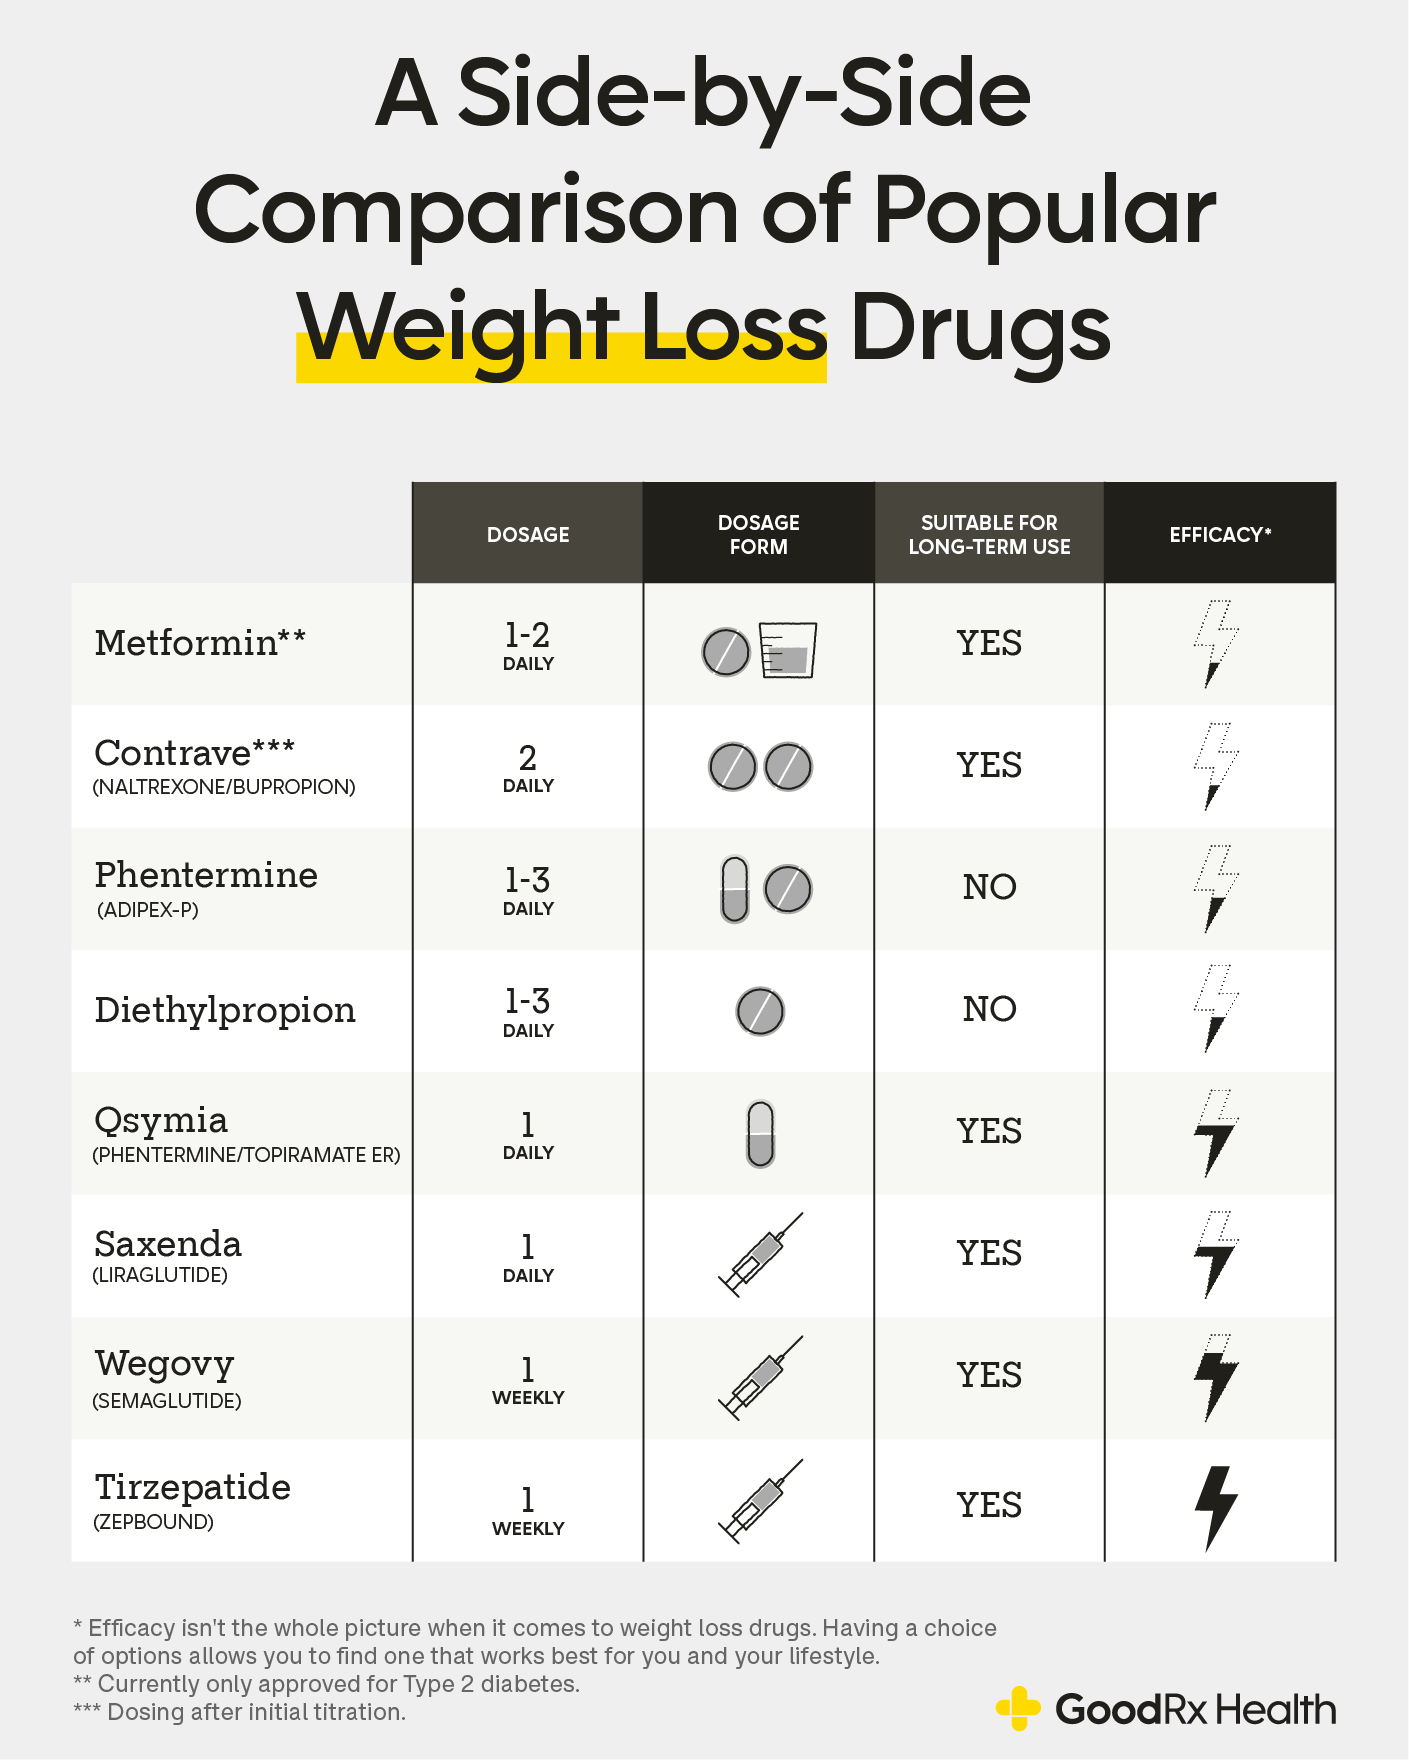
When a patient seeks to get Adipex, they are immediately met with the duality of the pharmaceutical market: the brand name versus the generic. Adipex-P is the brand name for phentermine hydrochloride, a sympathomimetic amine used as a short-term adjunct in a regimen of weight reduction. From a financial perspective, the choice between brand and generic is the first major hurdle in accessibility.
Brand vs. Generic: The Price Gap
The price discrepancy between brand-name Adipex-P and generic phentermine is substantial. Brand-name medications carry the weight of the manufacturer’s research, development, and marketing costs. For an individual paying out-of-pocket, Adipex-P can cost significantly more than its generic counterpart. Understanding this price gap is essential for budgeting. Generic phentermine is chemically equivalent and offers the same efficacy for a fraction of the price, making it the preferred choice for those without comprehensive prescription drug coverage.
Pharmacy Pricing Volatility and Comparison Shopping
The retail price of Adipex is not static across the board. Pharmaceutical pricing in the United States is notoriously opaque, with different pharmacy chains—such as CVS, Walgreens, and Costco—offering varying price points for the same dosage. Strategic consumers use comparison tools and discount programs to mitigate these costs. Utilizing digital platforms that aggregate drug prices can lead to savings of up to 80%. For those asking how to get Adipex affordably, the answer often lies in the willingness to shop around rather than simply filling the script at the nearest location.
The Hidden Costs of the Prescription Process
The cost of the pills is only one component of the total expenditure. To get Adipex legally, one must obtain a prescription from a licensed healthcare provider. This involves:
-
Initial Consultations: Specialist fees for obesity medicine or bariatric doctors often exceed those of general practitioners.
-
Diagnostic Testing: Blood work, EKG screenings, and metabolic panels are frequently required to ensure the patient is a safe candidate for a stimulant-based medication.
-
Follow-up Appointments: Because Adipex is a controlled substance (Schedule IV), it requires regular monitoring, meaning a recurring monthly or quarterly co-pay or out-of-pocket fee for doctor visits.
Navigating Insurance Coverage and Out-of-Pocket Expenses
The most significant barrier to getting Adipex is often the insurance provider. Many health insurance plans categorize weight loss medications as “cosmetic” or “lifestyle” drugs, which places them on an exclusion list. This categorization is a point of contention in healthcare finance, as it ignores the preventive value of treating obesity to avoid more expensive comorbidities.
Deciphering Prior Authorization and Medical Necessity
If a plan does cover Adipex, it usually requires a “Prior Authorization” (PA). This is a process where the insurer requires proof that the medication is medically necessary. To secure approval, your healthcare provider must document that you meet specific Body Mass Index (BMI) thresholds—typically a BMI over 30, or over 27 with a co-morbidity like hypertension or Type 2 diabetes.
From a financial strategy standpoint, winning a PA is a major victory. It shifts the burden of cost from the individual to the insurer, reducing a triple-digit monthly expense to a manageable co-pay. Understanding the specific criteria of your plan’s formulary is the key to successfully navigating this financial hurdle.
Utilizing Health Savings Accounts (HSA) and FSAs
For those whose insurance does not cover the drug, or for those with high-deductible health plans (HDHPs), Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs) are invaluable tools. Because Adipex is a prescribed medication for a diagnosed medical condition, the costs—including the medication, the doctor visits, and the lab work—are considered “qualified medical expenses.”
Using pre-tax dollars from an HSA to pay for Adipex effectively provides a 20% to 30% discount, depending on your tax bracket. This is a critical component of any financial plan for medical weight loss. By treating health as a tax-advantaged investment, patients can manage the “how to get Adipex” question with much higher financial efficiency.
The Economic ROI of Medical Weight Loss Management
While the upfront costs of getting Adipex can be daunting, the financial “Return on Investment” (ROI) of successful weight loss is profound. In financial planning, we often talk about mitigating risk. Obesity is one of the highest risk factors for long-term financial insolvency due to medical debt.
Offsetting Long-Term Healthcare Costs
The cost of treating the complications of obesity—such as cardiovascular disease, sleep apnea, and chronic joint pain—far outweighs the cost of a short-term course of Adipex. Studies in health economics consistently show that a 5% to 10% reduction in body weight can lead to a significant decrease in the lifetime cost of care. When calculating the cost of getting Adipex, one must subtract the potential future savings on insulin, blood pressure medication, and surgical interventions.
The Impact on Earning Potential and Life Insurance
There is also a direct correlation between health and earning potential. Improved energy levels and metabolic health often lead to higher productivity and fewer sick days. Furthermore, for those looking to secure life insurance or disability insurance, a lower BMI and a clean bill of metabolic health can result in significantly lower premiums. In the “Money” niche, getting Adipex is not just about weight; it is about optimizing your human capital.
Financial Strategies for Sustainable Access to Prescription Medication
If you are looking for how to get Adipex while maintaining a strict budget, several specific financial strategies can be employed. These tactics ensure that the cost of treatment does not derail other financial goals like retirement savings or debt repayment.
Manufacturer Coupons and Patient Assistance Programs
Pharmaceutical companies often offer “savings cards” or manufacturer coupons to reduce the out-of-pocket cost of brand-name drugs like Adipex-P. These cards can sometimes bring the cost down to as little as $25, even for those whose insurance refuses to cover the medication. Additionally, for individuals who meet certain income requirements, patient assistance programs (PAPs) can provide the medication for free or at a highly subsidized rate.
The Rise of Telehealth as a Cost-Effective Solution
The digital transformation of healthcare has introduced more affordable ways to get Adipex. Telehealth platforms specializing in weight management often offer “bundled” pricing. For a flat monthly fee, these services may include the medical consultation, the prescription, and sometimes even the shipping of the medication.
From a financial perspective, telehealth eliminates the “soft costs” of medical care:
-
Travel Costs: No gas or public transit fees to get to a clinic.
-
Opportunity Cost: Appointments can be done during a lunch break, eliminating the need to take time off work.
-
Transparency: Telehealth platforms are usually “cash-pay” friendly, providing clear, upfront pricing that avoids the “surprise billing” often associated with traditional hospital systems.

Budgeting for the “Post-Adipex” Phase
Adipex is designed for short-term use (usually up to 12 weeks). A sound financial plan must account for what happens after the medication period ends. The transition to maintenance usually involves a shift in spending toward high-quality nutrition, fitness memberships, or different maintenance medications. Smart financial planning involves reallocating the funds previously used for the Adipex prescription into a “wellness fund” to ensure the results—and the subsequent financial benefits—are permanent.
In conclusion, “how to get Adipex” is a multi-faceted question that sits at the intersection of medical need and financial strategy. By understanding the pricing structures, leveraging tax-advantaged accounts, navigating insurance hurdles, and viewing the medication as a high-ROI investment in human capital, individuals can manage the costs effectively. Health is the ultimate asset; managing the finances of its preservation is simply good business.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.