
For the vast majority of households, an automobile represents the second-largest financial commitment after housing. Yet, unlike real estate—which generally appreciates over time—a vehicle is a depreciating asset that requires a sophisticated understanding of market dynamics to manage effectively. Determining the value of your car is not merely a precursor to selling it; it is a vital component of personal financial planning, insurance optimization, and net worth tracking. By accurately assessing the current market worth of your vehicle, you can make informed decisions regarding trade-ins, private sales, and the timing of your next capital expenditure.

Understanding the Lifecycle of Automotive Assets
The moment a new vehicle is driven off the dealership lot, it undergoes a significant “valuation shock.” This initial drop in value is a result of the transition from a retail product to a used commodity. Understanding the mechanics of this decline is the first step in managing the financial health of your automotive investments.
The Impact of Depreciation
Depreciation is the largest single cost of owning a vehicle, often surpassing fuel, insurance, and maintenance. On average, a new car loses approximately 20% of its value within the first year and continues to decline by roughly 15% annually thereafter. For the financially savvy owner, tracking this curve is essential. By year five, most vehicles have lost 60% of their original purchase price. Determining value requires looking past the emotional attachment or the “sticker price” paid years ago and looking strictly at the residual value—the amount a willing buyer is prepared to pay in the current economic climate.
Calculating the Real Cost of Ownership
To truly understand your car’s value, you must view it through the lens of a balance sheet. This involves comparing the current market value against any outstanding debt on the vehicle. If the car’s value is higher than the loan balance, you have positive equity—a liquidable asset. If the value is lower, you are “underwater” or have negative equity. Regularly determining the value of your car allows you to adjust your insurance coverage (such as removing collision on a low-value older car) and plan for the eventual replacement of the asset without straining your cash flow.
Essential Tools and Data for Accurate Valuation
In the modern financial landscape, data is the most valuable currency. To determine what your car is worth, you must look at aggregated market data rather than anecdotal evidence or individual listing prices, which often reflect “asking” prices rather than “closing” prices.
Leveraging Industry Standard Pricing Guides
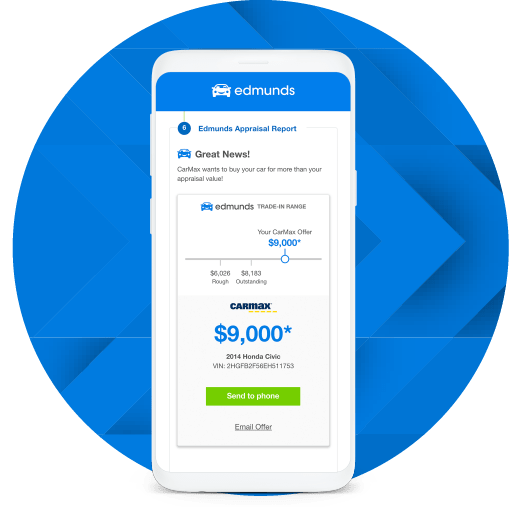
Several major financial data providers specialize in automotive valuation. Kelly Blue Book (KBB) is perhaps the most recognized, offering a proprietary algorithm that considers regional trends and historical transaction data. J.D. Power (formerly NADA) provides values based on actual transactions at the dealership level, making it a favorite for lenders and insurance companies. Finally, Consumer Reports and Black Book offer deep insights into the wholesale values that dealers use when bidding at auctions. Utilizing a combination of these tools provides a “value range” that creates a realistic expectation for your car’s worth.
The Difference Between Trade-In, Private Party, and Retail Value
When determining value, you must define the context of the potential transaction.
-
Trade-In Value: This is the wholesale price a dealer will offer. It is typically the lowest value because the dealer must factor in reconditioning costs and a profit margin for resale. However, it offers significant convenience and, in many jurisdictions, a tax advantage (where the trade-in value is deducted from the taxable price of the new car).
-
Private Party Value: This is what you can expect when selling to another individual. It is higher than trade-in value but requires more effort in terms of marketing and legal paperwork.
-
Retail Value: This is the price a consumer would pay at a dealership. While your car may be listed for this amount on a lot, you will rarely realize this full value as an individual seller because you cannot offer the financing, warranties, or certified inspections that a dealer provides.
Variables That Influence Your Car’s Market Worth
Valuation is not a static calculation; it is a nuanced assessment based on specific variables that can swing the price by thousands of dollars. As a vehicle owner, understanding these levers allows you to better time your exit from the asset.
The Mileage-to-Maintenance Correlation
Mileage is the primary metric for wear and tear. Most valuation models assume an average of 12,000 to 15,000 miles per year. If your vehicle falls significantly below this average, its financial value increases disproportionately. However, mileage alone does not tell the whole story. A documented service history is a “value multiplier.” From a financial perspective, a car with 80,000 miles and a complete folder of maintenance receipts is often worth more than a car with 60,000 miles and no service history, as the former represents a lower risk of future capital expenditure for the buyer.
Condition Grading: From Fair to Excellent
Professional appraisers use a strict grading scale: Excellent, Good, Fair, and Poor. Most owners erroneously believe their car is in “Excellent” condition. In the financial world, “Excellent” is reserved for vehicles that look and run like new, with no cosmetic flaws and perfect mechanical health. Being honest about condition is vital for an accurate valuation. A single dent or a stained interior can decrease the value by 5% to 10% because the market discounts the price by the estimated cost of restoration.
Market Demand and Seasonal Trends
External economic factors play a massive role in valuation. For example, during periods of high fuel prices, the value of large SUVs and trucks may plummet while the value of fuel-efficient hybrids and electric vehicles (EVs) rises. Furthermore, seasonality affects liquidity; convertibles often see a price surge in the spring, while all-wheel-drive vehicles command a premium in late autumn. Tracking these macro-trends ensures you aren’t selling your asset during a period of low demand.
Strategic Selling: Maximizing Your Financial Return
Once you have determined the objective value of your car, the next step is a strategic execution to capture as much of that value as possible. This is where the intersection of marketing and finance becomes critical.
The Private Sale Premium vs. Convenience Costs
From a pure ROI (Return on Investment) standpoint, selling a vehicle privately is almost always the superior choice. By cutting out the middleman (the dealership), you capture the “spread” between wholesale and retail prices. On a $20,000 vehicle, this spread can be as much as $3,000. However, the savvy investor must also account for the “cost of time.” If it takes 20 hours of labor to manage the sale, you must determine if the premium earned exceeds your personal hourly rate.
Tax Considerations and Incentives in Vehicle Transfers
In many states, the tax implications of a vehicle sale can alter the final financial outcome. When you trade in a car, you often only pay sales tax on the “difference” between the new car price and the trade-in value. For instance, if you buy a $40,000 car and trade in a $15,000 car, you only pay sales tax on $25,000. In a state with 8% sales tax, this saves you $1,200. This “tax shield” must be added to the dealer’s offer when comparing it to a potential private sale price to see which path yields the highest net benefit.
Integrating Vehicle Valuation into Your Net Worth Strategy
Successful personal finance requires a holistic view of all assets. Your car should not be a “forgotten” line item on your balance sheet until the day you decide to replace it.
Managing Auto Loan Equity
For those with financed vehicles, knowing the car’s value is essential for managing debt. If market data shows your car is depreciating faster than your loan principal is declining, you are losing net worth every month. In such cases, making extra principal payments or “gap” insurance may be necessary to protect your financial position. Conversely, if you have high equity, that car represents a potential source of emergency liquidity.
When to Liquidate the Asset
The most important financial decision regarding a car is knowing when to sell. There is a “sweet spot” in a vehicle’s life—usually between years four and six—where the rate of depreciation slows down, but major repair costs haven’t yet spiked. By monitoring the value annually, you can identify the point of diminishing returns. When the annual cost of repairs and the continued depreciation exceed the monthly cost of a newer, more reliable vehicle, it is financially prudent to liquidate the asset and reinvest the equity into a more efficient transportation solution.
Determining the value of your car is a discipline that requires objective analysis and a focus on market data. By moving away from emotional valuations and treating the vehicle as a significant component of your financial portfolio, you can minimize losses, maximize returns, and ensure that your automotive choices align with your broader wealth-building goals.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.