
In today’s dynamic financial landscape, individuals often find themselves needing to adjust their banking relationships. Whether driven by a desire for better services, changes in personal circumstances, or simply a consolidation of accounts, understanding how to close a bank account efficiently and securely is a crucial aspect of responsible personal finance. While the idea of closing a bank account might seem daunting, especially when considering the “online” aspect, PNC Bank, like many modern financial institutions, offers channels to facilitate this process. This guide provides a detailed, step-by-step approach to navigate the online closure of your PNC bank account, ensuring a smooth transition and safeguarding your financial well-being. By focusing on the financial implications, necessary precautions, and the digital tools available, we aim to empower you with the knowledge needed to manage this important financial decision with confidence and insight.

Navigating Account Closure: Why and When to Consider It
Deciding to close a bank account is rarely a snap decision; it’s often the culmination of various financial or personal shifts. Understanding the motivations behind such a move is the first step in approaching the process strategically, ensuring you make the best financial choices for your circumstances.
Common Reasons for Closing a Bank Account
There’s a multitude of valid reasons why an individual might opt to close a bank account. For many, it’s about financial consolidation, simplifying their banking by reducing the number of active accounts, thereby making it easier to track spending, manage budgets, and avoid unnecessary fees. Another frequent driver is the pursuit of better rates or services. The banking industry is highly competitive, and customers often switch to institutions offering higher interest rates on savings, lower fees, superior customer service, or more robust digital banking tools.
Life changes also play a significant role. A relocation to a new state or country might necessitate switching to a bank with a stronger local presence, or one that caters specifically to international transactions. Furthermore, dissatisfaction with current services – be it high fees, persistent technical issues, poor customer support, or a lack of desired features – can be a compelling reason to seek greener pastures. Some might also close accounts as part of a broader financial strategy, such as simplifying their financial portfolio ahead of retirement, or to eliminate an account that poses a temptation for unnecessary spending.
Pre-Closure Checklist: Essential Financial Due Diligence
Before initiating the closure process, meticulous preparation is paramount to avoid financial headaches and ensure a seamless transition. This involves a comprehensive review and proactive management of your existing financial setup.
-
Reviewing Transaction History: Go through at least the last 6-12 months of statements. Identify all recurring direct deposits (e.g., payroll, government benefits) and automatic payments (e.g., utility bills, loan payments, subscriptions, insurance premiums). Make a detailed list.
-
Setting Up New Accounts: Crucially, you must have an alternative bank account fully established and operational before closing your PNC account. Ensure this new account can accommodate all your incoming and outgoing transactions. Transferring funds directly to a new account within PNC, if you’re only closing one specific account and keeping others, is also an option.
-
Transferring Funds: Once your new account is ready and all automatic transactions have been identified, initiate the transfer of your balance from the PNC account. It’s advisable to leave a small buffer amount (e.g., $10-$50) in the PNC account until it’s officially confirmed closed, just in case any minor, unforeseen debits or credits surface.
-
Checking for Outstanding Items: Confirm there are no uncashed checks written from your PNC account, pending debits, or credit card holds tied to that account. Allowing time for these to clear is critical.
Understanding the Implications: Potential Fees and Relationship Impact
Closing an account isn’t always without repercussions. Be aware of potential account closure fees. While many banks have phased these out, some might still charge a fee if an account is closed within a certain timeframe after opening (e.g., 90 or 180 days). Review your account agreement or contact PNC directly to confirm.
Consider the impact on your banking relationship. If you have other products with PNC, such as loans, credit cards, or investment accounts, closing a checking or savings account might subtly alter your overall relationship with the bank. While usually not significant for single account closures, it’s good to be aware. Furthermore, ensure you understand how closing the account might affect your access to online banking features for other linked PNC products. Lastly, ensure you have downloaded and saved all necessary statements and transaction records for tax purposes or future reference, as online access to closed accounts can be limited or revoked.
The Online Process for PNC Account Closure: What to Expect
While the complete closure of a bank account often requires a final layer of verification that may involve a phone call or branch visit, PNC, like many major banks, provides robust online channels to initiate and manage much of the process. Leveraging these digital tools can significantly streamline your journey towards account closure.
Initiating Contact: Utilizing PNC’s Digital Channels
PNC offers several online avenues to begin the account closure process or gather the necessary information. The most direct methods typically include:
-
Online Banking Portal: Log into your PNC online banking account. Navigate to the customer service or “contact us” section. Many banks provide secure messaging services or dedicated forms for account-related inquiries, including closure requests. Look for options like “Send a Secure Message,” “Contact Support,” or “Manage Accounts.” This is often the preferred method as it’s secure and creates a digital record of your communication.
-
Secure Message System: Within the online banking portal, locate the secure message center. Compose a message clearly stating your intent to close your specific account(s), including account numbers. Ask for a list of any outstanding requirements or steps you need to take. This method allows for asynchronous communication, meaning you can send your request at any time and receive a response within a typical business day or two.
-
PNC Website Support: The general PNC Bank website often has a comprehensive FAQ section or a “Contact Us” page detailing different ways to reach customer service, including specific numbers for account-related inquiries. While not directly initiating closure, it can help you find the precise online form or phone number for the next step.
-
Virtual Assistant/Chatbot: Some financial institutions use AI-powered virtual assistants or chatbots on their website or within their mobile app. While these may not be able to execute a closure, they can often guide you to the correct department or provide links to relevant information.
It’s crucial to specify the exact account(s) you wish to close (e.g., checking account ending in XXXX, savings account ending in YYYY). Avoid generic statements to prevent misinterpretations.
Required Information and Documentation
When you formally request to close your account, whether online or via a follow-up call, PNC will require specific information to verify your identity and process the request securely. Be prepared with:
-
Account Numbers: Have the full account number(s) of the account(s) you wish to close readily available.
-
Personal Identification Information: This typically includes your full legal name, address, date of birth, Social Security Number (SSN), and possibly your mother’s maiden name or answers to security questions. This is crucial for identity verification.
-
Reason for Closure (Optional but Recommended): While not always mandatory, providing a brief reason for closing your account (e.g., “relocating,” “consolidating accounts,” “found a better rate elsewhere”) can sometimes streamline the process or provide valuable feedback to the bank.
-
Instructions for Remaining Funds: Clearly state how you wish any remaining balance (even a small amount) to be handled. Common options include transferring it to another PNC account (if you have one), direct depositing it into an external account (you’ll need the routing and account number), or requesting a cashier’s check be mailed to your address of record.
The Verification Process: Ensuring Security and Compliance
Given the sensitive nature of closing a financial account, PNC will implement stringent verification steps to protect your assets and prevent fraud. This process typically involves:
-
Two-Factor Authentication (2FA): If you’re initiating the process through online banking, you may be prompted to complete a 2FA step (e.g., a code sent to your registered phone or email) to confirm your identity before proceeding with a sensitive request.
-
Verbal Confirmation: Even if you initiate the request online, it is highly probable that a PNC representative will need to contact you by phone to verbally confirm your identity and intent to close the account. This adds an essential layer of security. They may ask security questions only you would know.
-
Written Confirmation (Optional): In some cases, especially if there are complexities, PNC might require a signed written request. While less common for simple checking/savings accounts, it’s a possibility for certain types of accounts or situations.
-
Final Review of Terms: The representative will likely confirm that you understand any final implications, such as the cessation of services, fee structures, and how any outstanding items will be handled.
Always ensure you are communicating through official PNC channels. Be wary of unsolicited emails or calls claiming to be from the bank asking for sensitive information to close your account.
Ensuring a Smooth Transition: Financial Best Practices Before and After Closure
Closing a bank account is more than just a procedural step; it’s a financial transition that requires careful planning to avoid disruptions to your income, payments, and overall financial stability. Proactive management of your financial ecosystem is key.
Updating Direct Deposits and Automatic Payments
This is arguably the most critical step in preventing financial disruption. Failing to update these items can lead to missed income, overdue bills, and potential fees.
-
Direct Deposits: Contact your employer’s HR or payroll department well in advance to update your direct deposit information to your new bank account. If you receive government benefits (e.g., Social Security, veteran benefits), contact the relevant agency to change your direct deposit details. Allow ample time for these changes to take effect, often one or two pay cycles.
-
Automatic Payments (ACH Debits): Systematically update all companies that automatically debit your PNC account. This includes utility providers (electricity, gas, water, internet), loan providers (mortgage, car loan, student loans), insurance companies, credit card companies, subscription services (streaming, gym memberships), and any other recurring payments. Log into each service’s online portal or call their customer service to update the payment method to your new account. Keep records of when these changes were made.
-
Scheduled Transfers: If you have any recurring transfers set up within PNC (e.g., from checking to savings), ensure these are canceled or redirected to your new accounts.
It’s wise to overlap your old and new accounts for a period (e.g., 1-2 months) to ensure all direct deposits and automatic payments have successfully transitioned before zeroing out your old PNC account.
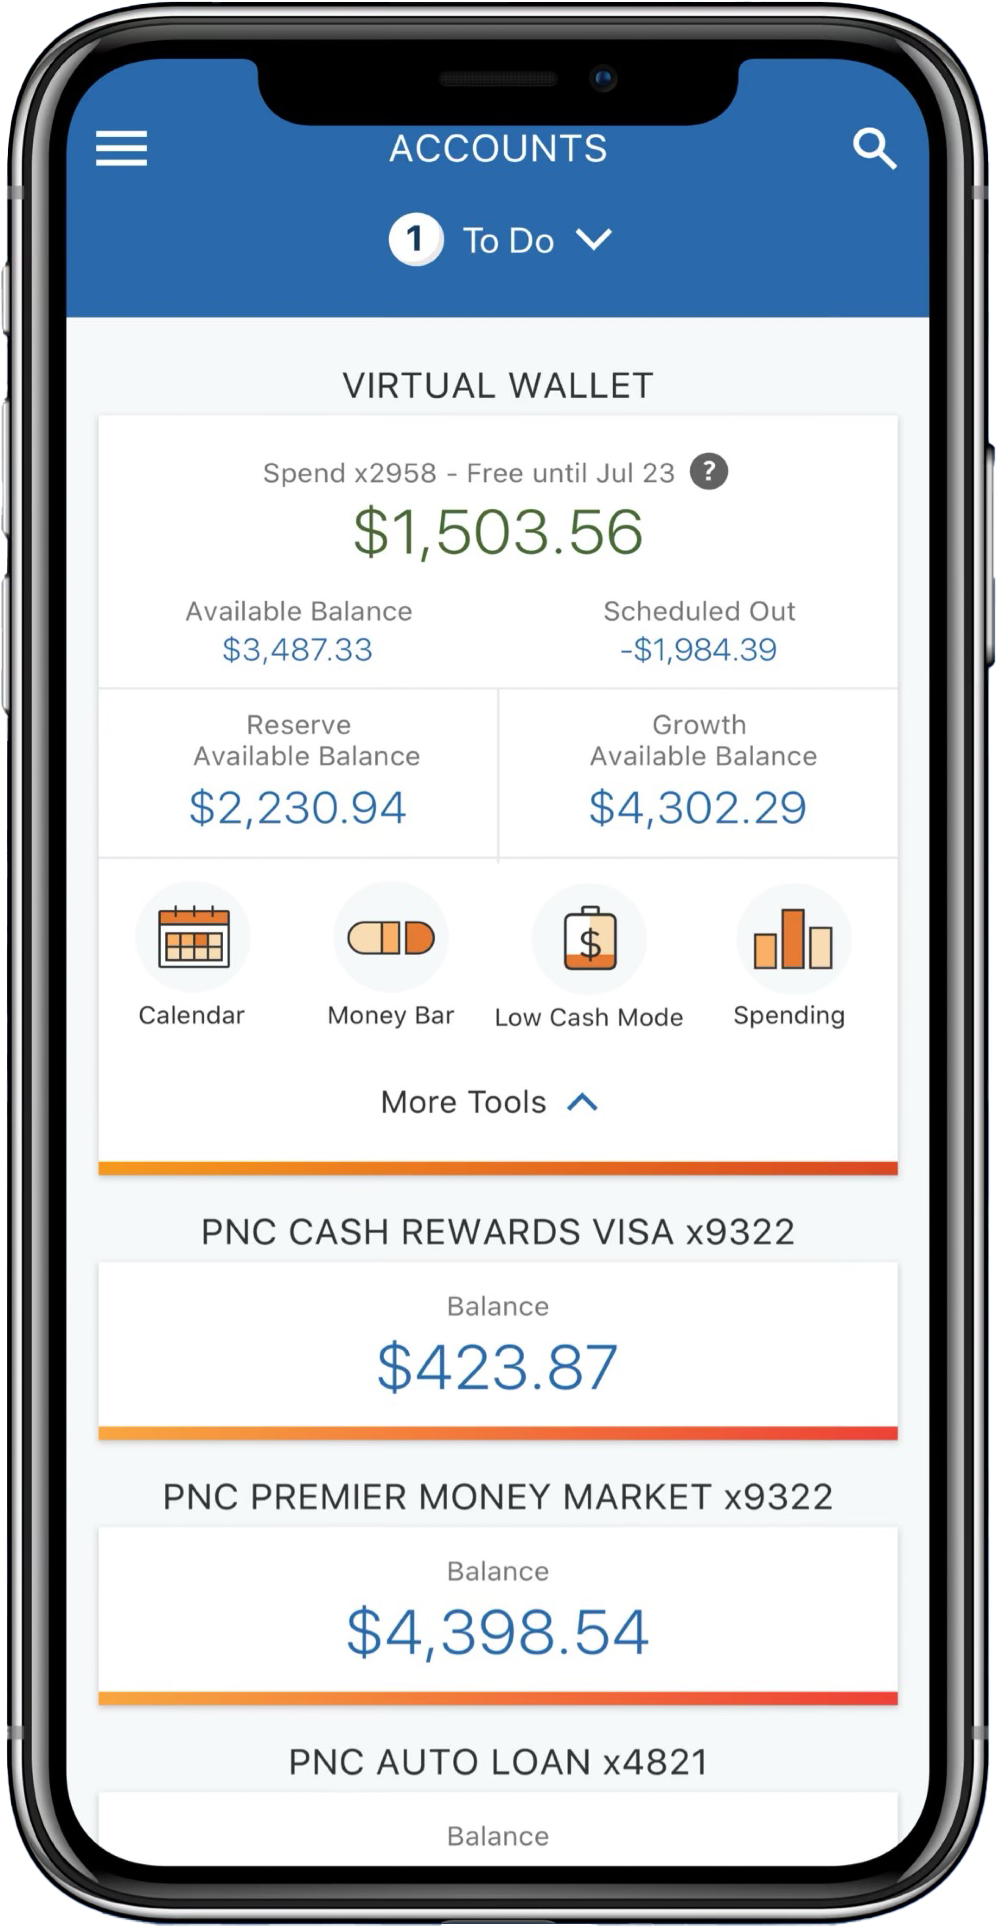
Managing Outstanding Checks and Pending Transactions
Even in an increasingly digital world, paper checks and pending transactions can complicate account closure.
-
Outstanding Checks: If you’ve written any checks from your PNC account that haven’t yet been cashed, make every effort to notify the recipients to deposit them immediately or provide them with an alternative payment method. You cannot close an account if there are uncashed checks linked to it. If a check surfaces after closure, it could be returned unpaid, incurring fees for both you and the recipient.
-
Pending Transactions: Be aware of any recent debit card purchases or online bill payments that might still be pending. Allow a few business days for all transactions to fully clear before initiating closure. Closing an account with pending transactions can lead to complications and potential overdrafts if the transaction eventually clears.
-
Stop Payments: If you have any stop payments active on your PNC account, understand that these will cease once the account is closed.
Final Statement Review and Record Keeping
Upon successful closure, PNC should send you a confirmation. It’s vital to review this and retain key documents for future reference.
-
Confirmation of Closure: Ensure you receive a written confirmation (physical mail or secure email) from PNC stating that the account has been officially closed and has a zero balance. This is your proof of closure.
-
Download Statements: Before closure, download and save all your historical bank statements (at least the last 7 years for tax purposes, but preferably all available). These can be invaluable for tax audits, proving payments, or resolving future financial discrepancies.
-
Record Keeping: Keep a physical or digital folder with all documents related to the account closure: your initial request, PNC’s confirmation, records of updated direct deposits/automatic payments, and final statements. This organized record-keeping is a cornerstone of sound personal finance.
Alternatives to Full Closure: When Less Drastic Measures Suffice
Sometimes, a full account closure isn’t the only, or even the best, solution for your financial needs. PNC, like other major banks, often provides options that allow you to modify your banking relationship without completely severing ties. Exploring these alternatives can save time and maintain continuity.
Downgrading Account Types
If your primary concern is high fees or too many unused features, a full closure might be overkill. Many banks offer a tiered system of checking and savings accounts.
-
Lower-Fee or No-Fee Options: PNC might have simpler checking accounts with lower or no monthly maintenance fees, particularly if you maintain a certain minimum balance or meet specific direct deposit requirements. Downgrading to such an account allows you to retain your account number, maintain an existing relationship, and avoid the hassle of setting up entirely new direct deposits and automatic payments, while still addressing your fee concerns.
-
Basic Savings Accounts: If you have a more complex savings or money market account that no longer suits your needs, inquire about switching to a more basic, no-frills savings account. This can simplify your finances without necessitating a full bank change.
This approach is particularly beneficial if you want to keep a secondary account with PNC for specific purposes, such as an emergency fund or a joint account, but want to reduce the cost or complexity of your primary account.
Reducing Account Activity
Perhaps you don’t need to close the account, but rather reduce its active role in your financial life.
-
Maintaining Minimal Balance: If your PNC account has no monthly fees or if you can easily meet the requirements to waive them, you might consider simply reducing its activity. Transfer your primary funds elsewhere and keep a minimal balance, using it as a backup account or for very specific, infrequent transactions.
-
Dormant Account Management: Understand PNC’s policy on dormant accounts. If an account remains inactive for an extended period (typically 1-5 years, varying by state and bank policy), it may be declared dormant and eventually escheated (turned over) to the state. If you choose to keep an account open with minimal activity, ensure you understand and comply with any requirements to keep it active to avoid this process.
This strategy can be useful for retaining an account that you might need again in the future without the overhead of immediate closure.
Exploring Other PNC Products
If your dissatisfaction stems from a specific account type but you are otherwise content with PNC as an institution, consider consolidating your banking within PNC itself.
-
Internal Transfers and Consolidations: Instead of moving funds to an entirely different bank, explore if PNC offers another account type or product that better fits your current needs. For example, if you’re unhappy with your checking account but have a PNC credit card, you might open a different PNC checking account and close the old one, keeping your credit card relationship intact.
-
Relationship Banking: Discuss your financial goals with a PNC banker. They might be able to offer tailored solutions, perhaps bundling services that reduce fees or provide better benefits across your existing or new PNC accounts. Sometimes, simply communicating your needs can unlock solutions you weren’t aware of.
These alternatives highlight that financial management is dynamic. Before making a final decision to close, take the time to evaluate if a less permanent adjustment might serve your financial interests better, leveraging your existing banking relationship where appropriate.
Post-Closure Considerations: Maintaining Financial Health
The act of closing a bank account is not just an end; it’s also a new beginning for your financial journey. What you do after the account is officially closed is just as important as the steps you took beforehand to ensure continued financial health and peace of mind.
Monitoring Your Credit Report
While closing a checking or savings account generally doesn’t directly impact your credit score in the way closing a credit card might, it’s still prudent to monitor your credit report.
-
Impact of Account Changes: Ensure that the closure doesn’t inadvertently lead to any issues, such as unnoticed outstanding payments that might have been linked to the closed account. While rare, a misstep could lead to a late payment report if, for instance, a forgotten automatic loan payment bounced due to the account closure.
-
Fraud Detection: Regularly reviewing your credit report (you’re entitled to a free report from each of the three major bureaus annually at AnnualCreditReport.com) is a fundamental practice for fraud detection. After any significant financial change, including account closure, it’s an opportune time to be extra vigilant for any suspicious activity. This helps ensure that your personal information, which was used in the account closure process, hasn’t been compromised.
Re-evaluating Your Banking Needs
Closing an account with one institution and moving to another provides an excellent opportunity to reassess your overall banking strategy and future financial goals.
-
Future Financial Goals: Are you saving for a house, retirement, or a major purchase? Your new bank should offer products and services that align with these goals, such as high-yield savings accounts, investment platforms, or robust lending options.
-
New Opportunities: Take advantage of this fresh start. Explore innovative fintech solutions, online-only banks with competitive rates, or credit unions known for their customer service and community focus. Don’t just settle for the status quo; research thoroughly to find an institution that genuinely meets your evolving needs and offers superior financial tools.
-
Digital Banking Experience: Consider the quality of the new bank’s online banking portal and mobile app. In today’s world, a user-friendly, secure, and feature-rich digital experience is non-negotiable for managing your money effectively.
Building a Stronger Financial Foundation
The decision to close an account, often stemming from a need for better financial management, should be integrated into a larger strategy for building a more robust financial foundation.
-
Diversification: Consider diversifying your banking relationships. While having too many accounts can be cumbersome, having accounts at two different institutions (e.g., a primary bank for daily transactions and a high-yield online bank for savings) can offer both convenience and security.
-
Emergency Funds: Ensure your emergency fund is adequately funded and easily accessible, ideally in a separate, high-yield savings account that is distinct from your primary checking account.
-
Budgeting and Financial Planning: Use this opportunity to recommit to sound budgeting practices. Re-evaluate your income and expenses, set new financial targets, and regularly review your financial health. Leveraging online budgeting tools or financial advisors can be instrumental here.
Closing a PNC bank account online, when approached systematically and with an understanding of its financial implications, can be a smooth and empowering process. It’s an opportunity not just to change banks, but to refine your financial strategy, optimize your resources, and set yourself up for greater financial success and peace of mind. By following these professional and insightful guidelines, you can ensure your transition is seamless and beneficial to your long-term financial health.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.