
The seemingly simple query “how to calculate 10” might appear trivial at first glance. Yet, in the vast and intricate world of personal finance, investing, and business management, “10” is far more than just a digit. It represents a myriad of critical concepts: a targeted 10% return on investment, a crucial 10-year savings horizon, a 10x growth multiplier, or even the fundamental breakdown of a budget into its top 10 categories. Understanding how to “calculate 10” in these contexts is not about performing a basic arithmetic operation; it’s about mastering the underlying financial metrics, formulas, and principles that empower individuals and businesses to make informed decisions, set realistic goals, and achieve sustained financial success.
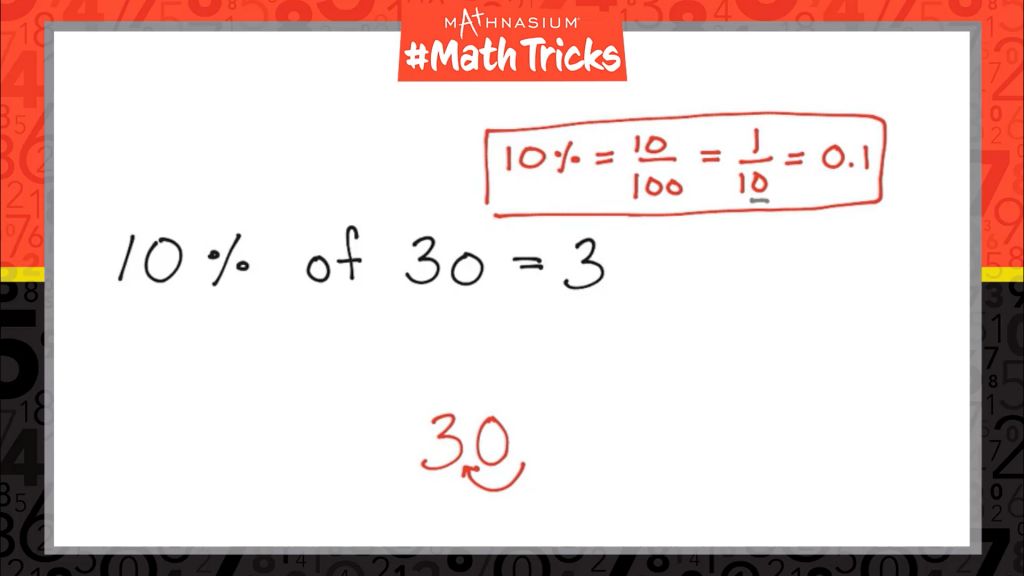
This article will delve into the essential financial calculations that, while often involving other numbers, can be critically understood through the lens of achieving or interpreting “10” in various financial scenarios. We will explore how mastering these calculations can transform abstract financial goals into actionable plans, providing clarity and control over your financial future.
The Foundational Significance of “10” in Financial Goal Setting
In finance, the number “10” frequently serves as a benchmark, a target, or a key factor in projections. Whether it’s aiming for a specific percentage, a numerical target, or understanding time horizons, “10” provides a tangible focus for analysis and strategy.
Interpreting “10” as a Percentage: The 10% Rule
One of the most common applications of “10” in finance is as a percentage. From saving 10% of your income to calculating a 10% return on investment, this simple rate can have profound implications over time. Understanding how to calculate 10% of any given figure is fundamental. For example, knowing that saving just 10% of your monthly income can lead to substantial wealth accumulation over decades underscores the power of consistent, even modest, financial discipline. Similarly, a 10% annual return, while seemingly small, can double your money in roughly seven years due to the magic of compounding, a concept we will explore further. This foundational understanding allows for quick mental calculations and scenario planning, providing a crucial starting point for more complex financial modeling.
“10” as a Target: Setting Achievable Milestones
Beyond percentages, “10” can represent a concrete financial target. This might be saving an initial $10,000 for an emergency fund, aiming for a 10-fold return on a specific investment (a 10x multiplier), or even breaking down a large financial goal into 10 manageable steps. The ability to calculate what it takes to reach these “10” targets involves backward planning and understanding the components required. For instance, if your goal is to save $10,000, you’ll need to calculate how much you need to save monthly or annually, considering your time horizon and potential earnings. This shifts the focus from an abstract dream to a series of quantifiable, achievable actions. The psychological impact of breaking down large sums into smaller, more digestible “10” units can also make financial goals feel less daunting and more attainable.
“10” as a Time Horizon: Understanding Long-Term Growth
The 10-year mark often serves as a significant milestone in financial planning. Whether it’s a 10-year investment plan, a projection for retirement savings in the next decade, or analyzing the performance of an asset over the past 10 years, this time horizon is crucial. Calculating future values, compound interest, or required savings over a 10-year period provides invaluable insights into the feasibility and potential outcomes of financial strategies. For example, understanding how a small monthly investment compounds over 10 years versus 5 years dramatically illustrates the power of time in wealth creation. The ability to model these longer-term scenarios is essential for strategic planning, especially when considering major life events like homeownership, children’s education, or retirement.
Core Calculations for Personal Financial Health
At the heart of financial management lies a set of fundamental calculations that dictate personal financial health. These aren’t just for experts; they are tools everyone can use to understand where their money goes and how to make it work harder.
Budgeting and Expense Tracking: The 10-Category Approach
Effective budgeting begins with understanding your income and expenses. One practical way to approach this is to categorize your spending into 10 key areas (e.g., housing, transportation, food, utilities, entertainment, savings, debt repayment, healthcare, personal care, miscellaneous). By tracking what percentage of your income goes into each of these “10” categories, you can quickly identify areas for optimization. The core calculation here is simple: Expense Category Amount / Total Income x 100%. Regularly reviewing these percentages helps ensure you’re not overspending in one area at the expense of another critical financial goal, such as saving that crucial 10% of your income.
Calculating Net Worth: A Snapshot of Financial Standing
Your net worth is a critical indicator of your financial health, calculated simply as Assets – Liabilities. While “10” might not appear directly in this formula, understanding how specific assets or liabilities contribute to or detract from your net worth by a factor of 10 (e.g., a $10,000 increase in savings, or a $10,000 reduction in debt) is crucial. Regularly calculating your net worth allows you to track progress towards financial independence and provides a clear picture of your current financial standing. It empowers you to see the tangible impact of your financial decisions over time, helping to identify whether your assets are growing by 10% or if your liabilities are shrinking by 10%.
Debt Management: Prioritizing Repayment and Reducing Interest
For many, managing debt is a significant financial hurdle. Key calculations here involve understanding interest rates, minimum payments, and the total cost of debt. For example, calculating how much interest you’d pay on a $10,000 loan at a 10% annual interest rate over a specific period is eye-opening. The simple interest formula, Principal x Rate x Time, helps illustrate the compounding cost of debt. More advanced calculations, often found in loan amortization schedules, show how much of each payment goes towards principal versus interest. Prioritizing high-interest debts, often following methods like the “debt snowball” or “debt avalanche,” relies on precise calculations to achieve the most efficient path to debt freedom. Reducing debt by 10% can free up significant cash flow for other financial goals.
Unlocking Investment Growth: The Power of Rates and Returns
Investing is where the number “10” truly shines, particularly in the context of growth rates, returns, and the exponential power of compounding. Mastering these calculations is essential for wealth creation.
Compound Interest: The Eighth Wonder of the World

Compound interest is arguably the most powerful concept in finance. It’s the interest you earn on both your initial principal and the accumulated interest from previous periods. The formula for future value with compound interest is FV = PV (1 + r)^n, where FV is future value, PV is present value, r is the annual interest rate (e.g., 0.10 for 10%), and n is the number of compounding periods (e.g., 10 years). Calculating how a $1,000 investment grows at a 10% annual rate over 10 years versus 20 years dramatically demonstrates this power. Over 10 years, it grows to roughly $2,593.74. Over 20 years, it becomes $6,727.50 – more than double the 10-year growth due to the exponential effect. Understanding this calculation is paramount for long-term investing and retirement planning.
Rate of Return: Measuring Investment Performance
The rate of return (ROR) measures the gain or loss on an investment over a specified period, expressed as a percentage of the initial investment. A simple ROR calculation is (Current Value – Initial Value) / Initial Value x 100%. For example, if you invested $10,000 and it grew to $11,000, your return is 10%. While seemingly straightforward, consistently achieving even a modest 10% annual return can lead to significant wealth over time. This calculation is crucial for evaluating the performance of your portfolio, comparing different investment opportunities, and understanding whether your investments are on track to meet your financial goals.
The Rule of 72 and Beyond: Quick Estimates of Doubling Time
The Rule of 72 is a mental math shortcut to estimate the number of years required to double your money at a given annual rate of return. Simply divide 72 by the annual return rate. For instance, at a 10% annual return, your money would roughly double in 7.2 years (72 / 10 = 7.2). This quick calculation provides an intuitive understanding of investment growth and helps illustrate the power of compounding without complex formulas. Similarly, one could consider a “Rule of 10” for a rough estimate of achieving specific multiples of your investment, though this is less standardized. For instance, how many doubling periods (each 7.2 years at 10% return) are needed to achieve a 10x return? This kind of quick estimation is invaluable for on-the-fly financial planning and goal setting.
Strategic Financial Planning: Projecting Goals and Understanding Risk
Beyond day-to-day management and investment growth, strategic financial planning involves projecting future needs and mitigating risks. “10” frequently appears in these projections, from retirement planning to emergency fund calculations.
Retirement Planning: The 10x Income Rule of Thumb
A common rule of thumb for retirement planning suggests you should aim to have 10 times your annual income saved by the time you retire. While highly generalized, this “10x income” rule provides a quick, albeit rough, target. Calculating what it would take to reach this 10x target involves projecting your future income, understanding inflation, and estimating your desired retirement lifestyle. This requires sophisticated financial modeling, often aided by retirement calculators that factor in compound growth, contributions, and withdrawal rates. Breaking this large 10x goal into smaller, 10-year increments (e.g., aim for 1x income by age 30, 3x by age 40, etc.) makes the path clearer and more manageable.
Emergency Funds: The 10-Month Security Blanket
Another crucial aspect of financial planning is building an emergency fund. A widely recommended guideline is to save 3-6 months’ worth of living expenses. However, some might aim for a more robust “10-month security blanket” for added peace of mind, especially if they have an unpredictable income or significant financial obligations. Calculating the exact amount needed involves totaling your essential monthly expenses and then multiplying that figure by 10. This direct calculation provides a clear, actionable target for building financial resilience, offering a buffer against unexpected life events like job loss, medical emergencies, or significant home repairs.
Risk Assessment and Diversification: The 10-Asset Portfolio
Understanding risk is paramount in investing. Diversification, the strategy of spreading investments across various asset classes to reduce risk, is often conceptualized through dividing your portfolio into different categories. While not a strict rule, thinking in terms of a “10-asset portfolio” or ensuring no single asset constitutes more than 10% of your total holdings can be a helpful mental model for maintaining diversification. Calculating the allocation percentages for each asset (e.g., Individual Asset Value / Total Portfolio Value x 100%) ensures that your portfolio is appropriately diversified and that you aren’t overexposed to any single risk. This systematic approach helps mitigate the impact of any single investment underperforming.
Practical Application: Leveraging Tools and Formulas
While understanding the theoretical underpinnings of these calculations is vital, practical application often involves leveraging modern tools and a systematic approach.
Spreadsheet Power: Excel and Google Sheets for Financial Modeling
For anyone serious about managing their finances, spreadsheets like Excel or Google Sheets are indispensable. These tools allow you to perform complex calculations, create amortization tables, project future values, track expenses, and build detailed budgets. Learning basic formulas such as SUM, AVERAGE, PV (Present Value), FV (Future Value), PMT (Payment), and RATE can transform your ability to “calculate 10” in a myriad of financial contexts. You can easily set up a spreadsheet to calculate your net worth, track your 10 categories of expenses, project the growth of an investment at a 10% annual return over 10 years, or determine how long it will take to save $10,000.
Online Financial Calculators and Apps: Instant Insights
Numerous online financial calculators and mobile apps provide instant solutions for complex financial questions. Whether you need to calculate loan payments, retirement savings projections, or compound interest, these tools simplify the process. Websites like Bankrate, Investopedia, and various brokerage firms offer calculators tailored to specific financial scenarios. While they perform the calculations for you, understanding the underlying principles discussed in this article allows you to input the correct variables and interpret the results accurately. They can quickly show you how a 10% increase in savings or a 10-year extension of your investment horizon can impact your financial future.
Seeking Professional Guidance: When Expertise Matters
While self-education and diligent tracking are powerful, there are times when seeking professional financial advice is prudent. Financial advisors can help you navigate complex tax implications, optimize investment strategies, and build comprehensive financial plans that align with your long-term goals. They can provide tailored insights into how to best “calculate 10” in the context of your unique financial situation, whether that means strategizing to hit a specific 10x investment target or optimizing your financial plan to achieve a desired 10% growth rate annually. Their expertise ensures that your calculations and strategies are robust and well-informed.
Conclusion
The seemingly straightforward question “how to calculate 10” unravels into a rich exploration of fundamental financial concepts, strategic planning, and the power of numerical targets. From understanding the impact of a 10% savings rate to projecting investment growth over 10 years, the number “10” serves as a powerful illustrative guide in the world of money. Mastering these essential financial calculations empowers you to move beyond abstract concepts, transform your financial aspirations into actionable plans, and gain confidence in navigating the complexities of personal finance and investing. By diligently applying these principles and leveraging available tools, you’re not just calculating a number; you’re actively shaping a more secure and prosperous financial future. The journey to financial mastery begins with a solid grasp of these core calculations, making “how to calculate 10” a surprisingly profound inquiry into the bedrock of financial wisdom.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.