
The Digital Bridge: Why Physical Cash Still Matters for App Users
In an increasingly cashless society, mobile payment applications like Cash App have revolutionized the way individuals manage their funds, send money, and conduct transactions. Yet, despite the pervasive shift towards digital wallets, physical cash remains a cornerstone of the economy for many. Whether it’s income from informal work, gifts, or simply a preference for handling tangible currency, a significant portion of the population still operates with cash. This creates a critical need for seamless mechanisms to bridge the gap between physical money and digital financial platforms. The ability to convert cash into digital funds within an app directly addresses this need, ensuring financial inclusivity and convenience for a broader user base. Without such features, mobile payment apps would inadvertently exclude those who primarily deal with cash, limiting their utility and reach.
Bridging the Gap: The Need for Cash-to-Digital Solutions
The demand for cash-to-digital solutions stems from various user behaviors and economic realities. Many individuals receive wages in cash, conduct transactions with merchants who prefer cash, or simply prefer to withdraw physical currency for daily spending. For these users, an inability to easily deposit cash into their mobile app would necessitate a trip to a traditional bank, an option not always convenient or accessible. Mobile apps, therefore, must act as a direct conduit, offering a frictionless path to digitize physical currency. This not only enhances the app’s functionality but also empowers users to leverage the full suite of digital financial services, from peer-to-peer payments to investing, all powered by their newly digitized funds. The underlying technology behind these solutions focuses on creating secure, reliable, and user-friendly interfaces that can be integrated into existing retail infrastructures.
Accessibility and Inclusion: Beyond Traditional Banking
For millions globally, access to traditional banking services is limited or non-existent. This phenomenon, often referred to as being “unbanked” or “underbanked,” means reliance on cash for most, if not all, financial activities. Mobile payment apps with in-store cash deposit capabilities offer a vital lifeline, providing a quasi-banking solution through the ubiquity of smartphones and retail networks. This technological advancement democratizes access to digital finance, enabling individuals without bank accounts to participate in the digital economy. It lowers barriers to entry, providing a gateway to financial tools that might otherwise be out of reach, thereby fostering greater financial inclusion. The design of these features prioritizes simplicity and broad compatibility, ensuring that users with varying levels of technological literacy can effectively utilize the service to manage their funds.
Navigating the Process: A Step-by-Step Tech Tutorial
Adding cash to your Cash App account at a retail store is designed to be a straightforward process, leveraging a combination of your smartphone’s capabilities and the existing point-of-sale systems in participating stores. Understanding each step ensures a smooth and secure transaction, transforming physical currency into immediately usable digital funds. This tutorial breaks down the technical interaction, from preparing your app to confirming your deposit.
Preparing Your Cash App for In-Store Deposits
Before heading to a store, a few preparatory steps within the Cash App itself are necessary to initiate the deposit process. This involves locating the specific feature designed for cash deposits and familiarizing yourself with any associated limits.
Locating the “Paper Money” Feature
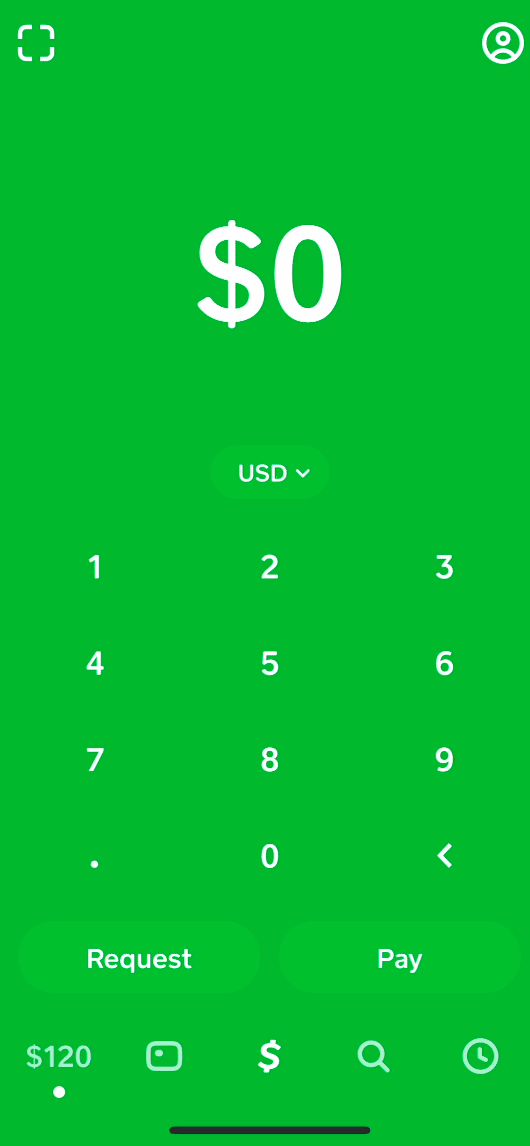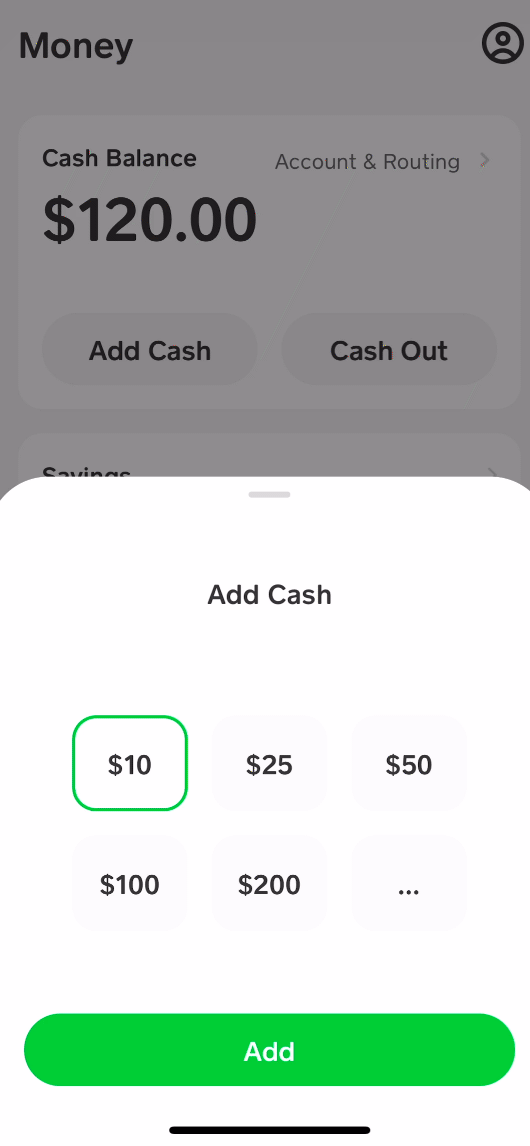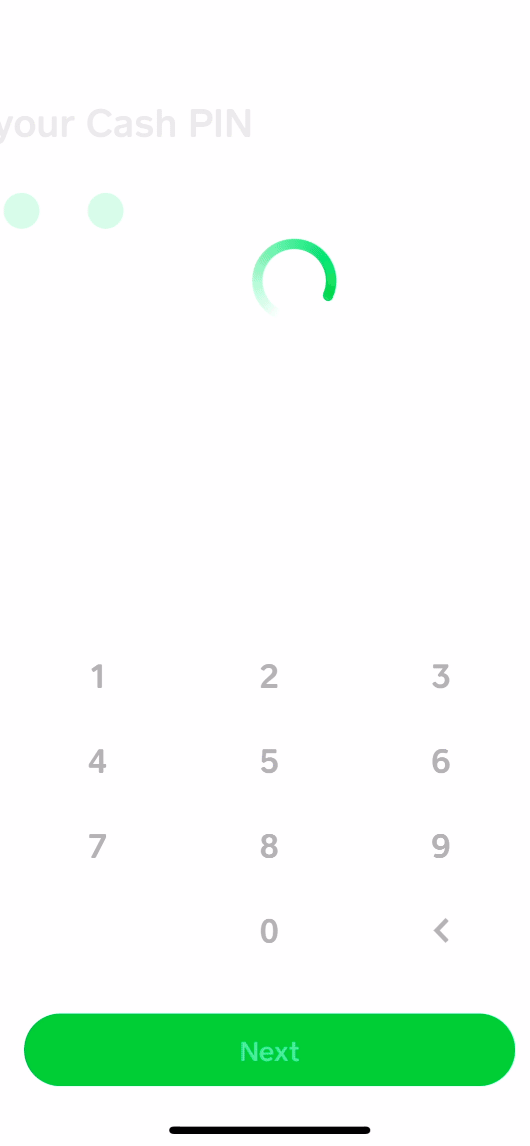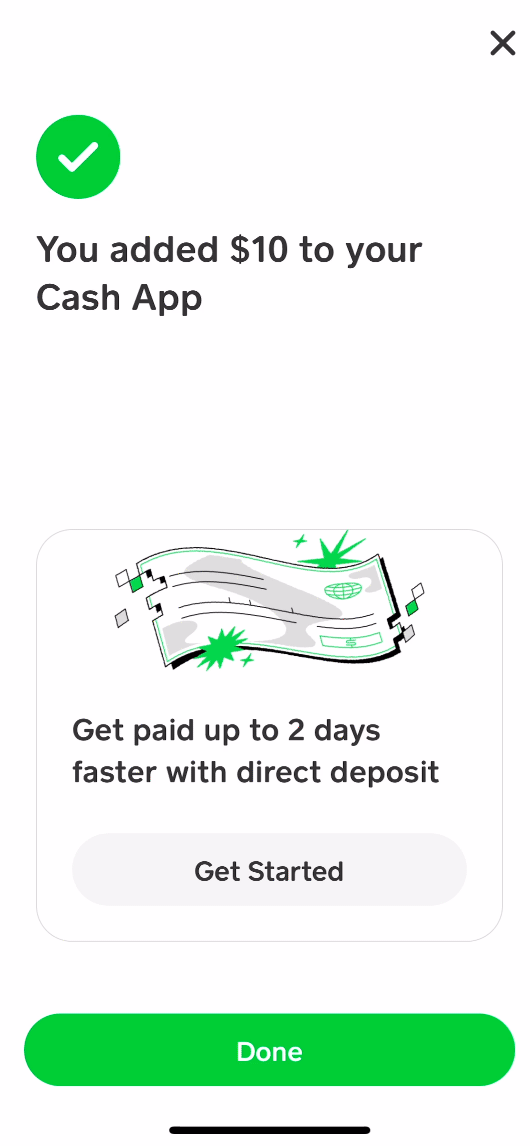
The journey begins within the Cash App’s intuitive interface. Users typically access the “Paper Money” or “Deposit Cash” feature by navigating to the banking tab (often represented by a house icon or dollar sign), then selecting the option to add cash. This action triggers the app to prepare for a physical deposit, generating the necessary digital credentials for the transaction. The design emphasizes user-friendliness, ensuring that even first-time users can quickly identify and activate this function. The app’s architecture facilitates a direct link between this in-app action and the subsequent interaction at a retail location.
Understanding the Deposit Limit
Like many financial applications, Cash App implements deposit limits to comply with regulatory standards and manage risk. These limits can vary based on the user’s verification status (e.g., identity verification completed) and the specific retailer. Before initiating a deposit, the app will typically display the current limits, ensuring users are aware of how much cash they can deposit in a single transaction or over a specific period. This information is crucial for planning larger deposits and preventing potential transaction failures due to exceeding limits. The app’s backend systems dynamically adjust these limits based on real-time data and user profiles, a core aspect of its robust financial technology framework.
The In-Store Transaction: Seamless Integration
Once your Cash App is ready, the physical transaction at a participating store is the next step. This process relies on generating a unique barcode and interacting with the store’s point-of-sale (POS) system.
Identifying Participating Retailers
Cash App partners with various national and local retailers to facilitate cash deposits. The app itself provides a mapping feature or a list of nearby participating locations, making it easy for users to find a convenient store. This extensive network is a testament to the sophisticated integration between Cash App’s platform and diverse retail POS systems, allowing for a standardized deposit experience across different store environments. These partnerships are critical for the scalability and accessibility of the service, expanding the physical footprint of digital finance.
Generating Your Unique Deposit Barcode
Upon selecting the “Deposit Cash” option and confirming your intent, Cash App generates a unique, scannable barcode directly within the app. This barcode is not merely an identifier; it’s a cryptographically secured token that links the physical cash transaction at the store directly to your specific Cash App account. The ephemeral nature of these barcodes, often with a limited validity period, adds an extra layer of security, minimizing the risk of unauthorized use. The technology here is akin to a digital handshake, ensuring that the cash handed over to the cashier is precisely attributed to your digital wallet.
Completing the Deposit with a Cashier
At the chosen retailer, you present your generated barcode to the cashier. The cashier scans this barcode using their standard POS scanner, similar to how they would scan a product. You then hand over the desired amount of cash, which the cashier inputs into their system. The POS system, integrated with Cash App’s backend, processes this information, initiating the transfer of funds. This direct integration streamlines the process, removing intermediaries and accelerating the deposit confirmation. The interaction is designed to mimic any other retail transaction, making it familiar and efficient for both users and store personnel.
Real-Time Confirmation and Digital Security
A cornerstone of modern financial technology is real-time processing and robust security measures. Cash App’s in-store deposit feature excels in both areas, providing immediate feedback and protecting user data.
Instant Notification of Funds
Almost instantaneously after the cashier completes the transaction, you will receive a notification within the Cash App confirming the deposit. The funds are typically available for use within your account immediately, reflecting the speed and efficiency of the underlying API integrations and data processing systems. This real-time confirmation provides peace of mind and allows users to immediately utilize their digitized cash for payments, transfers, or other app features.
Safeguarding Your Transaction Data
Throughout the entire process, Cash App employs advanced encryption protocols and security measures to protect your personal and financial information. The barcode itself is a one-time use token, and the transmission of transaction data between the retailer’s POS system and Cash App’s servers is secured against unauthorized access. This multi-layered security approach is fundamental to maintaining user trust and adhering to industry standards for financial data protection, ensuring that your cash-to-digital conversion is not only convenient but also safe.
The Technology Behind Instant Cash Deposits
The seemingly simple act of depositing physical cash into a digital app at a store is underpinned by a complex interplay of advanced technologies. From secure data generation to real-time communication protocols, each component works in concert to ensure a fast, accurate, and secure transaction.
Secure Barcode Generation: Cryptographic Foundations
The unique barcode generated by Cash App for in-store deposits is more than just a visual pattern; it’s a sophisticated digital key. At its core, this barcode leverages cryptographic principles to embed specific, secure information linking the transaction to your individual account. When you request to deposit cash, the app’s backend generates a unique token, which is then encoded into a scannable format (e.g., QR code or UPC-A). This token typically contains an account identifier, a timestamp, and often a checksum or digital signature to verify its authenticity and integrity. This prevents tampering and ensures that only valid, app-generated barcodes can initiate a deposit, significantly reducing the risk of fraud. The security architecture relies on robust hashing algorithms and secure key management to protect the integrity of each generated barcode.
Real-time API Integration: Connecting Stores to Cash App
The magic of instant deposits happens through sophisticated Application Programming Interface (API) integration. Cash App’s platform establishes secure, real-time communication channels with the point-of-sale (POS) systems of participating retailers. When a cashier scans your barcode, the POS system sends a request via a secure API endpoint to Cash App’s servers. This request carries the unique barcode data along with the amount of cash being deposited. Cash App’s backend then processes this request, validates the barcode, verifies the amount, and, upon successful validation, credits your account. Concurrently, it sends a confirmation back to the POS system, which then finalizes the transaction on the retailer’s side. This seamless, machine-to-machine communication ensures that funds are almost instantly recognized and made available, transforming what would traditionally be a multi-day banking process into a real-time digital transaction.
Fraud Prevention and Account Security Mechanisms
Beyond the secure barcode generation and API integration, Cash App implements a multi-layered fraud prevention strategy for cash deposits. This includes continuous monitoring of transaction patterns for suspicious activities, utilizing machine learning algorithms to detect anomalies that might indicate fraudulent behavior. For instance, unusually high deposit frequencies or large sums from new accounts might trigger additional verification steps. Furthermore, two-factor authentication (2FA) and biometric security features (e.g., fingerprint or face ID) within the app add an extra layer of protection, ensuring that even if a device is compromised, unauthorized access to initiate transactions is prevented. These mechanisms are crucial for maintaining the integrity of the financial ecosystem and safeguarding user funds against evolving cyber threats.
Optimizing Your Cash App Experience for Future Deposits
Maximizing the utility of Cash App for cash deposits involves more than just knowing the steps; it also requires understanding the nuances of the service, including fees and troubleshooting. A clear grasp of these aspects enhances the user experience and ensures smooth, consistent access to digital funds.
Understanding Transaction Fees and Their Structure
While Cash App generally offers many free services, some third-party integrations, like in-store cash deposits, may incur a small fee. These fees, typically a percentage of the deposit amount or a flat rate, are levied by the retail partner for providing the service and maintaining the underlying technology infrastructure. Cash App is generally transparent about these charges, displaying them clearly within the app before you confirm a deposit. Understanding this fee structure allows users to budget effectively and make informed decisions about how and when to digitize their cash, ensuring there are no surprises during the transaction. This transparency is a key component of building trust in financial technology platforms.
Troubleshooting Common Deposit Issues
Occasionally, users might encounter issues during an in-store cash deposit. Common problems can include a barcode failing to scan, the app not showing available retailers, or a delay in funds appearing. For scanning issues, ensuring good lighting and a clear screen on your device often resolves the problem. If the app doesn’t show retailers, checking location services and internet connectivity is advisable. In cases of delayed funds, consulting the in-app support or checking the transaction history for status updates is the next step. Cash App’s support system is designed to guide users through these common technical glitches, providing solutions and ensuring a high success rate for deposits. The platform’s robustness includes logging and monitoring tools that help diagnose and resolve issues efficiently.
Exploring Other Cash App Features for Financial Management
While adding cash is a foundational feature, Cash App offers a broader suite of tools that integrate seamlessly with your newly digitized funds. Users can utilize their balance for peer-to-peer payments, invest in stocks or Bitcoin directly through the app, or use the associated Cash Card for everyday purchases. Understanding these interconnected features allows users to leverage their digitized cash beyond simple transfers, transforming Cash App into a comprehensive personal financial management tool. The ecosystem is designed for fluid movement of funds, offering users multiple avenues to control and utilize their money digitally.
The Future of Cash-to-Digital: Evolving Technologies
The landscape of cash-to-digital solutions is continuously evolving, driven by technological advancements and changing consumer needs. The future promises even greater convenience, security, and integration, pushing the boundaries of what mobile financial applications can achieve.
Expanding Retailer Networks and Geographic Reach
The initial success of in-store cash deposits hinges on the availability of participating retailers. The future will likely see a significant expansion of these networks, extending to more diverse retail environments and smaller local businesses. This broader geographic reach will make cash deposits even more accessible, particularly in underserved communities where traditional banking infrastructure is sparse. Technological improvements in POS system compatibility and API standardization will facilitate easier onboarding for new retail partners, further solidifying the bridge between physical cash and digital finance across wider demographic and geographic segments.
Biometric Authentication and Enhanced Security Protocols
As transaction volumes increase and cyber threats become more sophisticated, security will remain a paramount focus. Future iterations of cash deposit features will likely integrate more advanced biometric authentication methods, such as voice recognition or advanced facial scanning, alongside existing fingerprint and face ID options. Furthermore, the underlying cryptographic protocols will continually be updated to counter emerging vulnerabilities, ensuring that user data and funds remain secure. Innovations in tokenization and multi-party computation could also contribute to more robust transaction verification, minimizing the risk of fraud and enhancing user confidence in the platform’s security.
Predictive Analytics for User Behavior and Service Improvement
The vast amounts of transaction data generated by cash deposits offer invaluable insights for predictive analytics. Future developments will leverage machine learning to analyze user behavior patterns, anticipate peak deposit times, identify potential pain points in the user journey, and even predict demand for cash services in specific areas. This data-driven approach will enable Cash App to proactively optimize its service, from strategically expanding retailer partnerships to refining the user interface and offering personalized support. By understanding how and why users convert cash to digital, the platform can continually evolve to meet their needs more effectively, cementing its role as an indispensable financial tool.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.