
Navigating retirement and income streams can be a complex endeavor, particularly when balancing continued work with Social Security benefits. Many individuals choose to work past their initial retirement age, whether for financial necessity, personal fulfillment, or to maintain a certain lifestyle. Understanding the rules governing how much you can earn while receiving Social Security is crucial for effective financial planning and maximizing your overall income. The Social Security Administration (SSA) implements specific regulations, primarily through what is known as the “earnings test,” which can affect the amount of benefits you receive if you are below your Full Retirement Age (FRA).
Understanding Social Security’s Earnings Test
The earnings test is a critical component of Social Security policy for those who work while receiving benefits before reaching their Full Retirement Age (FRA). The FRA varies depending on your birth year, gradually increasing from 66 for those born between 1943 and 1954, to 67 for those born in 1960 or later. Understanding how this test works at different stages is vital for planning your finances.
Before Full Retirement Age (FRA)
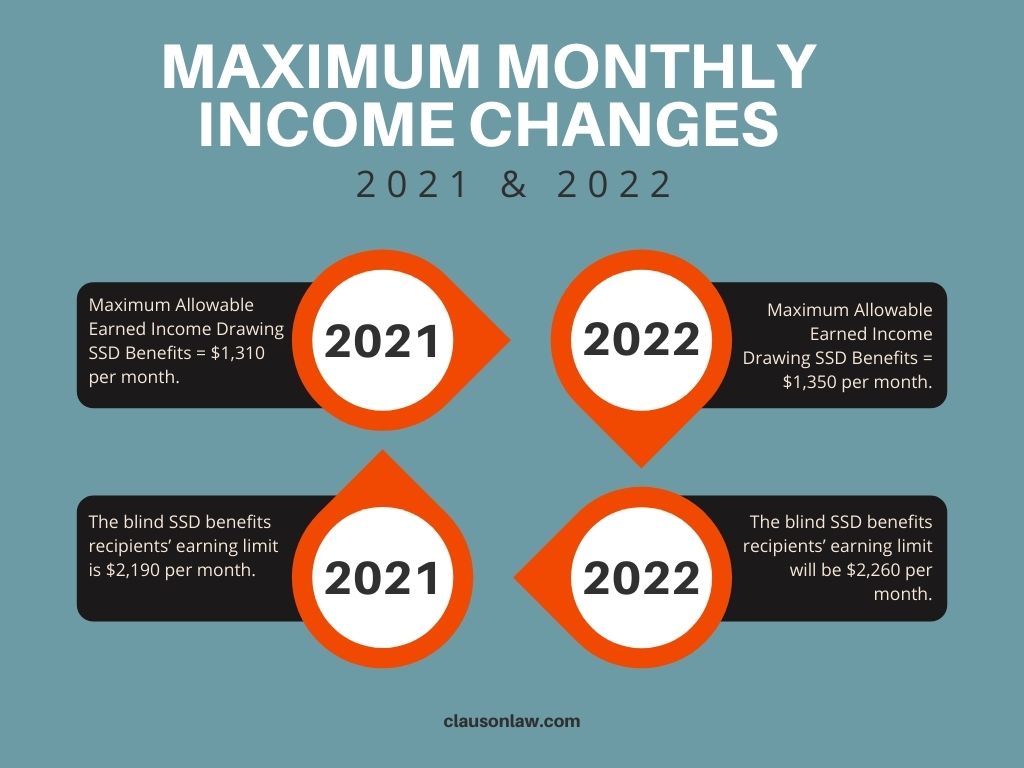
If you are receiving Social Security benefits and have not yet reached your FRA for the entire year, the SSA applies an annual earnings limit. For 2024, this limit is $22,320. If your earnings exceed this threshold, your benefits will be reduced. The rule is that $1 in benefits will be withheld for every $2 you earn above the annual limit.
For example, if you are below your FRA and earn $30,000 in a year, you have exceeded the $22,320 limit by $7,680 ($30,000 – $22,320). In this scenario, the SSA would withhold $3,840 from your Social Security benefits ($7,680 / 2). This reduction is applied throughout the year by reducing your monthly benefit payment until the withheld amount is met. It’s important to note that these withheld benefits are not lost permanently; they typically contribute to a higher monthly benefit amount once you reach your FRA.
In the Year You Reach FRA
A different set of rules applies during the calendar year in which you reach your Full Retirement Age, up until the month you actually attain that age. For 2024, the earnings limit for this specific period is significantly higher, set at $59,520. If you exceed this limit before your birth month, the SSA will withhold $1 in benefits for every $3 you earn above the limit.
This higher limit and different withholding rate acknowledge that individuals are transitioning out of the earnings test phase. For instance, if you reach your FRA in October 2024 and earn $65,000 from January through September, you’ve exceeded the limit by $5,480 ($65,000 – $59,520). The SSA would then withhold $1,826.67 from your benefits ($5,480 / 3). Once you reach your FRA month, the earnings test no longer applies to any income earned from that month forward.
At or After Full Retirement Age
One of the most significant advantages of reaching your Full Retirement Age is that the Social Security earnings test completely disappears. There is absolutely no limit on how much you can earn from work once you hit your FRA. You can continue to work full-time, part-time, or in any capacity, and your Social Security benefits will not be reduced due to your earnings. This provides considerable flexibility and eliminates the need to meticulously track your income against SSA thresholds. Many individuals choose to delay claiming benefits until or after their FRA to take advantage of this, alongside the benefit of earning delayed retirement credits.
Navigating the Trade-offs: Working and Benefits
Working while receiving Social Security benefits before your Full Retirement Age (FRA) involves a careful balance between current income and future financial security. Understanding the immediate and long-term impacts is crucial for making informed decisions.
Impact on Current Benefits
As detailed with the earnings test, working above the annual limits before your FRA will directly reduce your current monthly Social Security benefit payments. This can be a shock to individuals who anticipate a certain level of income from both sources. The withheld amount effectively defers a portion of your benefits. It’s vital for retirees to factor these potential reductions into their budgeting and financial planning. Relying solely on the projected gross Social Security benefit without accounting for potential earnings test reductions can lead to cash flow problems.
However, it’s important to remember that these withheld benefits are not permanently lost. When you reach your FRA, the SSA will recalculate your benefit amount to account for the months your benefits were withheld. This recalculation usually results in a higher monthly benefit for the rest of your life, effectively recouping the earlier reductions. The SSA treats the months benefits were withheld due to earnings as if you hadn’t claimed benefits for those months, thus adjusting your benefit amount upwards as if you had started receiving benefits later.
Long-Term Benefit Increases
Continuing to work, even while receiving Social Security, can lead to higher benefits in the long run. Social Security benefits are calculated based on your 35 highest-earning years. If you continue to work later in life, especially if your recent earnings are higher than some of your earlier career years, these new higher earnings can replace lower-earning years in your Social Security record. This can result in an increase in your primary insurance amount (PIA), which is the base figure from which your monthly benefit is derived.
Additionally, as mentioned, if benefits were withheld due to the earnings test, your benefit amount is adjusted upward at FRA. This adjustment compensates for the earlier withholding, providing a higher ongoing monthly payment. Therefore, working longer can serve a dual purpose: providing immediate income and potentially enhancing your future Social Security benefits.
Tax Implications
An often-overlooked aspect of working while on Social Security is the impact on your federal income taxes. A portion of your Social Security benefits can become taxable if your “provisional income” exceeds certain thresholds. Provisional income is calculated as the sum of your adjusted gross income (AGI), tax-exempt interest income, and half of your Social Security benefits.
For single filers, if your provisional income is between $25,000 and $34,000, up to 50% of your benefits may be taxable. If your provisional income exceeds $34,000, up to 85% of your benefits may be taxable. For those married filing jointly, these thresholds are $32,000 and $44,000, respectively.
Earning additional income from work directly increases your AGI, which in turn increases your provisional income. This can push you into a higher tax bracket or cause a larger portion of your Social Security benefits to become taxable, effectively reducing your net income. It’s crucial to consider these tax implications when planning your work and benefit strategy, as the interplay can significantly affect your take-home pay. Consulting with a tax professional can help you understand your specific situation and plan accordingly.
Strategies for Maximizing Income While Receiving Social Security

Effectively managing your income streams while on Social Security requires strategic planning. There are several approaches you can take to optimize your financial situation, whether you aim to maximize your immediate take-home pay or ensure a higher benefit amount in the future.
Delaying Benefits
One of the most potent strategies for maximizing your Social Security income is to delay claiming benefits past your initial eligibility age, especially if you are still working. While you can start receiving benefits as early as age 62, doing so results in a permanent reduction in your monthly payment. Conversely, for each year you delay claiming benefits past your Full Retirement Age (FRA) up to age 70, you earn “delayed retirement credits.” These credits increase your annual benefit by a certain percentage (e.g., 8% per year for those born in 1943 or later).
If you are working and not reliant on your Social Security benefits for immediate living expenses, delaying your claim can be a financially savvy move. By delaying, you avoid the earnings test entirely while simultaneously locking in a significantly higher monthly benefit for the rest of your life. This strategy is particularly appealing for those who are healthy, have other income sources, and anticipate a long lifespan, as the cumulative effect of higher monthly payments over many years can be substantial.
Strategic Part-Time Employment
If delaying benefits isn’t feasible or desirable, and you’re still below your FRA, a strategic approach to part-time employment can help you manage the earnings test. By carefully monitoring your income, you can aim to stay below the annual earnings limit. For instance, if the limit is $22,320, you might choose to work only enough hours or at a rate that keeps your annual gross income just below that threshold. This allows you to receive your full Social Security benefit without any reductions, while still supplementing your income with earnings from work.
This approach requires meticulous tracking of your income, especially if you have variable work hours or multiple employers. It might mean adjusting your work schedule, taking on specific projects, or even changing the type of work you do to maintain control over your earnings. While it might limit your earning potential in the short term, it ensures your Social Security benefits remain untouched.
Exploring Passive or Self-Employment Income
It’s crucial to understand what kind of income is subject to the Social Security earnings test. The earnings test primarily applies to “earned income” from wages or net earnings from self-employment. However, many other forms of income are generally exempt from the earnings test. These include:
-
Investment income: Dividends, interest, capital gains, and rental income (unless you are a real estate professional actively managing properties).
-
Pensions and annuities: Payments from retirement plans like 401(k)s, IRAs, and traditional pensions.
-
Government benefits: Other government payments like veterans’ benefits.
This distinction offers a significant opportunity for retirees to supplement their income without triggering the earnings test. If you have assets that generate passive income, such as a diversified investment portfolio, rental properties, or even royalties from past work, these income streams will not affect your Social Security benefits. Exploring or expanding these types of income sources can be an excellent strategy for increasing your overall financial security without penalty. For self-employment, while net earnings from self-employment are subject to the earnings test, careful structuring of a business can sometimes differentiate between active earned income and passive business income.
Consulting a Financial Advisor
The interplay between working income, Social Security benefits, tax implications, and investment strategies can be incredibly complex. What works best for one individual may not be suitable for another, given differing financial situations, health statuses, family needs, and personal goals. Therefore, consulting a qualified financial advisor specializing in retirement planning is highly recommended.
A financial advisor can help you:
-
Project your Social Security benefits under various claiming scenarios.
-
Analyze the impact of different levels of earned income on your benefits and taxes.
-
Develop a comprehensive retirement income strategy that integrates your work plans, investments, and Social Security.
-
Advise on tax-efficient strategies for drawing down assets and managing income.
Their expertise can provide clarity, help you avoid costly mistakes, and ensure you are maximizing your financial resources throughout your retirement years.
Common Misconceptions and Key Takeaways
The topic of working while receiving Social Security is often surrounded by misconceptions that can lead to suboptimal financial decisions. Dispelling these myths and reinforcing key principles is essential for sound retirement planning.
“Working Means Losing All Benefits”
One of the most prevalent myths is that if you work while on Social Security, you will lose all of your benefits. This is largely untrue. As detailed, the earnings test only applies if you are below your Full Retirement Age (FRA) and earn above specific annual limits. Even then, benefits are withheld, not completely lost, at a rate of $1 for every $2 or $3 earned over the limit. Once you reach your FRA, there is no earnings limit whatsoever, meaning you can earn an unlimited amount without any reduction to your Social Security benefits. The benefits that are withheld before FRA are also typically repaid in the form of a higher monthly benefit after you reach your FRA. Understanding the nuances of the earnings test can alleviate fears and enable more informed choices about continuing work.
Provisional Income and Taxes
Another critical point often misunderstood is the taxation of Social Security benefits. Many believe their benefits are entirely tax-free. However, as discussed, a significant portion of Social Security benefits can become taxable at the federal level if your provisional income—which includes your earned income—exceeds certain thresholds. This means that earning more from work can not only potentially reduce your current benefits (if below FRA) but can also make a larger portion of your remaining benefits subject to federal income tax. This dual impact can substantially reduce your net take-home income. It’s crucial for financial planning to factor in the potential for increased tax liability on both your earned income and your Social Security benefits. State income taxes on Social Security also vary, adding another layer of complexity.
The Importance of Planning
Ultimately, the most significant takeaway for anyone considering working while on Social Security is the absolute necessity of proactive and comprehensive financial planning. Relying on assumptions or incomplete information can lead to unexpected reductions in benefits, higher tax burdens, or missed opportunities for maximizing lifetime income.
Key aspects of planning should include:
-
Understanding your Full Retirement Age (FRA): This is the pivot point for the earnings test.
-
Estimating future earnings: Project how much you realistically expect to earn from work each year.
-
Reviewing your Social Security statement: Regularly check your earnings record and benefit estimates.
-
Considering various claiming strategies: Analyze the trade-offs of claiming early, at FRA, or delaying until age 70.
-
Assessing your overall financial picture: Look at all sources of income, expenses, assets, and liabilities.
-
Consulting professionals: Engage with financial advisors and tax experts who can provide personalized guidance tailored to your unique situation.
By taking a thoughtful and strategic approach, individuals can successfully integrate continued work into their retirement plans, maximizing their income and securing a more stable financial future while navigating the intricacies of Social Security regulations.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.