
Chase is widely regarded as the premier issuer for rewards enthusiasts, travel hackers, and small business owners alike. Between the lucrative Ultimate Rewards ecosystem and a robust lineup of co-branded partner cards, it is natural to wonder how many of these powerful financial tools one can carry at a single time. However, unlike some issuers that impose a hard cap on the number of physical cards you can hold, Chase utilizes a more nuanced set of rules based on your credit history, your total credit exposure, and specific product family restrictions.
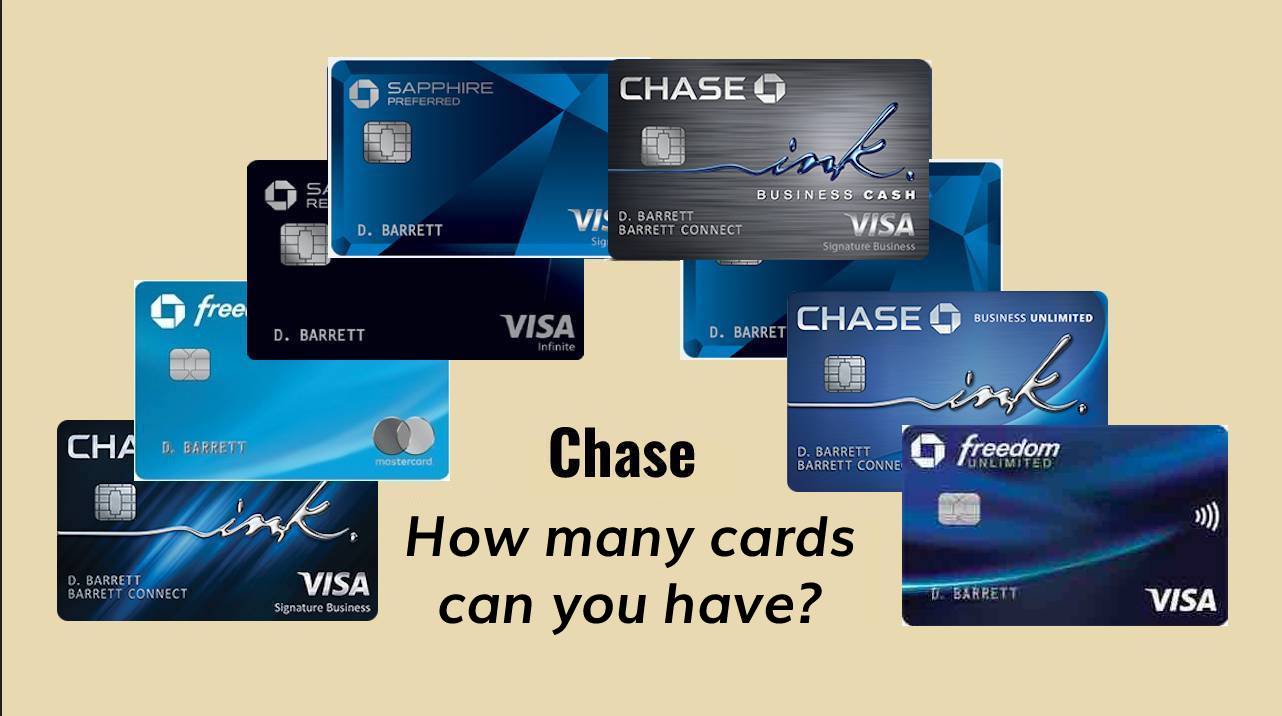
Understanding these internal policies is essential for anyone looking to build a “Chase Trifecta” or maximize their points-earning potential. While there is no official number published by Chase, the practical limit is dictated by a combination of the infamous 5/24 rule, total credit limits relative to income, and product-specific eligibility requirements.
The Foundation: Understanding the 5/24 Rule
Before counting your current cards or planning your next application, you must understand the “5/24 rule.” This is the single most important hurdle in the Chase ecosystem. Although Chase does not officially market this policy, it is a well-documented internal standard used to evaluate the risk of “credit churning.”
What is the 5/24 Rule?
The 5/24 rule states that if you have opened five or more personal credit accounts with any issuer (not just Chase) within the last 24 months, you will almost certainly be denied for a new Chase card. This includes everything from a new store card at a department store to a premium travel card from a competitor. Chase views high-velocity borrowing as a risk factor, regardless of your credit score or income level.
How it Impacts Your Total Card Count
Because of this rule, your ability to acquire new Chase cards is limited by your overall activity in the credit market. If you have been aggressive in opening accounts elsewhere, you may find yourself locked out of the Chase ecosystem for months or even years. This is why many financial experts suggest “starting with Chase” when beginning a credit rewards journey. Once you exceed that five-card threshold across the board, you lose the opportunity to add Chase products until your oldest accounts fall outside the two-year window.
The Role of Business Cards in 5/24
Interestingly, most Chase business cards do not add to your 5/24 count because they do not appear on your personal credit report. However, you generally must be under 5/24 to be approved for them in the first place. This creates a strategic advantage: you can apply for several Chase Ink business cards without increasing your 5/24 status, allowing you to keep your personal slots open for other products.
Total Credit Exposure vs. Number of Cards
While some issuers like American Express have historically limited users to a specific number of credit cards (such as five), Chase focuses more on the “Total Credit Exposure.” This refers to the cumulative dollar amount of credit Chase is willing to extend to you across all your accounts.
The Income-to-Credit Ratio
Chase typically limits your total credit line across all cards to approximately 40% to 50% of your reported annual income. For example, if you earn $100,000 per year, Chase may be comfortable giving you a total of $50,000 in credit. Whether that $50,000 is spread across two cards with $25,000 limits or ten cards with $5,000 limits is, to a certain extent, up to you.
Reallocating Credit for New Approvals
If you reach your maximum credit exposure with Chase, they may deny your application for a new card—not because you have too many cards, but because they aren’t willing to lend you more money. In these instances, a “reconsideration” phone call can be highly effective. You can often ask a representative to shift a portion of the credit limit from an existing card to the new one to facilitate the approval. By doing this, many users have successfully held 10 or more Chase cards simultaneously.
The 2/30 Rule
Another temporal limit to keep in mind is the 2/30 rule. Generally, Chase will only approve a maximum of two credit card applications within a 30-day window. If you attempt to open three cards in a single month, the third is almost guaranteed to be an automatic rejection. This ensures that you aren’t rapidly accumulating debt in a way that signals financial distress.
Product Family Restrictions
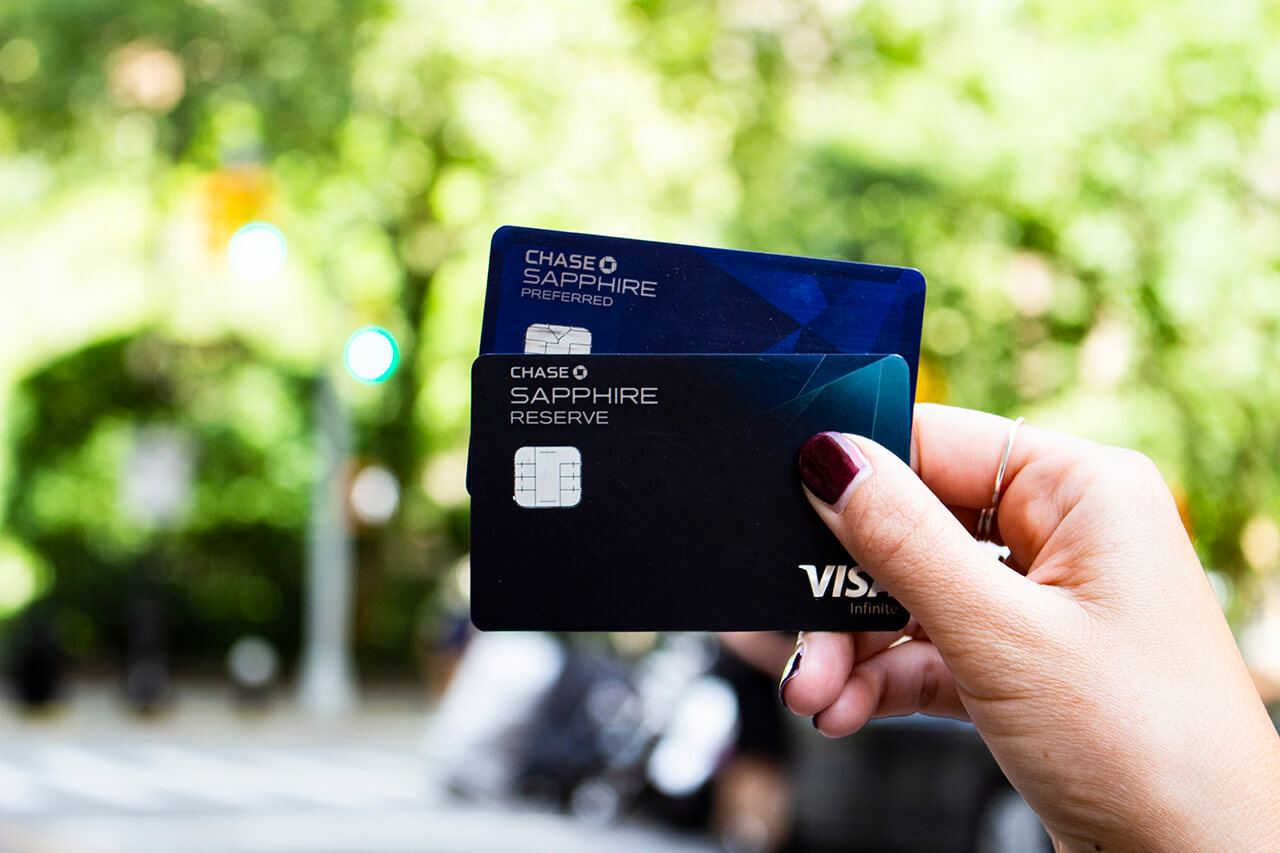
Even if you are under 5/24 and have plenty of room in your total credit exposure, Chase has “one-per-family” rules that prevent you from holding multiple versions of similar cards.
The Sapphire Rule
The most famous of these is the Sapphire rule. You can only hold one Sapphire card at a time—either the Sapphire Preferred or the Sapphire Reserve. Furthermore, you are ineligible for a new-user sign-up bonus on any Sapphire card if you have received a Sapphire bonus in the last 48 months. If you currently hold a Sapphire Preferred and want a Reserve, you cannot simply apply for the second one; you must either upgrade your existing card or downgrade it to a “freedom” product before applying (provided you are outside the 48-month window).
Southwest Airlines and United Restrictions
Similar rules apply to co-branded partners. For the Southwest Rapid Rewards personal cards, you can typically only hold one at a time and cannot receive a new bonus if you’ve received one in the last 24 months. However, this rule usually does not apply to the business versions of these cards, allowing you to hold one personal and one business Southwest card simultaneously—a popular strategy for earning the Southwest Companion Pass.
The Freedom Ecosystem
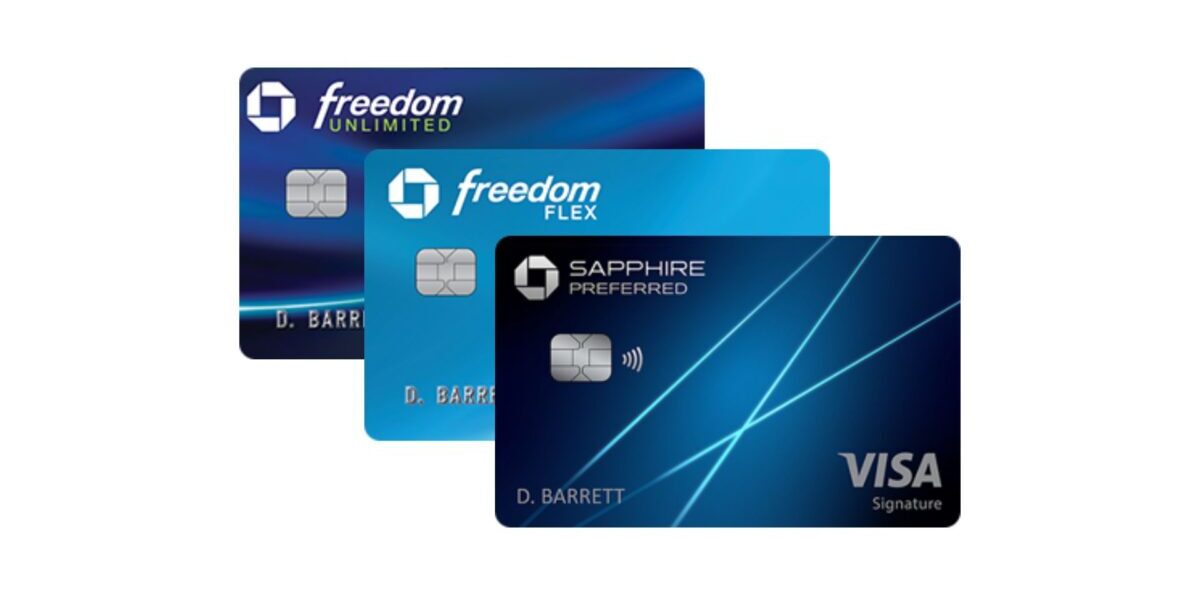
The Chase Freedom family, which includes the Freedom Flex and the Freedom Unlimited, is more flexible. It is common for users to hold both, and in some cases, multiple versions of the same card if they have performed “product changes” over the years. These cards are the backbone of the “Chase Trifecta,” which usually consists of one Sapphire card for transfers and two Freedom cards for categorized spending.
Strategies for Building Your Chase Portfolio
Since the number of cards you can have is functionally limited by 5/24 and total exposure, strategy becomes paramount. You want every slot to count toward your specific financial goals, whether that is cash back or luxury travel.
Prioritize High-Value Cards Early
Because of 5/24, you should prioritize Chase cards that offer the highest utility or sign-up bonuses before looking at other issuers. The Sapphire Preferred or Reserve should usually be the anchor of your portfolio, followed by the Freedom Unlimited for its baseline earning rate on non-category spend.
Leveraging Business Entities
If you have any form of side income—freelancing, selling on eBay, or consulting—you may qualify for Chase Ink business cards. As mentioned, these cards are vital for those who want to hold a large number of Chase cards. Because they don’t count toward your 5/24 total, they allow you to expand your points-earning potential without “using up” your personal slots. Many power users hold three or four different business cards alongside their personal ones.
Monitoring Your “Velocity”
While the 2/30 rule is the hard limit, it is generally recommended to wait at least 90 days between Chase applications. Applying too quickly can trigger a manual review of your accounts. Chase values long-term relationships; showing a pattern of steady, responsible card usage over years makes them much more likely to approve your 10th or 12th card.
Long-Term Management and Maintenance
Having a large number of Chase cards requires diligent management. If you hold ten cards, you are managing ten different payment cycles and potentially several different annual fees.
The No-Annual-Fee “Sock Drawer” Strategy
If you have an old Chase card that you no longer use, but it has no annual fee (like the Freedom Flex), it is almost always better to keep it open. This increases your total credit limit and the average age of your accounts, both of which help your credit score. If a card has an annual fee that you no longer find valuable, consider “downgrading” it to a no-fee version rather than closing it. This preserves your relationship with Chase and keeps your total credit exposure intact.
Annual Fee Justification
For cards with high annual fees, such as the Sapphire Reserve or the United Club Infinite, you must perform an annual audit. Does the travel credit, lounge access, or point multiplier outweigh the cost? Because Chase limits your “slots” via 5/24, you don’t want to waste a position on a card that isn’t providing a clear return on investment.
Conclusion: The Practical Limit
So, how many Chase credit cards can you have? For most disciplined consumers, the answer is as many as your income and 5/24 status allow. There are documented cases of individuals holding 10 to 15 Chase cards by carefully navigating the 5/24 rule, utilizing business cards to stay under the limit, and calling the reconsideration line to shift credit limits when they hit their ceiling.
By treating your Chase applications as a marathon rather than a sprint, and by understanding the internal logic of credit exposure and product families, you can build a comprehensive portfolio that serves every aspect of your financial life. Focus on the rules, respect the velocity limits, and prioritize the cards that offer the most value to your specific spending habits.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.