
The allure of the silver screen is often inextricably linked with the tantalizing aroma of freshly popped corn. For many, a movie experience feels incomplete without a generous bucket of theater popcorn, often oversized, buttery, and seemingly bottomless. Yet, beyond the immediate indulgence and the ticket price, lies a more subtle, often overlooked financial equation. We frequently dissect our budgets for housing, transportation, and investments, but how often do we consider the financial ripple effects of our discretionary food choices, particularly those laden with carbohydrates and calories? This article delves into how a seemingly simple question – “how many carbs in theater popcorn?” – opens a broader dialogue about personal finance, health expenditures, and the smart allocation of our hard-earned money.
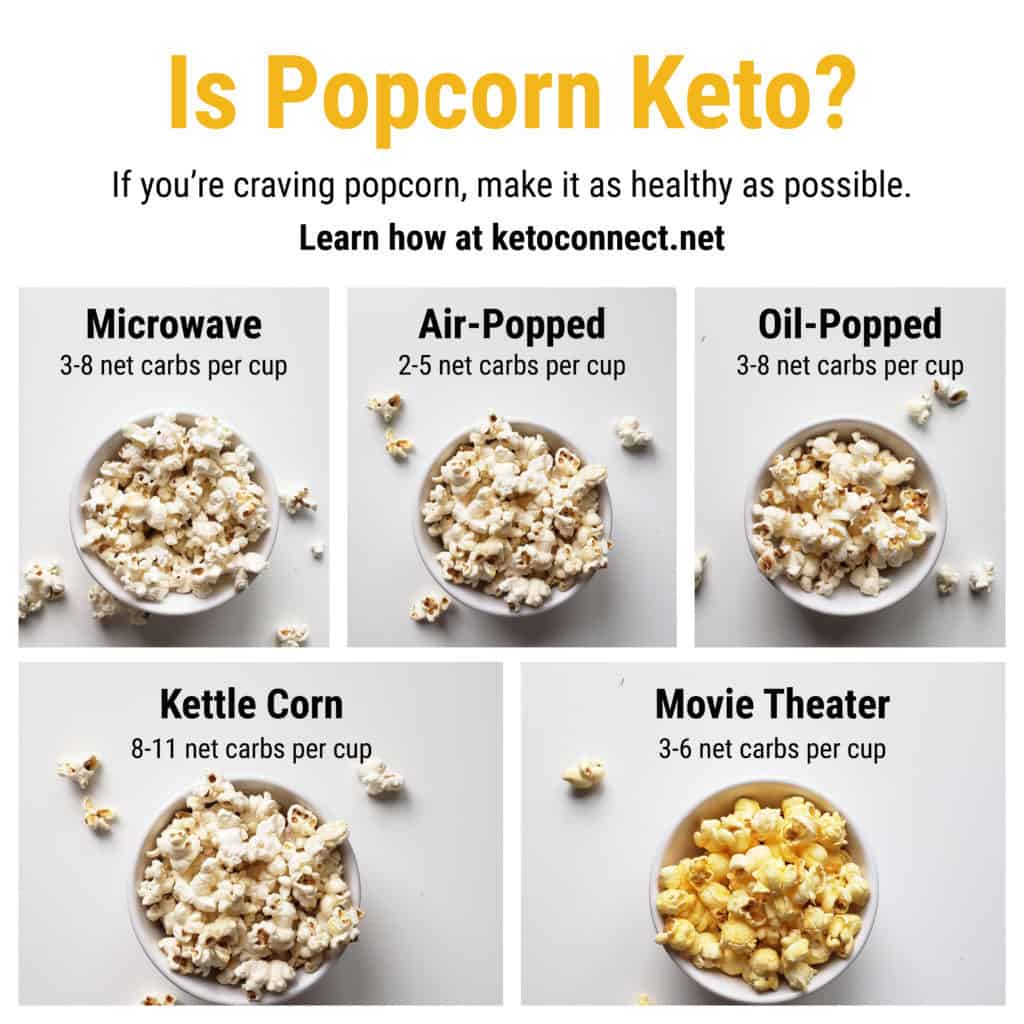
In an age where health consciousness is on the rise and personal finance literacy is more crucial than ever, understanding the interplay between our dietary habits and our financial health is paramount. Theater popcorn, a common pleasure, serves as an excellent case study to illustrate how everyday consumption choices, influenced by nutritional content, can have tangible and intangible financial consequences that extend far beyond the initial purchase.
Beyond the Ticket Price: The Real Cost of Indulgence
When we shell out money for a large popcorn at the cinema, we’re often focused on the immediate gratification and the entertainment value. However, a deeper financial analysis reveals that the transaction is rarely as simple as dollar for kernel. The true cost of that salty, buttery treat stretches into various facets of our personal finance, from direct expenditure to potential future health liabilities.
The Immediate Transaction: Popcorn’s Price Tag
Let’s start with the obvious: the upfront cost. Theater popcorn, notoriously, is marked up significantly. A large popcorn can easily cost upwards of $8-$12, sometimes even more than the movie ticket itself, especially when bundled with a drink. While this might seem like a minor expense in isolation, consider the cumulative effect. If you’re a regular moviegoer, attending once or twice a month, this discretionary spending can amount to hundreds of dollars annually. For a single individual, that could be a significant contribution to an emergency fund, a small investment, or even a down payment on a valuable financial tool. For a family, these costs multiply quickly, carving out a substantial chunk of the entertainment budget that could potentially be reallocated to more impactful financial goals.
Moreover, the size of these portions is often deceiving. A “large” popcorn can contain 10-20 cups of popped corn, an amount far exceeding a reasonable serving size for an individual. This contributes to overconsumption, not just of the snack itself, but of the associated financial outlay. Are we truly getting value for money when we consume far more than we need or even truly want, simply because it’s available in an oversized container?
Nutritional Neglect: A Down Payment on Future Health Bills
Here’s where the “carbs” in “how many carbs in theater popcorn” become particularly relevant to personal finance. Theater popcorn, especially the heavily buttered varieties, is not just high in carbohydrates; it’s often packed with saturated fats, trans fats (if made with hydrogenated oils, though less common now), sodium, and a considerable amount of calories. A large popcorn can contain anywhere from 1,000 to over 1,200 calories and well over 100 grams of carbohydrates, sometimes rivaling the caloric intake of entire meals.
Regular consumption of high-carb, high-fat, high-sodium foods, often characterized as “empty calories” due to their low nutritional density, contributes to a range of health issues. These include weight gain, increased risk of type 2 diabetes, cardiovascular diseases, and high blood pressure. Each of these conditions carries a substantial financial burden. Medical expenses – doctor visits, prescriptions, specialized treatments, hospital stays – can quickly decimate savings, rack up debt, and increase insurance premiums. Even seemingly small health issues can lead to lost workdays, impacting income and productivity. Thus, prioritizing immediate gratification through nutritionally poor choices can be seen as making a “down payment” on future, potentially crippling, health bills. From a financial planning perspective, investing in preventative health through mindful dietary choices is a far more prudent strategy than repeatedly funding indulgent, health-detrimental habits.
Opportunity Cost: What Else Could Your Snack Money Buy?
Every dollar spent on theater popcorn is a dollar that cannot be spent or saved elsewhere. This concept, known as opportunity cost, is central to sound financial decision-making. That $10 for a large popcorn might seem trivial, but what if it were consistently diverted?
-
Savings and Investments: Over a year, $10 twice a month is $240. Invested in a low-cost index fund with an average annual return, that amount could grow significantly over decades, contributing to retirement savings, a down payment on a home, or a child’s education fund.
-
Debt Reduction: For those carrying credit card debt, that $10 could make an additional payment, reducing the principal and saving on interest charges over time.
-
Emergency Fund: Building a robust emergency fund is a cornerstone of financial security. Consistently redirecting discretionary spending like popcorn money can expedite this crucial safety net.
-
Healthier Alternatives: The same $10 could purchase a week’s worth of fresh fruits or vegetables, a healthy ingredient for home-cooked meals, or a subscription to a fitness app, all of which contribute positively to long-term health and, by extension, financial resilience.
Understanding the opportunity cost forces us to evaluate our spending habits not just in terms of what we gain, but what we forfeit. Is the fleeting pleasure of theater popcorn worth the missed opportunity for greater financial security or better health outcomes?
The Financial Equation of Dietary Choices: Carbs, Calories, and Cash Flow
Our bodies are complex machines, and the fuel we provide them directly impacts their performance. This analogy extends to our financial lives, where dietary choices can significantly influence our cash flow, productivity, and overall economic stability.
Understanding Macronutrients: More Than Just a Number
While the specific number of carbs in theater popcorn isn’t the primary focus of a financial discussion, understanding what macronutrients are and their general impact is crucial. Carbohydrates are one of three macronutrients (along with fats and proteins) that provide energy. Different types of carbs have different effects: complex carbohydrates (like those in whole grains) provide sustained energy, while simple carbohydrates (like those in sugary drinks or refined snacks) offer a quick burst followed by a crash. Theater popcorn, especially when loaded with butter and seasonings, often falls into the latter category in terms of its glycemic impact due to the refined nature of the corn and added sugars/fats.
From a financial perspective, consuming an abundance of simple, quickly digested carbohydrates can lead to energy fluctuations, impacting focus and productivity during work hours or other financially important activities. If your energy levels are inconsistent due to a poor diet, your ability to perform optimally, seek new opportunities, or even manage your finances effectively can be compromised.
The “Empty Calorie” Trap: Fueling Your Body vs. Draining Your Wallet
Empty calories are those that provide significant caloric energy but lack essential vitamins, minerals, fiber, and other beneficial nutrients. Theater popcorn, especially without its hull (which provides fiber) and doused in artificial butter, often fits this description. These foods offer little in terms of nutritional return on investment.
Financially, the “empty calorie” trap is insidious. We spend money on items that provide fleeting satisfaction but offer no lasting benefit for our health or, consequently, our long-term financial stability. It’s akin to constantly refueling your car with low-octane, dirty fuel – it might run for a bit, but performance will suffer, and maintenance costs will inevitably rise. The money spent on nutritionally void foods could be reallocated to nutrient-dense options that genuinely fuel the body, support cognitive function, and contribute to sustained energy levels, thereby enhancing productivity and reducing the likelihood of future health-related financial drains. This isn’t about deprivation, but about optimization – getting more nutritional and financial value for every dollar spent on food.
The Ripple Effect: How Diet Impacts Productivity and Earning Potential
A healthy diet is directly correlated with better physical and mental health. Individuals who maintain a balanced diet often experience higher energy levels, improved concentration, reduced stress, and fewer instances of illness. These factors have a direct bearing on earning potential and financial resilience:

-
Work Performance: Sustained energy and cognitive function translate to better work performance, which can lead to promotions, raises, and new career opportunities.
-
Reduced Sick Days: A strong immune system, bolstered by good nutrition, means fewer sick days, which can prevent lost wages, especially for hourly workers or the self-employed.
-
Entrepreneurial Drive: Maintaining high energy and mental clarity is crucial for entrepreneurs and those pursuing side hustles, where self-discipline and sustained effort directly impact income generation.
-
Healthcare Savings: As discussed, a healthy lifestyle significantly reduces the likelihood and severity of chronic diseases, leading to lower out-of-pocket medical expenses, lower insurance premiums over time, and a reduced reliance on expensive medications.
In essence, every dietary choice, including opting for that high-carb, high-fat theater popcorn, contributes to a larger financial narrative. It’s an investment or a disinvestment in our human capital – our health and ability to generate wealth.
Budgeting for Wellness: Integrating Health into Your Financial Plan
A holistic financial plan isn’t just about managing assets and liabilities; it’s about managing your entire life, including your most valuable asset: your health. Integrating wellness into your financial strategy means making conscious choices that support both your physical well-being and your economic stability.
Prioritizing Preventative Health: An Investment, Not an Expense
Thinking of preventative health as an investment fundamentally shifts perspective. Instead of viewing healthy eating, regular exercise, and routine check-ups as expenses, consider them as premium payments on a long-term health insurance policy that minimizes future catastrophic financial outlays. Allocating a portion of your budget to high-quality, nutritious food, even if it seems more expensive upfront than processed alternatives, often pays dividends in reduced medical costs, increased productivity, and a higher quality of life.
When planning your personal finances, dedicate a line item to “wellness” or “health investment.” This could include funds for healthy groceries, a gym membership, or even educational resources on nutrition. By proactively investing in your health, you are safeguarding your financial future against the unforeseen and often exorbitant costs of illness.
Smart Snacking Strategies: Saving Dollars and Carbs
The solution isn’t to abstain from all treats forever but to approach indulgence strategically. For cinema visits, this means adopting smarter snacking habits that align with both health and financial goals.
-
Bring Your Own: Many cinemas allow patrons to bring in outside snacks, or at least a water bottle. Packing your own portion-controlled, healthier alternatives like air-popped popcorn (made at home with minimal oil and salt), trail mix, fruit, or vegetable sticks can save significant money and significantly reduce your intake of unhealthy carbs, fats, and sodium.
-
Share Portions: If you must have theater popcorn, consider splitting a small or medium size among several people. This drastically cuts down on individual consumption and cost.
-
Limit Frequency: Make theater popcorn an occasional treat rather than a default. Enjoy it mindfully, savoring the experience rather than mindlessly consuming an entire large bucket.
-
Choose Wisely: Opt for plain popcorn if available, and add your own seasonings from home (if permitted) to control sodium and fat content.
These strategies not only save money directly but also promote healthier eating habits that can have positive long-term financial benefits. It’s about conscious consumption rather than impulsive spending.
Reallocating Entertainment Budgets for Long-Term Gain
Instead of allowing your entertainment budget to be passively consumed by overpriced, unhealthy cinema snacks, actively reallocate those funds towards activities or purchases that provide greater value.
-
Experiences Over Consumption: Shift focus from consuming goods (like massive popcorn buckets) to experiencing activities. Perhaps use the saved money to attend a different type of performance, visit a museum, or take a short trip – experiences often provide richer memories and greater personal growth.
-
Skill Development: Invest in a course, a workshop, or a book that enhances a skill, potentially leading to increased earning potential or new hobbies.
-
Health and Fitness Investments: Direct savings towards a new pair of running shoes, a yoga class, or equipment for a home gym.
-
Financial Growth: Most importantly, consistently redirect a portion of these savings into a high-yield savings account, an investment portfolio, or towards paying down high-interest debt. This transforms a fleeting indulgence into a tangible step towards financial independence.
By making deliberate choices about where our entertainment dollars go, we transform passive spending into active financial planning.
Making Informed Choices: A Financial Lens on Lifestyle
Ultimately, the question of “how many carbs in theater popcorn” is a microcosm of a larger financial principle: the power of informed decision-making. Every choice we make, particularly those related to our health and spending, has a financial consequence, whether immediate or delayed.
The Power of Knowledge: Reading Between the Nutritional Lines
Ignorance is not bliss when it comes to personal finance or personal health. Knowing the approximate nutritional content of common foods, especially those consumed regularly or in large portions, empowers us to make healthier and more financially savvy choices. This doesn’t mean obsessively counting every carb, but having a general awareness. When you know that a large theater popcorn can contain over 1000 calories and 100+ grams of carbs, you can better weigh that against its monetary cost and its potential impact on your health goals and budget. This knowledge enables you to identify “financial and nutritional traps” and navigate them wisely.
Home vs. Out-of-Home Consumption: A Cost-Benefit Analysis
A significant factor in the cost and nutritional profile of food is whether it’s prepared at home or consumed out-of-home. Preparing food at home almost always offers greater control over ingredients, portion sizes, and cost. Theater popcorn serves as a prime example: the cost of unpopped kernels is negligible compared to the cinema price, and you can control the type and amount of oil, butter, and salt used. This principle applies to many other food items as well. Regularly dining out or relying on convenience foods often comes with a higher financial cost and a less healthy nutritional profile. A mindful financial approach encourages a greater emphasis on home preparation, allowing for better budget control and superior health outcomes.

The ROI of Healthy Habits: A Lifetime of Financial Resilience
The Return on Investment (ROI) for healthy habits, while not always immediately quantifiable in monetary terms, is profound and long-lasting. A commitment to a balanced diet, regular physical activity, and preventative care translates into:
-
Reduced Medical Expenses: Fewer doctor visits, prescriptions, and complex medical procedures.
-
Increased Productivity and Earning Capacity: More energy, better focus, and fewer sick days.
-
Greater Longevity and Quality of Life: Enjoying a longer, healthier life allows for more years to save, invest, and experience life without the burden of chronic illness.
-
Peace of Mind: The financial security that comes from knowing you are actively managing your health and resources is invaluable.
In conclusion, the simple question of “how many carbs in theater popcorn” unravels a complex web of financial implications. It highlights how seemingly small, discretionary choices can accumulate into significant financial outcomes, impacting everything from immediate budgets to long-term health and wealth. By adopting a professional, insightful, and engaging approach to understanding the financial costs of our dietary decisions, we can transform passive consumption into an active strategy for building a more resilient and prosperous financial future. The next time you consider that bucket of popcorn, remember: you’re not just paying for a snack; you’re making an investment, and like all investments, it’s worth scrutinizing its true return.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.