
Understanding your yearly income is not merely a theoretical exercise; it is the bedrock of sound financial management, strategic planning, and overall economic well-being. Whether you are an individual employee, a freelancer, a small business owner, or an investor, accurately figuring out your annual earnings empowers you to make informed decisions about budgeting, taxes, investments, and future aspirations. This comprehensive guide will walk you through the various components of yearly income, methods for calculation, and why this metric is crucial for achieving your financial goals.
The Fundamentals: Defining Your Gross Yearly Income
Gross yearly income represents the total amount of money you earn from all sources before any deductions, taxes, or expenses are taken out. It’s the “top line” number that paints the broadest picture of your earning capacity. The method for calculating it varies significantly based on your employment status.
For Salaried Employees: The Simplest Calculation
For individuals receiving a fixed annual salary, calculating gross yearly income is typically the most straightforward. It is simply the agreed-upon annual sum your employer pays you for your work.
-
Base Salary: Your primary compensation.
-
Bonuses: Performance-based, holiday, or retention bonuses should be included in the year they are received.
-
Commissions: If your role includes sales or performance-based commissions, these are added to your base salary.
-
Overtime Pay: While salaried employees are often exempt from overtime, some roles may still offer it; this should be included.
Example: If your annual salary is $60,000 and you received a $5,000 bonus and $2,000 in commissions, your gross yearly income from this employer would be $67,000.
For Hourly Workers: Time Tracking and Overtime
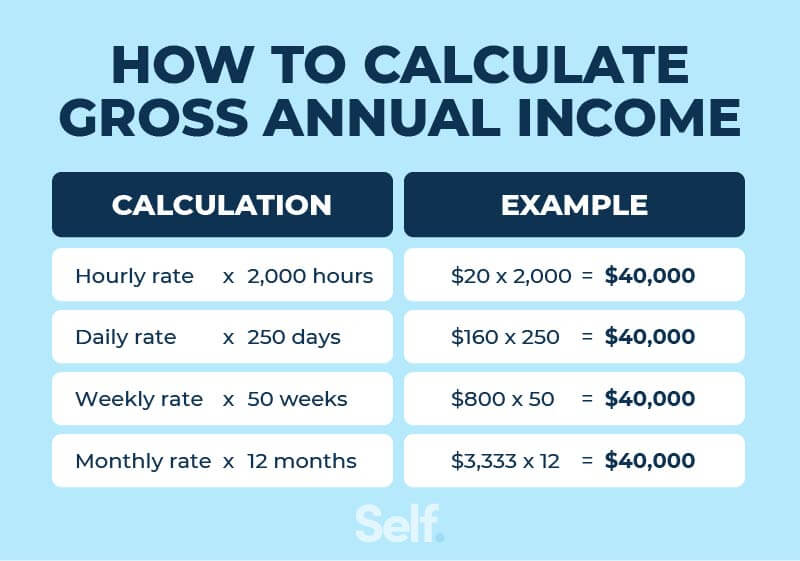
Hourly workers need to meticulously track their hours. Their gross yearly income is calculated by multiplying their hourly rate by the total hours worked throughout the year.
-
Regular Hours: (Hourly Rate x Total Regular Hours Worked Annually).
-
Overtime Hours: (Overtime Rate x Total Overtime Hours Worked Annually). Remember that overtime is often paid at 1.5 times the regular rate (or more, depending on local laws).
-
Holiday Pay/Shift Differentials: Any additional pay for working holidays or less desirable shifts should be factored in.
Example: If you earn $20/hour, work 40 regular hours a week for 52 weeks, and also worked 100 hours of overtime at time-and-a-half ($30/hour) throughout the year, your gross yearly income would be ($20 * 40 * 52) + ($30 * 100) = $41,600 + $3,000 = $44,600.
For Freelancers and Gig Workers: Variability and Invoicing
Freelancers, independent contractors, and gig workers typically have the most variable income. Their gross yearly income is the sum of all payments received from clients or platforms over the year.
-
Track All Invoices: Keep a detailed record of every invoice issued and payment received.
-
Payment Platforms: Consolidate income data from platforms like Upwork, Fiverr, Etsy, Uber, Lyft, etc.
-
Direct Payments: Include any direct payments from clients for services rendered.
-
Before Expenses: Remember this is gross income, so do not subtract business expenses at this stage, as they come into play for net income and taxable income.
This requires diligent record-keeping, often utilizing spreadsheets or specialized accounting software.
For Business Owners: Revenue Minus Cost of Goods Sold (COGS)
For business owners, defining “yearly income” can be more complex, as it involves distinguishing between business revenue and personal income.
-
Sole Proprietors/Single-Member LLCs: Your gross business revenue minus your Cost of Goods Sold (COGS) is often considered your gross income before operating expenses. Your personal yearly income often aligns closely with your business’s net profit (after all expenses, before owner’s draw/salary), from which you draw personal funds.
-
Partnerships/Multi-Member LLCs: Your personal yearly income will be based on your share of the business’s profits (owner’s draw or distribution).
-
S-Corps/C-Corps: Owners typically pay themselves a salary (which falls under the salaried employee calculation) and may also receive dividends or distributions from profits.
It’s crucial for business owners to maintain separate personal and business finances and consult with an accountant to properly structure their income.
Beyond Wages: Incorporating All Income Streams
Most people have multiple sources of income beyond their primary job or business. To accurately figure out your yearly income, you must cast a wider net and include all financial inflows.
Investment Income
Income generated from investments can significantly boost your overall yearly earnings.
-
Dividends: Payments from stocks or mutual funds you own.
-
Interest: Earnings from savings accounts, bonds, Certificates of Deposit (CDs), or peer-to-peer lending.
-
Capital Gains: Profits from selling assets like stocks, real estate, or other investments for more than you paid for them. Only realized gains (assets sold) count.
-
Rental Income: Gross rental receipts from properties you own, before deducting expenses like mortgage interest, property taxes, or maintenance.
Side Hustles and Passive Income
The rise of the gig economy and digital platforms has made side hustles and passive income streams increasingly common.
-
Freelance Work/Consulting: Any income earned outside your primary job.
-
Online Sales: Earnings from selling products on platforms like eBay, Amazon FBA, or your own e-commerce store.
-
Content Creation: Ad revenue, sponsorships, or royalties from blogs, YouTube channels, podcasts, or digital products.
-
Royalties: Income from intellectual property such as books, music, or patents.
-
Affiliate Marketing: Commissions earned by promoting other companies’ products.
Benefits and Other Income
Various government benefits, personal support payments, and other miscellaneous sources also contribute to your yearly income.
-
Unemployment Benefits: Payments received during periods of unemployment.
-
Disability Payments: Income from short-term or long-term disability insurance.
-
Social Security Benefits: Retirement, disability, or survivor benefits from Social Security.
-
Alimony/Child Support: Payments received from a former spouse or parent.
-
Pensions and Retirement Withdrawals: Income from pension plans or distributions from retirement accounts (e.g., 401k, IRA).
It is essential to include all these streams to get a complete picture of your total financial inflow for the year.
Calculating Your Net Yearly Income: The True Take-Home
While gross income is important for assessing earning potential, net yearly income, or “take-home pay,” is what you actually have available to spend, save, and invest after all deductions. This figure is crucial for budgeting and day-to-day financial management.

Understanding Deductions and Withholdings
Numerous deductions can reduce your gross income to your net income. These typically fall into two categories: pre-tax deductions and post-tax deductions.
-
Federal, State, and Local Income Taxes: The largest chunk for most people, withheld based on your W-4 elections.
-
FICA Taxes: Social Security and Medicare taxes, mandatory for most employees.
-
Health Insurance Premiums: Your share of health, dental, and vision insurance costs.
-
Retirement Contributions: Deductions for 401(k), 403(b), or other employer-sponsored retirement plans.
-
Other Pre-Tax Deductions: Contributions to Health Savings Accounts (HSAs), Flexible Spending Accounts (FSAs), commuter benefits, or dependent care accounts. These reduce your taxable income.
-
Post-Tax Deductions: Union dues, charitable contributions, or specific insurance premiums that are taken out after taxes.
The Importance of the Pay Stub and Tax Documents
Your pay stub is a detailed record of your gross pay, deductions, and net pay for each pay period. Reviewing it regularly helps you understand how your income is being distributed.
-
W-2 Form: Issued by employers, this year-end summary provides your total gross wages, taxable wages, and all federal, state, and local taxes withheld. This is the primary document for employees.
-
1099-MISC / 1099-NEC Forms: For freelancers and independent contractors, these forms report non-employee compensation received from clients.
-
1099-INT / 1099-DIV / 1099-B Forms: Report interest, dividends, and proceeds from broker and barter exchange transactions (investment sales).
-
Schedule K-1: For partners in a partnership or shareholders in an S-Corp, reporting your share of the business’s income, deductions, and credits.
These documents are essential for accurately calculating your net income for the year and filing your tax returns.
Estimating for Self-Employed Individuals
Self-employed individuals face unique challenges in calculating net income due to the absence of an employer to withhold taxes.
-
Self-Employment Tax: You are responsible for both the employer and employee portions of Social Security and Medicare taxes (currently 15.3% on net earnings up to a certain limit).
-
Business Deductions: You can deduct eligible business expenses (e.g., home office, supplies, software, mileage, insurance, professional development) to reduce your net taxable income.
-
Quarterly Estimated Tax Payments: To avoid penalties, self-employed individuals typically pay estimated taxes to the IRS quarterly throughout the year. This requires accurately forecasting your gross income and deductible expenses.
Why Accurate Income Calculation Is Crucial for Financial Health
Beyond tax compliance, a precise understanding of your yearly income offers profound benefits for your overall financial health and future planning.
Budgeting and Financial Planning
Knowing your net yearly income is the foundation for creating a realistic budget.
-
Setting Spending Limits: You can allocate funds effectively across categories like housing, food, transportation, and entertainment.
-
Saving Goals: Determine how much you can realistically save for emergencies, retirement, a down payment on a home, or other major purchases.
-
Debt Repayment: Assess your capacity to pay down existing debts efficiently.
Without this clarity, budgeting becomes guesswork, often leading to overspending or under-saving.
Tax Compliance and Optimization
Accurate income figures are non-negotiable for tax purposes.
-
Avoiding Penalties: Correctly reporting all income streams prevents underpayment penalties from the IRS or state tax authorities.
-
Identifying Deductions and Credits: A clear view of your income and expenses helps you identify all eligible tax deductions and credits, potentially reducing your overall tax liability.
-
Strategic Tax Planning: Understanding your income trajectory allows for proactive tax planning, such as maximizing retirement contributions or strategically timing asset sales.
Loan Applications and Creditworthiness
Financial institutions heavily rely on your declared yearly income when evaluating loan applications.
-
Debt-to-Income Ratio: Lenders use your income to calculate your debt-to-income (DTI) ratio, a key metric for determining your ability to manage monthly payments for mortgages, car loans, or personal loans.
-
Demonstrating Repayment Capacity: A stable and accurately reported income increases your credibility and trustworthiness as a borrower, often leading to better interest rates and loan terms.
Future Planning and Goal Setting
Your yearly income is a vital metric for long-term financial and career planning.
-
Career Advancement: It helps you evaluate job offers, negotiate salaries, and understand the financial impact of career changes.
-
Investment Strategies: Knowing your surplus income allows you to determine how much you can comfortably allocate to investments, accelerating your wealth accumulation.
-
Lifestyle Planning: It informs decisions about major life events, such as buying a home, starting a family, or planning for early retirement.
Tools and Best Practices for Tracking Your Income
Maintaining accurate records is paramount for figuring out your yearly income. Thankfully, a variety of tools and practices can simplify this process.
Manual Tracking: Spreadsheets and Notebooks
For those who prefer a hands-on approach, simple manual tracking can be effective.
-
Spreadsheets (Excel, Google Sheets): Create columns for Date, Income Source, Amount Received, Category (e.g., Salary, Freelance, Interest), and Notes. This offers flexibility and customization.
-
Physical Notebooks: A dedicated notebook can work for simple tracking, though it lacks the analytical capabilities of digital tools.
-
Pros: Free, customizable, provides a direct understanding of your money.
-
Cons: Time-consuming, prone to manual errors, less efficient for complex finances.
Digital Tools: Budgeting Apps and Software
Technology has revolutionized income tracking, offering convenience and automation.
-
Budgeting Apps (Mint, YNAB, Personal Capital): These apps link to your bank accounts and credit cards, automatically categorizing transactions and providing a real-time overview of your income and spending. Many offer income reporting features.
-
Personal Finance Software (Quicken): More robust software that can manage investments, create detailed reports, and even assist with tax preparation.
-
Accounting Software for Businesses (QuickBooks, Xero, FreshBooks): Essential for freelancers and business owners, these tools manage invoicing, expense tracking, payroll (if applicable), and generate profit & loss statements crucial for income calculation.
-
Pros: Automation, detailed reporting, convenience, error reduction, often accessible on multiple devices.
-
Cons: Monthly/annual fees for premium features, potential privacy concerns with linked accounts, a learning curve for advanced features.

Regular Review and Reconciliation
Regardless of the tools you use, consistent review and reconciliation are critical.
-
Monthly Checks: Compare your recorded income against bank statements and pay stubs to catch discrepancies early.
-
Quarterly Reviews: For variable income earners, a quarterly review helps adjust estimated tax payments and re-forecast annual income.
-
Yearly Reconciliation: Before tax season, conduct a thorough reconciliation of all income sources against official tax documents (W-2s, 1099s).
-
Organized Documentation: Keep all pay stubs, invoices, bank statements, and tax forms in a secure, organized manner (digitally or physically). This simplifies audits, tax filing, and overall financial management.
Figuring out your yearly income is more than just crunching numbers; it’s a fundamental step towards financial empowerment. By understanding where your money comes from, how it’s calculated, and its net impact, you gain the clarity and control needed to navigate your financial landscape with confidence, plan for the future, and achieve your personal and professional economic aspirations. Embrace the discipline of diligent tracking, and unlock the full potential of your earnings.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.