
In the world of personal finance, business, and investing, numbers tell a compelling story. Among these, percentages play a particularly crucial role, serving as a universal language for everything from interest rates and discounts to profit margins and market growth. Yet, for all their descriptive power, percentages often need to be translated into tangible, “whole number” values – actual dollars and cents – to make sense of our financial realities. Understanding how to accurately convert a percentage into a whole number is not just a mathematical exercise; it’s a fundamental skill that empowers individuals and businesses to make informed decisions, manage budgets effectively, and confidently navigate the complexities of the financial landscape.

This article delves into the indispensable skill of converting percentages to whole numbers, framing it strictly within the context of money. We’ll explore the ‘why’ and ‘how,’ providing clear methods and practical applications that directly impact your personal wealth, investment strategies, and everyday spending. By mastering this conversion, you’ll gain a deeper insight into your financial flows, making what often seems abstract feel concrete and manageable.
The Fundamentals: Understanding Percents and Whole Numbers in Finance
Before we dive into the mechanics of conversion, it’s vital to establish a clear understanding of what percentages and whole numbers represent in a financial context, and why their interplay is so critical. A solid foundation here will demystify the process and highlight its everyday relevance.
What is a Percent? Decoding its Financial Power
At its core, “percent” means “per hundred” or “out of one hundred.” It’s a way of expressing a part of a whole as a fraction of 100. In finance, percentages are powerful because they provide a standardized way to compare proportions and rates, regardless of the absolute values involved. For instance, a 5% interest rate on a loan is easily comparable, whether the loan is for $1,000 or $1,000,000. Similarly, a 20% discount signals the same proportionate saving, whether on a $50 item or a $500 item.
Percentages are ubiquitous:
-
Interest Rates: Savings accounts, loans, credit cards.
-
Discounts and Sales Tax: Retail transactions.
-
Investment Returns: Stock market gains, mutual fund performance.
-
Budgeting: Allocating a portion of income to savings or expenses.
-
Profit Margins: Business financial health.
-
Inflation: Erosion of purchasing power.
Without percentages, comparing financial performance or understanding relative changes would be cumbersome, requiring constant manipulation of large, disparate numbers.
The Significance of Whole Numbers in Monetary Values
While percentages offer comparison and insight, financial transactions ultimately boil down to whole numbers – the actual dollars, euros, yen, or pounds that change hands. When we talk about a “whole number” in finance, we’re typically referring to the specific monetary amount (e.g., $100, €50, £250). Even when dealing with cents, they are usually expressed as decimal parts of a whole number (e.g., $10.50), but the intent is to arrive at a precise, actionable monetary value.
The conversion from a percentage to a whole number is essentially about answering the question: “What actual amount does this percentage represent of a given total?” For example, if you see “20% off,” you don’t just want to know it’s a fifth; you want to know how many dollars or pounds that means you save. If your investment grew by “15%,” you want to know the tangible increase in your portfolio’s value. This translation is where the rubber meets the road, turning abstract proportions into concrete figures that directly impact your bank balance.
Why the Conversion Matters for Your Wallet
Mastering this simple conversion empowers you in countless financial scenarios:
-
Accurate Budgeting: You can precisely allocate a percentage of your income to various categories (e.g., “30% for housing” becomes “$1,500/month” if your income is $5,000).
-
Smart Shopping: You can instantly calculate the actual discount amount and final price, ensuring you truly understand the savings.
-
Informed Investing: You can quantify gains and losses, translating abstract percentage returns into real growth or depletion of your capital.
-
Debt Management: You can calculate the exact interest paid on loans and credit cards, highlighting the true cost of borrowing.
-
Tax Planning: You can estimate tax liabilities based on percentage rates applied to your income or purchases.
In essence, converting percentages to whole numbers is the bridge between understanding financial concepts and actively managing your money. It shifts you from a passive observer to an engaged participant in your own financial journey.
The Step-by-Step Guide to Percentage-to-Whole Number Conversion
The process of converting a percentage to a whole number is straightforward and relies on a few fundamental mathematical principles. While there are a couple of approaches, they both yield the same accurate results. The key is to remember that a percentage is always a part of a base whole number.
Method 1: The Decimal Bridge – The Most Common Approach
This method is the most widely used and generally the most intuitive for financial calculations, especially when using calculators or spreadsheets. It involves two simple steps:
Step 1: Convert the Percent to a Decimal
To convert any percentage to a decimal, you simply divide the percentage by 100. This is equivalent to moving the decimal point two places to the left.
-
Example:
-
25% becomes 25 ÷ 100 = 0.25
-
7.5% becomes 7.5 ÷ 100 = 0.075
-
120% becomes 120 ÷ 100 = 1.20
-
Step 2: Multiply the Decimal by the Base Whole Number
Once you have the decimal equivalent of the percentage, multiply it by the original whole number amount (the base amount) to find the specific whole number value that the percentage represents.
-
Formula: Whole Number Value = Decimal Equivalent × Base Whole Number
-
Real-world Examples:
-
Calculating a Discount: You want to buy a jacket that costs $80, and it’s on sale for 30% off.
-
Step 1: Convert 30% to a decimal: 30 ÷ 100 = 0.30
-
Step 2: Multiply by the base whole number ($80): 0.30 × $80 = $24
-
The discount is $24. The final price would be $80 – $24 = $56.
-
-
Calculating Sales Tax: Your bill for dinner is $65, and the sales tax is 8%.
-
Step 1: Convert 8% to a decimal: 8 ÷ 100 = 0.08
-
Step 2: Multiply by the base whole number ($65): 0.08 × $65 = $5.20
-
The sales tax is $5.20. Your total bill would be $65 + $5.20 = $70.20.
-
-
Investment Gains: You invested $5,000, and it grew by 12% in a year.
-
Step 1: Convert 12% to a decimal: 12 ÷ 100 = 0.12
-
Step 2: Multiply by the base whole number ($5,000): 0.12 × $5,000 = $600
-
Your investment gained $600. Your new total is $5,000 + $600 = $5,600.
-
-
Method 2: The Fractional Approach – An Alternative for Simpler Percents
While less common for complex financial calculations, the fractional approach can be very useful for mental math or when dealing with common percentages that have simple fractional equivalents (e.g., 25%, 50%, 75%, 10%, 20%).
Step 1: Convert Percent to a Fraction
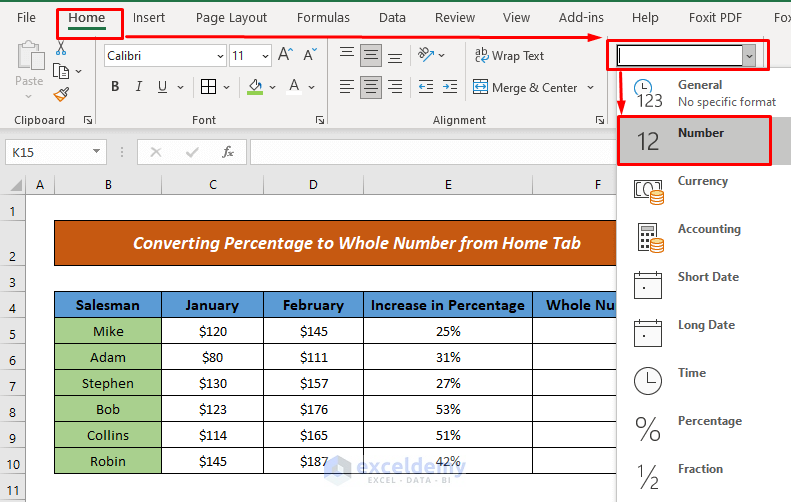
Express the percentage as a fraction with 100 as the denominator. Then, simplify the fraction if possible.
-
Example:
-
25% becomes 25/100, which simplifies to 1/4
-
50% becomes 50/100, which simplifies to 1/2
-
10% becomes 10/100, which simplifies to 1/10
-
Step 2: Multiply the Fraction by the Base Whole Number
Multiply the simplified fraction by the base whole number.
-
Formula: Whole Number Value = (Fractional Equivalent) × Base Whole Number
-
Real-world Examples:
-
Calculating a Tip: You want to leave a 20% tip on a $45 meal.
-
Step 1: Convert 20% to a fraction: 20/100 = 1/5
-
Step 2: Multiply by the base whole number ($45): (1/5) × $45 = $9
-
The tip is $9. Your total would be $45 + $9 = $54.
-
-
Simple Interest (Mental Math): You borrow $200 at 10% interest for one year.
-
Step 1: Convert 10% to a fraction: 10/100 = 1/10
-
Step 2: Multiply by the base whole number ($200): (1/10) × $200 = $20
-
The interest for the year is $20.
-
-
Both methods are mathematically sound. The decimal bridge is generally more versatile, especially when percentages aren’t easily reducible to simple fractions, or when precision is paramount (e.g., interest calculations involving many decimal places).
Practical Applications in Personal Finance and Investing
The ability to fluidly convert percentages to whole numbers is a cornerstone of financial literacy, impacting almost every aspect of your money management. Let’s explore some key areas where this skill becomes invaluable.
Budgeting and Expense Management
Effective budgeting involves allocating your income across various categories like housing, food, transportation, savings, and entertainment. Often, these allocations are expressed as percentages of your total income. Converting these percentages into precise dollar amounts allows you to create a tangible, actionable budget.
-
Example: If your monthly net income is $4,000 and you aim to save 15%, spend 30% on housing, and 20% on food:
-
Savings: 0.15 × $4,000 = $600
-
Housing: 0.30 × $4,000 = $1,200
-
Food: 0.20 × $4,000 = $800
-
This conversion moves you from aspirational percentages to concrete spending limits and savings goals, making it easier to track and adhere to your budget.
Decoding Investment Returns and Portfolio Growth
In the investment world, performance is almost always communicated in percentages. Whether it’s the annual return of a stock, the yield of a bond, or the growth of a mutual fund, understanding the actual dollar impact requires conversion.
-
Example: You have an investment portfolio worth $100,000, and it generated a 7% return last year.
-
Growth in dollars: 0.07 × $100,000 = $7,000
-
Your portfolio is now worth $100,000 + $7,000 = $107,000.
-
This helps you understand the true value increase, not just the relative performance. It’s also critical for calculating dividend yields (what percentage of the stock price you receive in dividends) and understanding the impact of fees, which are often percentage-based.
Understanding Loans, Interest Rates, and Payments
Loans and credit products are heavily percentage-driven. Interest rates (APR – Annual Percentage Rate) dictate the cost of borrowing, and understanding how these percentages translate into actual interest payments is vital for managing debt.
-
Example: You take out a $10,000 personal loan with a 6% annual interest rate.
-
Annual interest: 0.06 × $10,000 = $600
-
This tells you the base cost of borrowing for one year. For monthly payments, you’d then divide by 12 (assuming simple interest calculation for this example, though actual loan calculations are more complex with compounding).
-
Being able to calculate these figures helps you compare loan offers, understand repayment schedules, and assess the true cost of debt.
Calculating Sales Tax, Tips, and Discounts with Confidence
For everyday consumers, this conversion skill is most frequently applied in retail environments.
-
Sales Tax: Almost every purchase has a percentage-based sales tax. Knowing how to quickly calculate it helps you anticipate the final cost.
-
Tips: Tipping culture often involves percentages (15%, 20%, 25%). Rapid calculation ensures you tip appropriately without over or underpaying.
-
Discounts: “Up to 50% off!” promotions are common. Converting the percentage discount to a dollar amount helps you quickly determine your savings and the final price. This prevents impulse buys driven by large percentage figures that might not translate to significant dollar savings on inexpensive items.
Avoiding Common Mistakes and Enhancing Financial Literacy
While the conversion itself is simple, several common pitfalls can lead to financial miscalculations. Being aware of these and utilizing available tools can significantly enhance your financial accuracy and literacy.
The Importance of the “Base Number”
A percentage is always “of” something. The most frequent mistake is applying a percentage to the wrong base number.
-
Example: A store advertises “30% off original price!” If the item was originally $100 and is now $70 (already 30% off), a further 10% discount on the current price is 10% of $70, not 10% of $100.
-
Correct: 0.10 × $70 = $7 discount, new price = $63.
-
Incorrect: 0.10 × $100 = $10 discount.
-
Always identify what the percentage is referring to. Is it a percentage of your gross income or net income? Of the principal balance or the total amount due? Clarity on the base number is paramount.
Rounding Rules in Financial Contexts
When converting percentages that result in long decimals (e.g., 3.3333%), or when multiplying by a base number that leads to many decimal places, knowing when and how to round is crucial for monetary accuracy.
-
In finance, amounts are typically rounded to two decimal places (cents/pence).
-
General Rule: Round up if the third decimal place is 5 or greater; round down if it’s 4 or less.
-
Example: A calculation yields $15.7865. This would be rounded to $15.79. If it yielded $15.7832, it would be $15.78.
Consistent rounding prevents discrepancies and ensures that your financial records match actual transactions.
Leveraging Financial Tools: Calculators, Spreadsheets, and Apps
While understanding the manual conversion process is essential, modern financial management benefits immensely from digital tools.
-
Calculators: Basic calculators (physical or on your phone) are indispensable for quick conversions and multiplications.
-
Spreadsheets (Excel, Google Sheets): These are powerful tools for managing budgets, tracking investments, and performing complex financial modeling. They automatically handle percentage conversions and calculations with high precision. For instance, if you type
=25%*100into a cell, it will instantly give you25. -
Financial Apps: Many budgeting, banking, and investment apps include built-in calculators or display conversions directly, simplifying the user experience.
Don’t shy away from these tools; they enhance efficiency and reduce the chance of manual errors, allowing you to focus on the strategic aspects of your financial decisions.
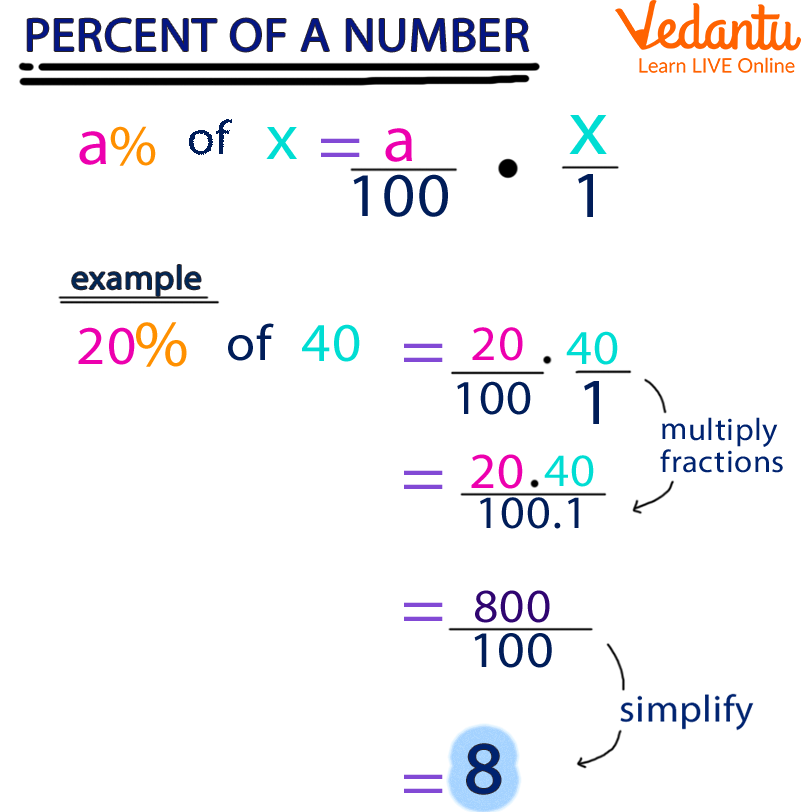
Conclusion
The ability to accurately convert a percentage to a whole number is more than just a mathematical trick; it is a foundational pillar of financial literacy. From dissecting a retail discount to forecasting investment returns, managing debt, or meticulously crafting a budget, this skill translates abstract proportions into tangible financial figures that directly impact your economic well-being.
By understanding the “decimal bridge” and the “fractional approach,” identifying the correct base number, and judiciously applying rounding rules, you gain a powerful lens through which to view your money. Furthermore, embracing readily available financial tools like calculators and spreadsheets empowers you to execute these conversions with efficiency and precision.
In a world increasingly driven by data and percentages, mastering this conversion transforms you from a passive consumer of financial information into an active, informed decision-maker. It allows you to confidently navigate prices, understand interest, evaluate investments, and ultimately, take greater control over your financial future. This seemingly simple mathematical operation is, in essence, a key to unlocking greater financial clarity and economic empowerment.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.