
Navy Federal Credit Union (NFCU) stands as a titan in the world of member-owned financial institutions. As the largest natural member credit union in the United States, it offers a level of service and a suite of products that often rival or exceed those of the largest commercial banks. However, because it is a credit union, membership is not open to the general public. It is a specialized ecosystem designed to serve those who have served the nation, along with their families. Opening an account is more than a simple transaction; it is an entry into a financial community known for competitive interest rates, lower fees, and a member-centric philosophy.
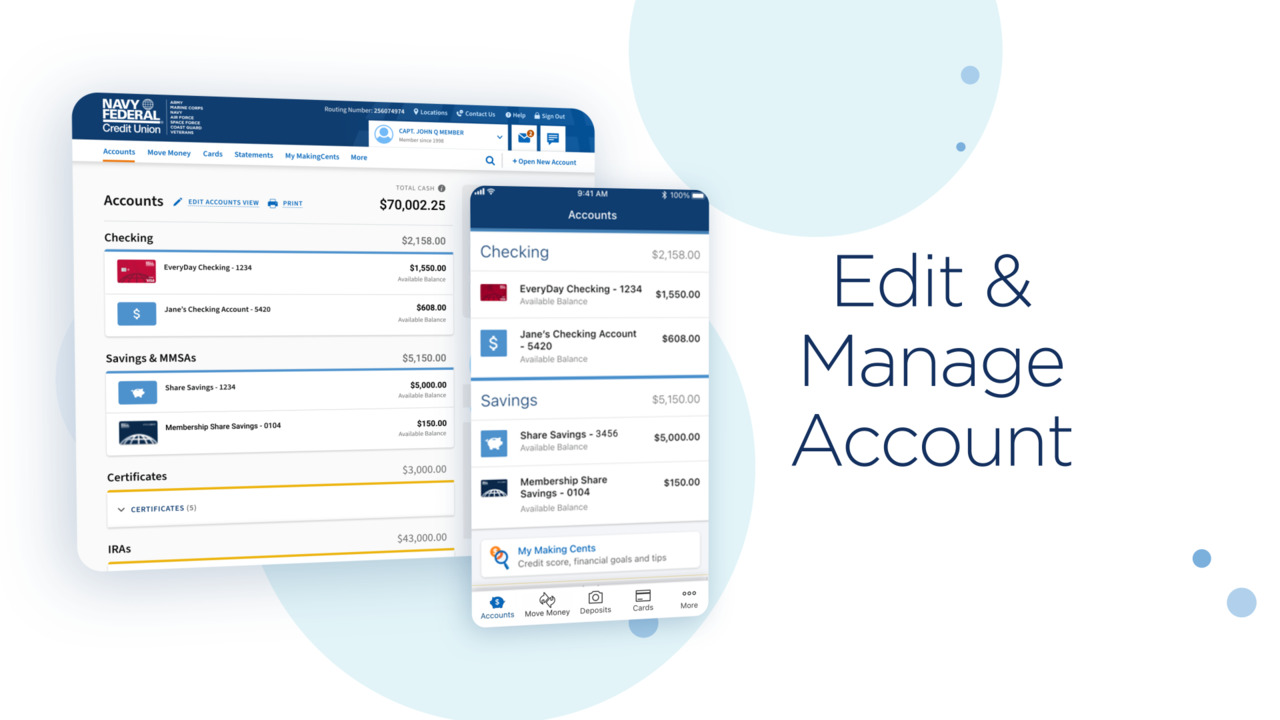
Navigating the process of joining Navy Federal requires an understanding of eligibility requirements, a gathering of specific documentation, and a strategic approach to selecting the right initial products. This guide provides a comprehensive roadmap for securing membership and leveraging the full weight of the institution’s financial tools to better your personal balance sheet.
Understanding Eligibility: Who Can Join Navy Federal?
The most significant hurdle to opening a Navy Federal account is the field of membership. Unlike a traditional bank that accepts any applicant with a valid ID and a deposit, Navy Federal is restricted by its charter to individuals with ties to the armed forces or the Department of Defense.
Active Duty, Veterans, and Retirees
The core of Navy Federal’s membership consists of those who are currently serving or have served in any branch of the U.S. military. This includes the Navy, Marine Corps, Army, Air Force, Coast Guard, Space Force, and the National Guard. Whether you are an active-duty service member, a reservist on drill status, or a retired veteran with an honorable discharge, you are eligible for membership. Navy Federal is particularly noted for its “Active Duty Checking” accounts, which offer early direct deposit and fee rebates, making it a primary choice for those currently in uniform.
Family Members and Household Ties
One of the most generous aspects of Navy Federal’s eligibility rules is the extension of membership to family members. Once a service member joins, or even if they are eligible but have not yet joined, their immediate family can apply. Immediate family is defined broadly and includes parents, grandparents, spouses, siblings, children (including adopted and stepchildren), and grandchildren.
Furthermore, household members—individuals who live in the same residence as a Navy Federal member—are also eligible. This inclusive policy allows the benefits of credit union membership to flow through generations, ensuring that the financial stability afforded to a service member can be shared with their domestic partners or roommates.
Department of Defense (DoD) Personnel
Beyond the uniformed services, Navy Federal serves the civilian backbone of the military. This includes Department of Defense civilian employees, U.S. Government employees assigned to DoD installations, and civilian contractors who work permanently on DoD installations. If you are a civilian working in a capacity that supports the military infrastructure, there is a high probability that you qualify for membership, granting you access to the same high-yield savings and low-interest loan products as active-duty personnel.
Preparing Your Documentation: What You Need Before You Apply
The application process is streamlined, but it can be delayed if you do not have the necessary verification documents ready. Navy Federal’s security protocols are stringent to protect the integrity of the institution and the identity of its members.
Personal Identification Requirements
To comply with federal regulations, specifically the USA PATRIOT Act, Navy Federal must verify your identity. You will need a government-issued photo ID, such as a driver’s license, passport, or state ID. If you are applying based on your own military service, having your Common Access Card (CAC) or your DD-214 (Certificate of Release or Discharge from Active Duty) is essential for verifying your status. For civilian employees, a work badge or a recent pay stub from a DoD agency may be required.
Financial and Contact Information
During the application, you will need to provide your Social Security number and a valid physical address. If you are currently stationed overseas, Navy Federal is well-equipped to handle APO/FPO/DPO addresses, which is one of the reasons it is a favorite for those deployed or stationed in foreign OCONUS locations. You will also need to provide an email address and phone number to set up multi-factor authentication, a critical component of their digital security suite.
Initial Deposit and Funding Sources
Opening a membership requires opening a Share Savings account, which represents your “share” of ownership in the credit union. The minimum deposit to open this account and establish membership is typically $5. You can fund this initial deposit via an electronic transfer from another bank, a debit or credit card, or by mailing a check. Having your external bank’s routing and account numbers ready will make the online application process much faster.
Step-by-Step: The Application Process
Once you have confirmed your eligibility and gathered your documents, the actual process of opening the account can be completed in minutes. Navy Federal offers three primary channels for application: online, mobile, and in-person.
Online Application: The Fastest Route
The most common way to join is through the Navy Federal website. The digital portal is designed to guide you through a series of prompts. You will first select your eligibility category (e.g., Active Duty, Veteran, or Family Member). If you are joining through a family member, you will ideally need their name and Navy Federal access number, though the system can often look them up with their permission. After entering your personal details and verifying your identity, you will select your account types—typically starting with a basic savings and a checking account.
Applying via Mobile App
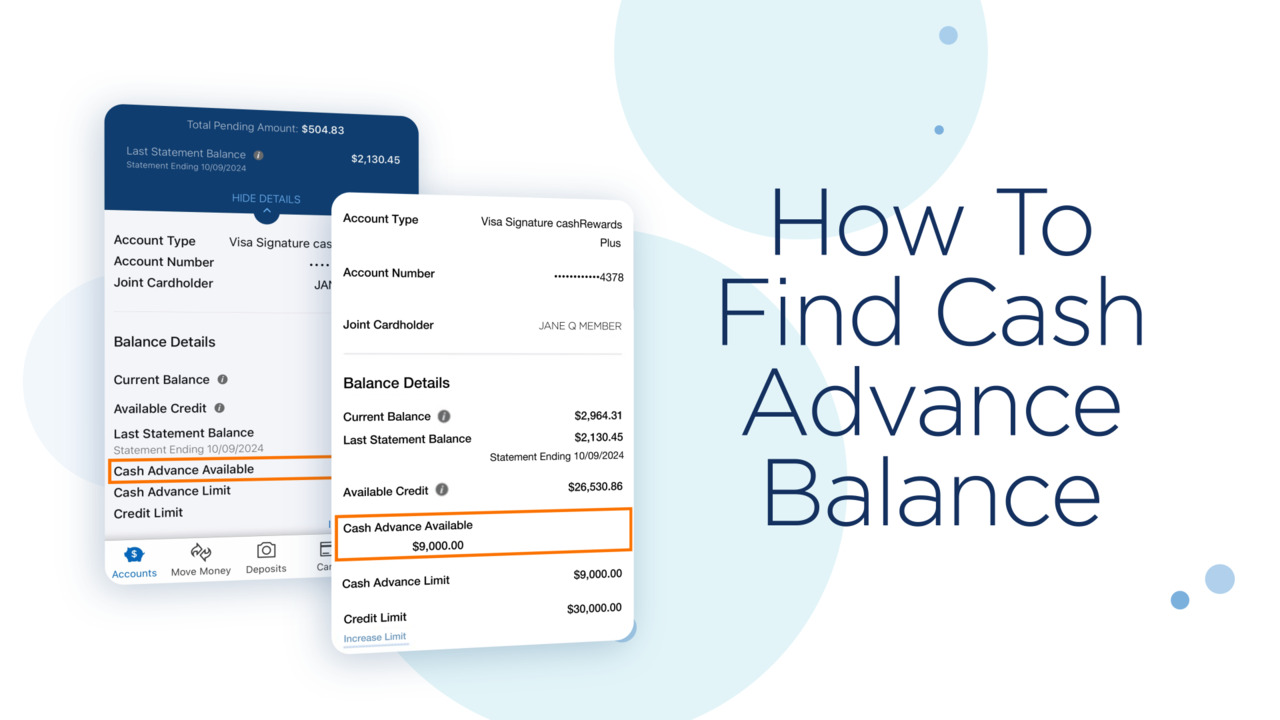
For those who prefer a mobile-first experience, the Navy Federal app allows you to complete the entire membership application. This method is particularly useful because it allows you to use your smartphone camera to scan your ID and documents, reducing the amount of manual data entry required. The app’s interface is intuitive and provides real-time status updates on your application.
In-Person and Over-the-Phone Options
If you live near a Navy Federal branch—often located on or near military installations—you can walk in and speak with a Member Service Representative. This is often the best route for those with complex eligibility questions or those who want to receive their debit card immediately, as many branches offer instant-issue cards. Additionally, Navy Federal operates a 24/7 contact center. Their representatives are famous for their high level of training and can walk you through the application over the phone at any hour of the day or night.
Maximizing Your Membership: Next Steps After Account Approval
Simply opening an account is only the first step. To truly benefit from Navy Federal, you must integrate their tools into your daily financial management and long-term planning.
Navigating the Digital Banking Suite
Once your account is open, setting up your online banking profile is a priority. Navy Federal’s digital platform is highly rated for its security and functionality. You should immediately enable features such as “Free Active Monitoring,” which alerts you to changes in your credit report, and “Digital Wallet” integration for Apple Pay or Google Pay. The platform also offers “Bill Pay” services that allow you to automate your monthly obligations, ensuring you never miss a payment.
Setting Up Direct Deposit and Automatic Transfers
To unlock the best features of certain checking accounts, such as the “Free Active Duty Checking” or the “Flagship Checking,” you should set up a direct deposit. For military members, this is handled through the MyPay system. For civilians, providing your Navy Federal routing and account numbers to your employer’s HR department is the standard procedure. Setting up a recurring “automatic transfer” from your checking to your savings account on payday is a fundamental personal finance strategy that Navy Federal makes exceptionally easy to execute.
Exploring Specialized Loan Products and Credit Cards
Navy Federal is perhaps best known for its lending products. Once you are a member, you gain access to credit cards that often have lower interest rates and higher credit limits than those offered by “Big Box” banks. For example, the “More Rewards” card or the “Flagship Rewards” card offer competitive points systems for travel and daily spending. Furthermore, their auto loans and mortgage products (including VA loans) are frequently cited as some of the most competitive in the industry, often featuring 100% financing options and no hidden fees.
Long-Term Financial Planning with Navy Federal
Membership in Navy Federal is for life. Even if you leave the military or move away from a branch, you retain your membership. This longevity allows the credit union to serve as a cornerstone of your long-term wealth-building strategy.
Building Credit through Member-Focused Products
For younger members or those looking to rebuild their financial standing, Navy Federal offers “nREWARDS” Secured Credit Cards and personal “pledge loans.” These products allow you to use your own savings as collateral to build a positive payment history. Because Navy Federal reports to all three major credit bureaus, consistent use of these tools can significantly raise your credit score over time, qualifying you for better rates on future mortgages or business loans.
Competitive Savings and Retirement Accounts
Beyond daily banking, Navy Federal provides robust options for long-term savings. Their Certificates of Deposit (CDs), often referred to as “EasyStart Certificates,” frequently offer promotional rates that outpace the national average. Additionally, they provide Individual Retirement Accounts (IRAs) and access to Navy Federal Financial Group (NFFG) advisors. These advisors can help you navigate the complexities of retirement planning, life insurance, and investment portfolios, ensuring that your military or civilian benefits are maximized for your future security.
By following this guide to opening an account, you aren’t just choosing a place to store your money; you are joining a financial cooperative dedicated to the unique needs of the defense community. The combination of personalized service, technological innovation, and aggressive financial rates makes Navy Federal Credit Union an essential tool for any eligible individual looking to master their personal finances.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.