
American Express (Amex) occupies a unique position in the global financial landscape. Unlike many other card issuers that act strictly as lenders, American Express functions as both a card issuer and a payment network. This vertical integration allows them to offer bespoke benefits, high-tier customer service, and a rewards ecosystem that is often cited as the gold standard for travelers and high-spenders. However, obtaining an American Express card is often perceived as a more rigorous process than securing a standard bank-issued credit card. To successfully navigate the application process and secure a place within this financial ecosystem, one must understand the specific requirements, the variety of products available, and the strategic maneuvers that increase the likelihood of approval.
Understanding the American Express Ecosystem
Before clicking the “Apply” button, it is essential to understand that American Express offers two distinct types of cards: Credit Cards and cards with “Pay Over Time” features (formerly known as Charge Cards).
Credit Cards vs. Pay Over Time Cards
Standard American Express credit cards, such as the Blue Cash Everyday® or the Hilton Honors cards, operate like traditional credit cards. They have a fixed credit limit and allow you to carry a balance from month to month while paying interest. In contrast, premium cards like The Platinum Card® or the American Express® Gold Card were historically charge cards, meaning the balance was due in full every month. Today, these premium cards feature a “Pay Over Time” limit, which provides a hybrid experience. However, they still lack a traditional “preset spending limit,” meaning your purchasing power adjusts based on your use of the card, your payment history, and your financial resources.
The Power of Membership Rewards
A primary motivation for seeking an American Express card is access to the Membership Rewards (MR) program. These points are highly valued by financial enthusiasts because of their flexibility. Rather than being tied to a single airline or hotel chain, MR points can be transferred to dozens of partner programs, including Delta SkyMiles, British Airways Executive Club, and Hilton Honors. Understanding the value of these points is critical because it justifies the higher annual fees associated with many Amex products.
The Prerequisites for a Successful Application
American Express is known for its “Apply with Confidence” feature, which allows applicants to see if they are approved for a card with a soft credit pull before committing to a hard inquiry that affects their credit score. Despite this transparency, certain financial benchmarks remain crucial for approval.
Credit Score Requirements
While American Express does not publicly disclose a minimum credit score, historical data suggests that a “Good” to “Excellent” FICO score is typically required. For entry-level cards like the Cash Magnet® or the Blue Cash Everyday®, a score in the 670 to 700 range is usually sufficient. For premium tier cards, such as the Platinum or Gold cards, applicants generally find more success with scores above 720. It is important to note that Amex looks at your entire credit profile, not just the three-digit number. They value a clean payment history and a low debt-to-income (DTI) ratio.
Income and Employment Status
To comply with federal regulations, American Express must ensure that an applicant has the “ability to pay.” When filling out the application, you are required to report your total annual income. This includes not just your salary, but also bonuses, interest, dividends, and, if you are over the age of 21, any income from a spouse or partner that you have a reasonable expectation of access to. Being accurate and honest here is vital; while Amex rarely requests a 4506-C form (tax transcript), they reserve the right to perform a financial review if they suspect inconsistencies.
Strategic Steps to Secure Your First Amex Card
If you are new to the American Express ecosystem, your strategy should focus on building a relationship with the institution. Amex is famously loyal to its existing customers, often offering subsequent cards with no additional hard credit pull once the first account is established.
Utilizing the Pre-Qualification Tool
The most effective way to start is by using the official American Express pre-qualification tool. By entering basic information, the system will show you which cards you are likely to be approved for. This step is a “soft pull,” meaning it does not impact your credit score. If you see a specific offer with a “fixed” APR or a “pre-approved” label, your odds of final approval are significantly higher.
Managing the “Once Per Lifetime” Rule
One of the most important strategies to consider before applying is American Express’s “Once Per Lifetime” rule for welcome bonuses. Generally, you can only earn a sign-up bonus for a specific card once in your life. Therefore, it is wise to wait for an elevated offer. For example, if the standard bonus for the Gold Card is 60,000 points, but you find a referral link or a “targeted” offer for 90,000 points, it is worth the effort to secure the higher amount, as you will likely never have the opportunity to earn that bonus again.
The 5-Card and 2/90 Rules
Amex has internal limits on the number of cards a single individual can hold. Generally, you are limited to five personal or business credit cards at one time (this limit does not usually count the “Pay Over Time” cards like the Gold or Platinum). Additionally, the “2/90” rule suggests that American Express will generally not approve more than two credit cards in a 90-day period. Keeping these constraints in mind helps in timing your applications for maximum success.
Choosing the Right Card for Your Financial Profile
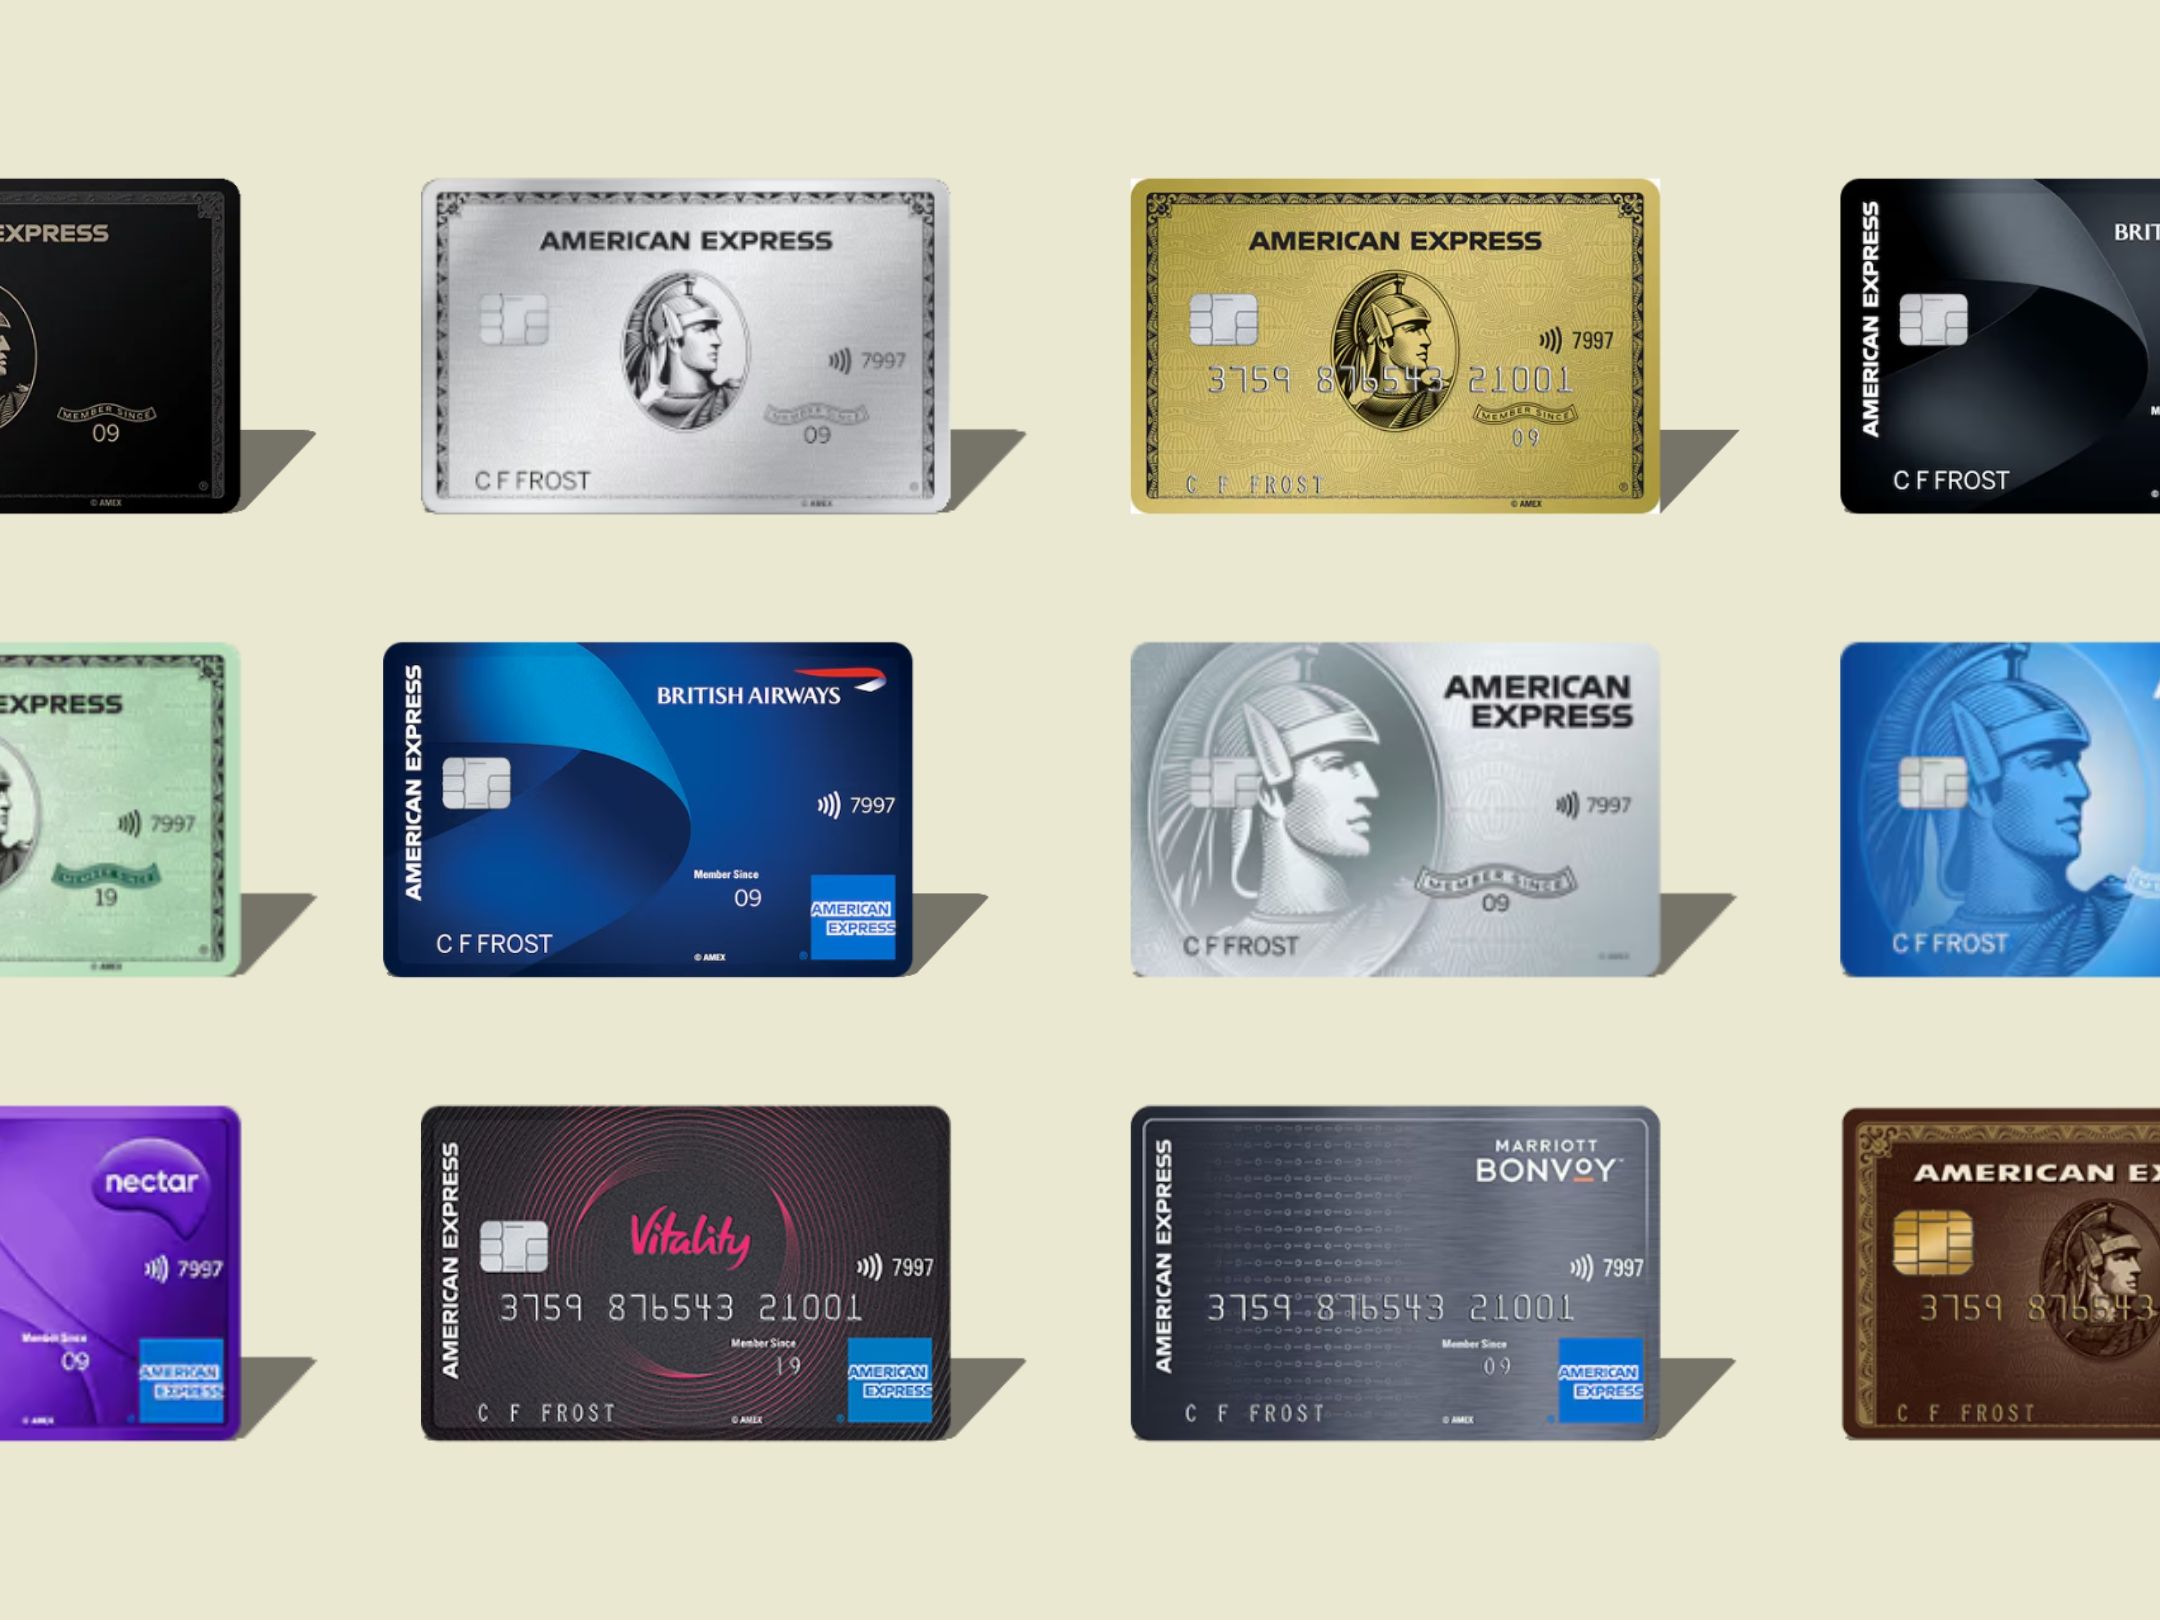
Not all American Express cards are created equal. Choosing the right one depends on your spending habits and whether you prefer cash back or travel rewards.
The Travel Enthusiast: The Platinum Card®
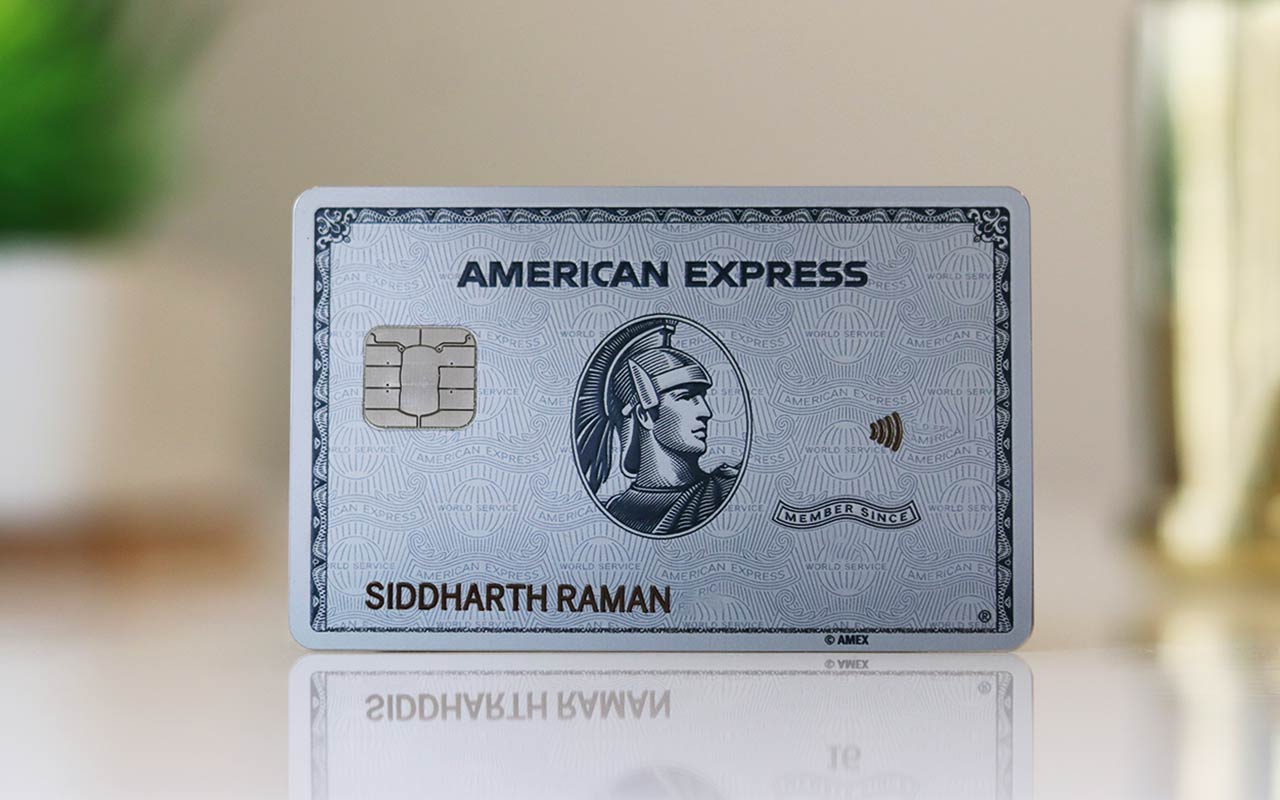
For those who travel frequently, the Platinum Card is the flagship product. While it carries a high annual fee, it offers unparalleled lounge access (including the Centurion Lounge network), significant airline and hotel credits, and elite status with Hilton and Marriott. This card is best suited for individuals who can naturally utilize the various digital entertainment, Uber, and Saks Fifth Avenue credits to offset the annual cost.
The Everyday Spender: The Gold Card
The American Express® Gold Card is often considered the “workhorse” of the rewards world. It earns high multipliers (4x points) on dining at restaurants and at U.S. supermarkets. For the average household that spends significantly on groceries and eating out, the points accumulated on this card can quickly outweigh the annual fee.
The Cash Back Advocate: Blue Cash Preferred®
If you prefer the simplicity of cash back over the complexity of travel points, the Blue Cash Preferred® is a top-tier choice. It offers a massive 6% cash back at U.S. supermarkets (on up to $6,000 per year) and on select U.S. streaming subscriptions, along with 3% on transit and gas. This card is ideal for those who want a straightforward return on their everyday domestic spending.
Maximizing Value After Approval
Getting the card is only the first step. To truly benefit from the American Express experience, you must manage the account strategically.
Meeting the Minimum Spend Requirement
Most American Express cards come with a “Welcome Offer.” This requires you to spend a specific amount of money within the first three to six months. It is imperative to track this spending carefully. Missing the requirement by even a few dollars will result in a total loss of the bonus, which is often the most valuable part of the card’s first-year ownership. Using the card for all regular expenses—rent (where feasible), utilities, groceries, and insurance—is a common way to hit these targets without overspending.
Monitoring “Amex Offers”
Once you are a cardholder, the American Express mobile app becomes a powerful tool. The “Amex Offers” section provides targeted discounts and bonus point opportunities at various retailers, from technology brands to clothing stores. By “adding” these offers to your card before shopping, you can save hundreds of dollars annually, effectively negating the cost of the annual fee.
Building a Long-Term Relationship
American Express values longevity. By maintaining a perfect payment record and keeping your accounts in good standing, you gain access to higher credit limits and “soft pull” approvals for future cards. Furthermore, if you ever decide the annual fee on a premium card is no longer worth it, Amex is known for offering “retention bonuses”—extra points or statement credits—to encourage loyal customers to keep their accounts open.
In conclusion, obtaining an American Express card requires a blend of solid credit health, an understanding of their specific product tiers, and a strategic approach to applications. By leveraging pre-qualification tools, choosing a card that aligns with your spending habits, and adhering to the institution’s internal rules, you can unlock a suite of financial tools and rewards that are among the most competitive in the industry. Whether you are looking for luxury travel perks or high-yield cash back, there is likely an American Express product that fits your financial trajectory.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.