
Choosing where to open an Individual Retirement Account (IRA) is one of the most consequential financial decisions an investor will make. While the Internal Revenue Service (IRS) sets the rules for how much you can contribute and the tax advantages you receive, the financial institution you choose—the “custodian”—determines your investment options, the fees you pay, and the quality of the tools at your disposal.
The landscape of retirement planning has shifted significantly over the last decade. Investors are no longer tethered to high-fee local banks or traditional brokerage houses that charge a premium for every trade. Today, the market is divided among legacy powerhouses, low-cost index fund pioneers, and tech-driven robo-advisors. Deciding which path to take requires an honest assessment of your financial goals, your level of expertise, and how much time you are willing to dedicate to managing your portfolio.

Top-Tier Brokerages for the Self-Directed Investor
For many, the ideal IRA provider is one that offers a “supermarket” of investment choices with little to no overhead cost. Self-directed investors typically look for platforms that provide deep research, a wide array of commission-free trades, and robust customer support.
Fidelity Investments: The All-Rounder
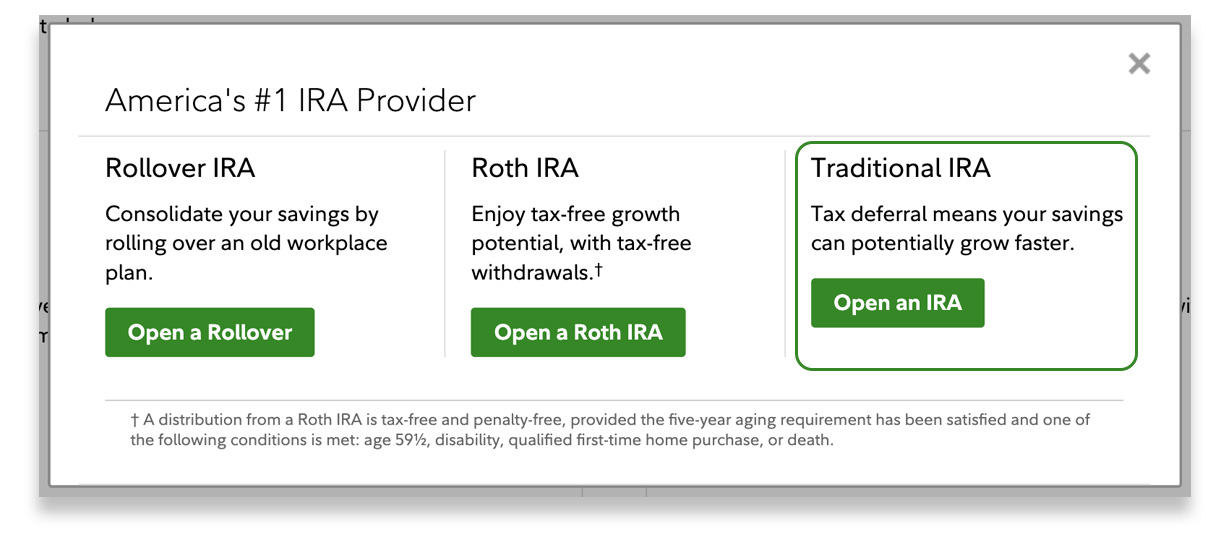
Fidelity has consistently positioned itself as a leader for both novice and experienced investors. One of its standout features is the “Fidelity Zero” family of funds—index funds that carry a 0% expense ratio. In an industry where even “low-cost” funds charge a few basis points, Fidelity’s commitment to zero-cost investing is a significant draw for those looking to maximize every penny of their retirement savings.
Beyond low costs, Fidelity offers a sophisticated web platform and mobile app that provide institutional-grade research. Their customer service is frequently cited as top-tier, offering 24/7 support and access to physical branches for those who prefer face-to-face interaction. For a Traditional or Roth IRA, Fidelity provides a frictionless experience that scales as your portfolio grows.
Charles Schwab: Innovation and Research
Charles Schwab is often the go-to choice for investors who value research and a high-quality user interface. Schwab was a pioneer in the discount brokerage space and continues to lead with its “Schwab Personalized Indexing” and extensive library of educational content.
Schwab’s IRA accounts benefit from $0 commissions on stocks and ETFs, and they offer a “Satisfaction Guarantee” that allows clients to request a refund of certain fees if they are unhappy for any reason. Their “Intelligent Portfolios” also provide a hybrid approach for those who want a managed account experience within a traditional brokerage framework.
Vanguard: The Vanguard of Indexing
If your investment philosophy is rooted in the “buy and hold” strategy popularized by Jack Bogle, Vanguard is the natural home for your IRA. Vanguard is unique because it is owned by its funds, which are in turn owned by the investors. This structure ensures that the company’s interests are perfectly aligned with its clients: lowering costs.
While Vanguard’s user interface has historically been more utilitarian than its competitors, the company has made significant strides in modernization. It remains the gold standard for low-cost mutual funds and ETFs. For investors who want to build a “Three-Fund Portfolio” and leave it alone for thirty years, Vanguard’s stability and culture make it an excellent choice.
The Rise of Robo-Advisors: Hands-Off Retirement Planning
Not everyone wants to spend their weekends researching price-to-earnings ratios or rebalancing their asset allocation. For the “set it and forget it” crowd, robo-advisors offer an automated solution that uses algorithms to manage your IRA.
Betterment: Goal-Oriented Investing
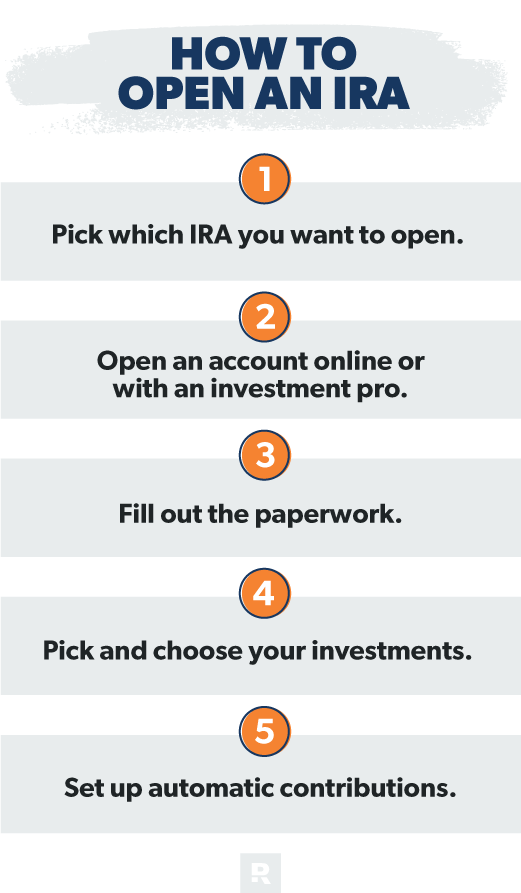
Betterment was one of the first robo-advisors to market and remains a top choice for IRA accounts. The platform excels at goal-based planning. When you open an IRA, Betterment asks about your age, income, and retirement goals, then constructs a diversified portfolio of low-cost ETFs tailored to your risk tolerance.
One of Betterment’s most valuable features for IRA holders is its automated rebalancing. If one asset class performs exceptionally well and begins to over-occupy your portfolio, the algorithm automatically sells high and buys low to return you to your target allocation. They also offer “Tax-Coordinated Portfolios,” which strategically place assets in different account types (like IRAs vs. taxable accounts) to minimize your overall tax burden.
Wealthfront: Advanced Features for Tech-Savvy Savers
Wealthfront competes directly with Betterment but tends to appeal more to the tech-savvy or those with higher balances. Their “Path” tool is perhaps the most sophisticated retirement planning software available to retail investors, pulling in data from all your financial accounts to provide a real-time picture of your retirement readiness.
Wealthfront also offers “Tax-Loss Harvesting” even in their automated accounts, though this is primarily a benefit for taxable accounts. For IRAs, their value lies in their highly efficient portfolio construction and their “Self-Driving Money” feature, which can automatically route excess cash into your IRA to ensure you hit your annual contribution limits without thinking about it.
Specialized Platforms and Niche Choices
In recent years, a third category of IRA providers has emerged: those catering to mobile-first users or those who want highly customized, non-traditional portfolios.
M1 Finance: The Customizer’s Dream
M1 Finance offers a unique middle ground between a traditional brokerage and a robo-advisor. They use a “pie” metaphor for investing. You choose the “slices” of your pie—which could be individual stocks, ETFs, or pre-built expert portfolios—and M1 handles the execution.
When you contribute money to your M1 IRA, the platform automatically buys shares in the proportions you’ve set. This allows for “dynamic rebalancing,” where new contributions are steered toward the underperforming parts of your portfolio to keep your allocation on track. It is an excellent choice for the investor who wants control over what they own but wants the mechanical process of buying and rebalancing to be automated.
Robinhood: The IRA Match
Robinhood disrupted the industry with $0 commissions, and they are attempting to do the same for retirement with their IRA “Match” program. For eligible users, Robinhood offers a percentage-based match on IRA contributions (subject to certain holding period requirements). This is a rarity in the IRA world, where matches are usually reserved for employer-sponsored 401(k) plans.
While Robinhood lacks the deep research tools of a Fidelity or Schwab, its simplified interface is attractive to younger investors who are just starting their retirement journey. However, investors should be aware of the long-term trade-offs, such as a more limited selection of mutual funds compared to traditional houses.
Critical Factors in Selecting Your IRA Provider
Once you have narrowed down the list of potential providers, it is essential to evaluate them against specific criteria that will impact your long-term wealth accumulation.
Fee Structures and Hidden Costs
While most major brokerages have moved to $0 commissions for stocks and ETFs, fees can still hide in the margins. You should investigate:
-
Expense Ratios: Does the provider steer you toward their own high-cost funds?
-
Advisory Fees: Robo-advisors typically charge between 0.25% and 0.50% of your assets annually. Over 30 years, a 0.25% fee can eat tens of thousands of dollars of your potential growth.
-
Transfer Fees: Some custodians charge an “ACAT” fee (usually $50 to $100) if you ever decide to move your IRA to a different provider.
Investment Breadth and Asset Classes
Your IRA is a long-term vehicle, and your needs might change. Today you might only want a total stock market index fund, but in ten years, you might want exposure to international emerging markets, real estate investment trusts (REITs), or even alternative assets like gold or crypto-linked ETFs. Ensure your chosen platform offers a wide enough range of assets so you won’t feel the need to move your account later.
Technological Tools and Educational Resources
The “best” platform is often the one that encourages you to stay consistent. If a platform’s mobile app is glitchy or confusing, you may be less likely to check your progress or increase your contributions. Conversely, if a platform provides excellent retirement calculators and “what-if” scenario builders, you may feel more empowered and engaged with your financial future.
Finalizing the Decision
There is no single “perfect” place to open an IRA, but there is a perfect place for your specific needs.
If you are a beginner who wants to be guided through every step, a robo-advisor like Betterment or Wealthfront provides the necessary guardrails. If you are a cost-conscious investor who wants the best possible funds for the lowest possible price, Vanguard or Fidelity is likely your best bet. If you are a sophisticated trader who wants a combination of banking and investing in one place, Charles Schwab or Fidelity offers a seamless experience.
The most important step is not finding the absolute best provider on day one, but rather opening the account and starting the contribution cycle. Due to the power of compound interest, the time your money spends in the market is often more important than the specific platform it sits on. Choose a reputable custodian that aligns with your current philosophy, and begin the journey toward a secure financial future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.