
For most individuals, a vehicle represents the second-largest financial investment they will make, trailing only the purchase of a home. Yet, unlike a home, which typically appreciates over time, a car is a depreciating asset. From a personal finance perspective, understanding the precise value of your vehicle is not just a matter of curiosity; it is a fundamental requirement for effective wealth management, insurance optimization, and strategic tax planning.
Whether you are looking to sell, trade in for a newer model, or simply calculate your current net worth, determining a car’s value requires a blend of data-driven analysis and market awareness. The “worth” of a car is not a static number but a fluid figure influenced by economic shifts, technological advancements, and consumer behavior.

Understanding Car Valuation as a Financial Asset
To accurately assess what your car is worth, you must first view it through the lens of a financial auditor. In the world of personal finance, a car is often categorized as a “use asset.” While it provides utility, its monetary value begins to erode the moment it leaves the dealership lot.
The Impact of Depreciation Curves
Depreciation is the most significant “hidden cost” of vehicle ownership. On average, a new car loses about 20% of its value within the first year and approximately 15% each year thereafter for the first five years. By understanding where your vehicle sits on this depreciation curve, you can make informed decisions about when to exit the investment. For instance, selling a car at the four-year mark—just before major out-of-warranty repairs typically begin—often yields the best balance between utility gained and capital recovered.
Car Value and Your Net Worth
When calculating your net worth, many people make the mistake of using the original purchase price or an optimistic “gut feeling.” To maintain an accurate balance sheet, you should update your vehicle’s valuation at least annually. This ensures that your insurance coverage is appropriate and that you aren’t overpaying for premiums on a vehicle whose replacement cost has dropped significantly. Furthermore, if you carry a car loan, knowing the current market value is essential to avoid falling into an “underwater” or “upside-down” loan situation, where you owe more than the asset is worth.
Key Factors That Influence Your Car’s Market Value
Determining value goes beyond simply looking up a make and model. Several micro and macro factors play a role in the final number a buyer or dealer is willing to pay.
Mileage and Mechanical Condition
Mileage is perhaps the most objective metric used in valuation. High-mileage vehicles are statistically closer to major mechanical failures, which is reflected in a lower price. However, the type of miles often matters as much as the number. A car with 50,000 highway miles is often in better mechanical health than one with 30,000 miles driven in stop-and-go city traffic.
Beyond the odometer, the mechanical integrity—specifically the engine, transmission, and cooling systems—serves as the backbone of the car’s value. A vehicle with a documented history of preventative maintenance (oil changes, belt replacements, brake services) will consistently command a premium of 10% to 15% over a similar vehicle with no service records.
The Role of Scarcity and Market Demand
The principles of supply and demand are vividly apparent in the used car market. Certain brands and models hold their value better due to perceived reliability or “cult” status. For example, mid-sized trucks and fuel-efficient hybrids often retain a higher percentage of their value during periods of high gas prices. Conversely, luxury sedans with high maintenance costs tend to depreciate rapidly once their factory warranties expire.
Geography and Seasonality
Where you live and when you sell significantly impact your car’s worth. A convertible will fetch a higher price in Florida than in Maine, and a four-wheel-drive SUV is worth more in the autumn months as buyers prepare for winter. When assessing your car’s value, always look at “comps” (comparable sales) within a 50-to-100-mile radius to get a realistic picture of your local market.
Top Financial Tools and Resources for Precise Estimates
In the digital age, we have moved past the “Blue Book” being a physical pamphlet at a dealership. There are now several sophisticated tools that aggregate millions of data points to provide a valuation.
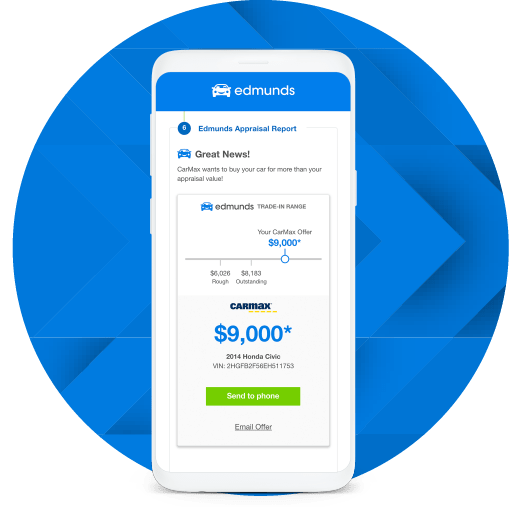
Kelley Blue Book (KBB) and Edmunds
KBB and Edmunds are the industry standards for consumer-facing valuations. They provide three distinct figures:
-
Trade-In Value: What a dealer will give you toward the purchase of another car. This is usually the lowest figure because the dealer must account for reconditioning and profit margin.
-
Private Party Value: What you can expect to receive if you sell the car yourself to another individual. This is generally higher than trade-in value but requires more effort.
-
Retail Value: What a dealer would list the car for on their lot. This is the highest number and includes the dealer’s overhead and warranty costs.
NADA Guides and Black Book
While KBB is popular with consumers, banks and insurance companies often rely on NADA (National Automobile Dealers Association) guides. NADA values tend to stay closer to what lenders are willing to finance. Black Book is another professional-grade tool used primarily by dealers to track weekly auction results. If you are negotiating a high-value trade-in, referencing NADA or Black Book data can provide more leverage than KBB alone.
Real-Time Market Platforms
For the most accurate “real-world” value, look at platforms like Bring a Trailer, Cars & Bids, or even Facebook Marketplace and Autotrader. These platforms show what people are actually paying, rather than a theoretical estimate. By filtering for “sold” listings, you can see the gap between the asking price and the final transaction price, which is a crucial distinction in a fluctuating economy.
Strategic Timing: When to Sell for Maximum Return
In personal finance, timing is everything. Holding onto a car for too long can lead to “maintenance creep,” where the cost of repairs exceeds the annual depreciation. Selling too early can lead to significant losses on the initial sales tax and “drive-off” depreciation.
The “Sweet Spot” of Vehicle Ownership
The most financially sound period to own a car is typically between years three and seven. During this window, the steepest part of the depreciation curve has passed, but the vehicle is still modern enough to be reliable and desirable to the secondary market. If your goal is to maximize the return on your investment, aim to sell before the car hits the 100,000-mile mark, as many buyers and lenders see this as a psychological and financial threshold that triggers a sharp drop in value.
Tax Implications and Trade-In Advantages
When determining what your car is worth, don’t forget to factor in the tax benefits of a trade-in. In many jurisdictions, you only pay sales tax on the difference between your new car’s price and your trade-in’s value. For example, if you buy a $30,000 car and trade in your old car for $10,000, you only pay sales tax on $20,000. In a state with 8% sales tax, that is an $800 savings. This “tax shield” often makes a lower trade-in offer from a dealer more financially attractive than a slightly higher private-party offer.
How to Boost Your Car’s Resale Value Before Appraisal
Once you have a baseline for what your car is worth, you can take active steps to push that value toward the “excellent” or “private party” end of the spectrum. This is where small investments of time and money can lead to significant financial gains.
The ROI of Professional Detailing
First impressions are quantifiable. A car that looks and smells new signals to a buyer that the mechanical components were likely treated with the same care. A professional detail, costing between $200 and $400, can frequently add $1,000 or more to the perceived value of a vehicle. Focus on removing odors, restoring headlight clarity, and deep-cleaning the engine bay.
Organizing the “Paper Trail”
Documentation is an asset. A binder containing every oil change receipt, tire rotation record, and repair invoice serves as proof of the car’s history. For high-end or vintage vehicles, this documentation can be the difference between an average sale and a record-breaking one. In the eyes of a savvy financial buyer, a well-documented car represents a lower risk, and lower risk always commands a higher price.
Addressing Minor Cosmetic and Mechanical Issues
Before seeking an appraisal, address “low-hanging fruit” repairs. Replace burnt-out bulbs, fix small chips in the windshield, and ensure the tires are properly inflated and cleaned. If the car has minor dents, consider “Paintless Dent Repair” (PDR). These small fixes remove the “negotiation ammunition” a buyer might use to chip away at your asking price. By presenting a vehicle that requires zero immediate investment from the next owner, you position yourself to demand the top end of the market value.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.