
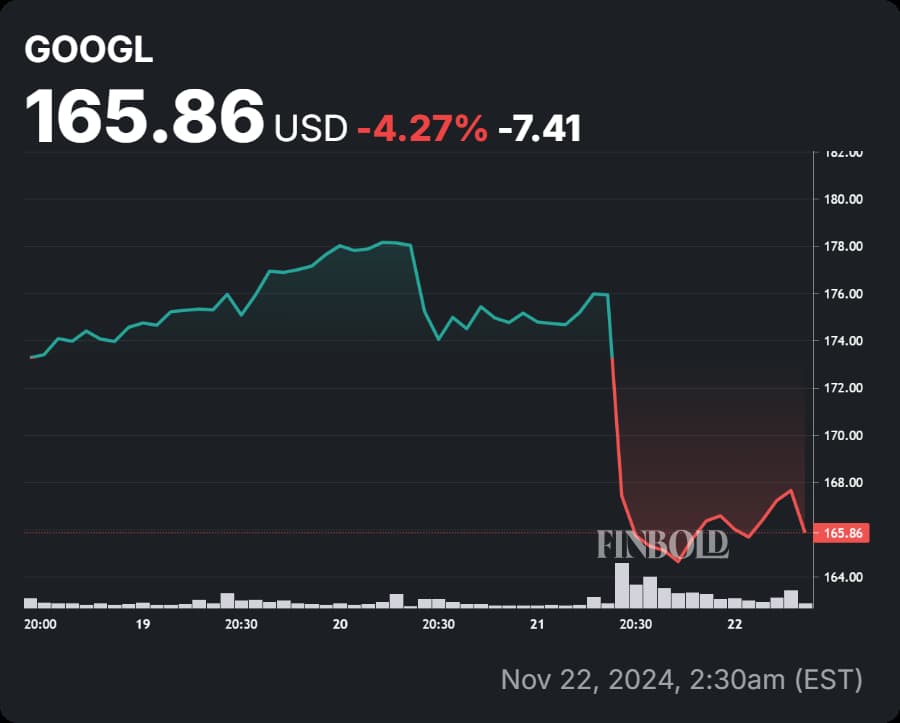
Google, or more accurately, its parent company Alphabet (GOOGL, GOOG), has long been a titan in the tech world, a seemingly impenetrable fortress of innovation and profitability. For years, its stock performance reflected this dominance, consistently delivering robust returns to investors. However, in various periods, even the mightiest companies experience downturns, and Alphabet is no exception. When Google’s stock experiences a significant drop, it triggers widespread concern and speculation among investors, analysts, and the general public. Understanding the multifaceted reasons behind such a decline requires a deep dive into macroeconomic trends, competitive pressures, regulatory landscapes, and company-specific performance metrics, all viewed through the lens of financial markets and investment strategies. This article aims to dissect the complex factors contributing to a hypothetical or real decline in Google’s stock price, providing a professional and insightful analysis exclusively within the “Money” niche.
Macroeconomic Headwinds and Investor Sentiment
The broader economic environment plays a crucial role in shaping the fortunes of individual stocks, especially those in the growth-oriented technology sector. When the economic tides turn, even the most robust companies can find themselves swimming against a strong current.
Inflationary Pressures and Interest Rate Hikes
One of the most significant macroeconomic forces impacting tech stocks, including Alphabet, is the persistent specter of inflation and the subsequent response from central banks. When inflation rises, central banks typically raise interest rates to cool down the economy. Higher interest rates have a twofold negative effect on growth stocks. Firstly, they increase the cost of borrowing for companies, making expansion and innovation more expensive. Tech companies, which often rely on debt financing for R&D and capital expenditures, feel this pinch acutely.
Secondly, and perhaps more critically for valuation, higher interest rates decrease the present value of future earnings. Growth stocks like Alphabet are often valued based on their anticipated future profits. When the discount rate used to calculate these future earnings increases, their present value, and thus the stock price, naturally falls. Investors become less willing to pay a premium for future growth when safer, lower-risk investments (like bonds) offer more attractive returns in the present. This re-rating of growth stocks often leads to significant price corrections, as the market recalibrates its expectations for future profitability in a higher interest rate environment.
Recession Fears and Advertising Spending Contraction
Another major macroeconomic headwind is the pervasive fear of a global or regional recession. Economic downturns are characterized by reduced consumer spending, business investment, and overall economic activity. For Alphabet, a significant portion of its revenue comes from advertising (Google Search, YouTube), which is highly cyclical and sensitive to economic fluctuations. During periods of economic uncertainty or recession, businesses tend to cut discretionary spending, and advertising budgets are often among the first to be reduced.
When advertisers pull back, Google’s core revenue streams shrink, directly impacting its top-line growth and profitability. Companies become more cautious about their marketing spend, focusing on high-ROI channels or pausing campaigns altogether. This contraction in advertising expenditure signals to investors that Google’s revenue growth might slow down or even decline, leading to a downward revision of earnings forecasts and, consequently, a drop in stock price. The sensitivity of Google’s business model to the health of the global economy makes it particularly vulnerable to recessionary fears, even if the actual recession has not yet materialized.
Intensified Competition and Market Share Challenges
While Google’s dominance in search and advertising seems unassailable, the competitive landscape is ever-evolving. New threats and existing rivals are constantly vying for market share and user attention, posing a tangible risk to Alphabet’s various segments.
Shifting Sands in Digital Advertising
Google’s advertising empire, built on Search and YouTube, faces increasing pressure from multiple fronts. New platforms like TikTok have rapidly captured significant portions of digital ad spend, especially among younger demographics. TikTok’s algorithm-driven feed and highly engaging short-form video content offer advertisers unique ways to reach audiences, diverting ad dollars that might traditionally have gone to YouTube or other Google properties.
Furthermore, e-commerce giants like Amazon are aggressively expanding their own advertising platforms. As more shopping journeys begin directly on Amazon, brands are increasingly allocating their ad budgets to reach consumers at the point of purchase, directly challenging Google’s search advertising supremacy. Apple’s privacy changes, particularly App Tracking Transparency (ATT), have also complicated the targeting capabilities for advertisers across platforms, including Google. While Google has its own privacy initiatives, the broader industry shift towards more restrictive data policies can impact the effectiveness and thus the value of digital advertising, potentially leading to lower ad rates or reduced spending.
Cloud Computing Race and AI Supremacy
In the burgeoning cloud computing market, Google Cloud Platform (GCP) continues to battle formidable opponents in Amazon Web Services (AWS) and Microsoft Azure. While GCP has shown impressive growth, it still trails its two larger rivals in market share. The cloud wars are incredibly capital-intensive, requiring massive investments in data centers, infrastructure, and talent. GCP’s continued push for market share often comes with high operating costs, impacting overall corporate profitability, especially if growth doesn’t translate into equivalent gains in market share or improved margins.
More recently, the advent of sophisticated generative AI models like ChatGPT has ignited a new arms race, particularly in the realm of search and information retrieval. Microsoft’s aggressive integration of OpenAI’s technologies into Bing and other products poses a direct existential threat to Google’s foundational search business. While Google has its own formidable AI capabilities and has swiftly responded with its Bard AI and other integrations, investor concern mounts over the potential for AI-powered search to disrupt Google’s long-standing search ad revenue model. Any perception that Google is falling behind in this crucial technological shift can significantly erode investor confidence and drive down stock valuation.
Regulatory Scrutiny and Antitrust Concerns
Alphabet’s sheer size and market dominance have naturally attracted the attention of regulators worldwide. Increased governmental scrutiny and ongoing antitrust investigations represent a material risk to the company’s operational freedom and profitability.
Global Antitrust Lawsuits and Investigations
Google is currently embroiled in numerous antitrust lawsuits and investigations across the globe, including significant challenges from the U.S. Department of Justice (DOJ), the European Union, and various state attorneys general. These cases often target Google’s core business practices, such as its dominance in search advertising, its app store policies (Google Play), and its ad tech stack. The allegations often center on anti-competitive behavior, such as self-preferencing Google’s own services, stifling competition, and imposing unfair terms on advertisers and developers.
The legal battles are not only financially costly due to legal fees and potential fines but also create significant uncertainty for investors. A negative outcome in any of these major cases could result in severe penalties, forced changes to Google’s business model, or even the divestiture of certain assets. For instance, a ruling that forces Google to alter its ad tech operations could directly impact its revenue generation capabilities and operational efficiency. The ongoing nature of these legal challenges means that regulatory risk remains a persistent overhang on Google’s stock, as the market prices in the potential for adverse rulings.
Impact on Business Practices and Innovation
Beyond direct fines and structural remedies, regulatory pressure can also constrain Google’s ability to innovate and expand. Constant scrutiny might lead Google to self-regulate or tread more carefully in developing new products and services, particularly if they could be perceived as further extending its market dominance. This “chilling effect” could slow down the pace of innovation or prevent Google from entering new markets as aggressively as it might otherwise.
Furthermore, compliance with different regulatory frameworks across various jurisdictions adds complexity and cost to Google’s operations. Divergent rules regarding data privacy, content moderation, and competition necessitate significant investments in legal, compliance, and technological resources. These operational burdens, while necessary, can detract from profitability and agility, making it harder for Google to compete effectively and sustain its historical growth trajectory, thereby impacting investor perception and stock price.
Company-Specific Performance and Investor Outlook
Ultimately, a stock’s performance is intrinsically linked to the underlying company’s financial results and its future prospects. Disappointing earnings or a cautious outlook from management can significantly erode investor confidence.
Disappointing Earnings Reports and Slowing Revenue Growth
When Google’s stock drops, it often coincides with or is precipitated by a quarterly earnings report that misses analyst expectations. Missing on key metrics like revenue, earnings per share (EPS), or critical growth rates (e.g., Search ad revenue growth, YouTube ad revenue growth, or Google Cloud Platform growth) signals to the market that the company’s performance is not as robust as anticipated. Even if the numbers are still strong in absolute terms, a deviation from analyst consensus can be interpreted as a negative surprise.
Slowing revenue growth, especially in core segments like advertising, is a particular concern. For a company valued as a growth stock, a deceleration in top-line expansion can lead to a re-evaluation of its growth multiple. Investors might begin to question the sustainability of its historical growth rates, leading to a downward adjustment of its valuation. Profitability concerns, such as declining operating margins or increased operating expenses that aren’t matched by revenue growth, can further exacerbate the situation. Large investments in “Other Bets” (like Waymo or Verily) or new AI initiatives, while strategically important for the long term, can weigh on short-term profitability if they don’t show clear signs of monetization or market viability.
Future Growth Vectors and Market Confidence
While Google has numerous long-term growth opportunities, including artificial intelligence, autonomous driving (Waymo), and healthcare (Verily), the market often demands near-term clarity and execution. If investors perceive that these future growth vectors are too far off, too speculative, or require excessive investment without clear returns, it can impact confidence. Market sentiment can shift rapidly, and even a slight wobble in the perception of Google’s long-term competitive advantage or its ability to monetize new technologies can lead to significant stock movements.
A cautious outlook provided by management during earnings calls, concerns over capital expenditure plans, or a lack of clear guidance on future profitability can amplify these worries. Conversely, clear articulation of strategies for new product monetization, cost-cutting initiatives, or a strong growth outlook can quickly reverse negative sentiment. The interplay between current financial results and the company’s projected future performance is a delicate balance that significantly influences how investors value Alphabet’s stock at any given moment.

Conclusion
The question “why is Google stock dropping?” does not have a single, simple answer but rather a complex interplay of forces. From the macroeconomic headwinds of inflation and recession fears that impact advertising spending and valuation multiples, to the intensifying competition from new platforms and cloud rivals, and the ever-present specter of regulatory intervention, Alphabet faces a dynamic array of challenges. Company-specific performance, including missed earnings expectations and concerns over future growth vectors, further contributes to investor apprehension.
For investors, a drop in Google’s stock price necessitates a thorough reassessment of their investment thesis. It prompts a deeper look into the company’s resilience, its capacity for innovation, and its strategic responses to market shifts. While short-term fluctuations are an inherent part of stock market investing, understanding the underlying drivers of a decline allows for a more informed perspective on whether the drop represents a temporary setback or a more fundamental re-evaluation of one of the world’s most influential technology companies. Ultimately, the market is a forward-looking mechanism, and Google’s stock performance will continue to reflect investor confidence in its ability to navigate these challenges and sustain its long-term growth trajectory in an increasingly complex global economy.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.