
In the intricate world of personal and business finance, understanding the foundational elements of your banking relationship is paramount. Among these, your bank account number stands out as a critical identifier—a unique digital fingerprint that distinguishes your financial holdings from millions of others. For customers of major financial institutions like Chase Bank, knowing the specifics of this number, from its typical digit count to its broader implications, is not merely a matter of curiosity but a cornerstone of effective financial management and security.
This article delves into the specifics of Chase bank account numbers, demystifying their structure, guiding you on how to locate them, and crucially, elaborating on their significance within your overall financial ecosystem. We’ll explore why this seemingly simple string of numbers plays such a pivotal role, from facilitating everyday transactions to safeguarding your financial identity, all strictly within the context of personal finance, business finance, and financial tools.
The Core Identifier: Understanding Your Chase Account Number
At its heart, a bank account number is a unique sequence assigned by a financial institution to identify a specific account. While the question “how many digits” might seem straightforward, the answer can sometimes vary slightly, reflecting the complex internal systems banks use to manage vast numbers of accounts and product types. For Chase Bank, like many large U.S. banks, these numbers are designed to be robust and distinctive.
Typical Digit Count for Chase Checking and Savings Accounts
While Chase Bank does not publicly disclose a single, universal digit count for all its account numbers, common industry practice and observation reveal a general range. Typically, a Chase checking or savings account number will consist of between 10 and 12 digits. It’s important to understand that this is a general guideline. Some specific product types or legacy accounts might fall slightly outside this range, but these are exceptions rather than the rule. The longer length, compared to some older systems, provides a higher degree of uniqueness, crucial for a bank with millions of customers.
This digit count provides sufficient permutations to uniquely identify individual accounts across Chase’s expansive customer base. It’s a key piece of information that differentiates your specific checking or savings account from another, even if that other account belongs to someone with the exact same name. This uniqueness is foundational to the integrity of financial transactions.
Why Account Numbers Can Vary
The slight variation in digit count can be attributed to several factors within a large banking institution:
-
Internal System Architectures: Different types of accounts (e.g., standard checking, premium savings, specific business accounts) might be managed by slightly different internal systems, each with its own numbering scheme.
-
Product Evolution: Over time, as new financial products are introduced or existing ones are updated, the numbering conventions might evolve. A legacy account opened decades ago might have a slightly different structure than a new account opened today.
-
Acquisitions and Mergers: When banks merge or acquire other financial institutions, they often integrate different account numbering systems, leading to a broader range of valid account number lengths across the combined entity.
-
Security and Redundancy: The length and complexity of account numbers also contribute to security, making them harder to guess or generate fraudulently.
It’s crucial for account holders to know their specific account number rather than relying on a generic digit count, as this is the precise identifier required for all transactions.
The Distinction Between Account Numbers and Other Banking Identifiers
It’s common for individuals to confuse their bank account number with other financial identifiers. Understanding these distinctions is vital for proper financial management:
-
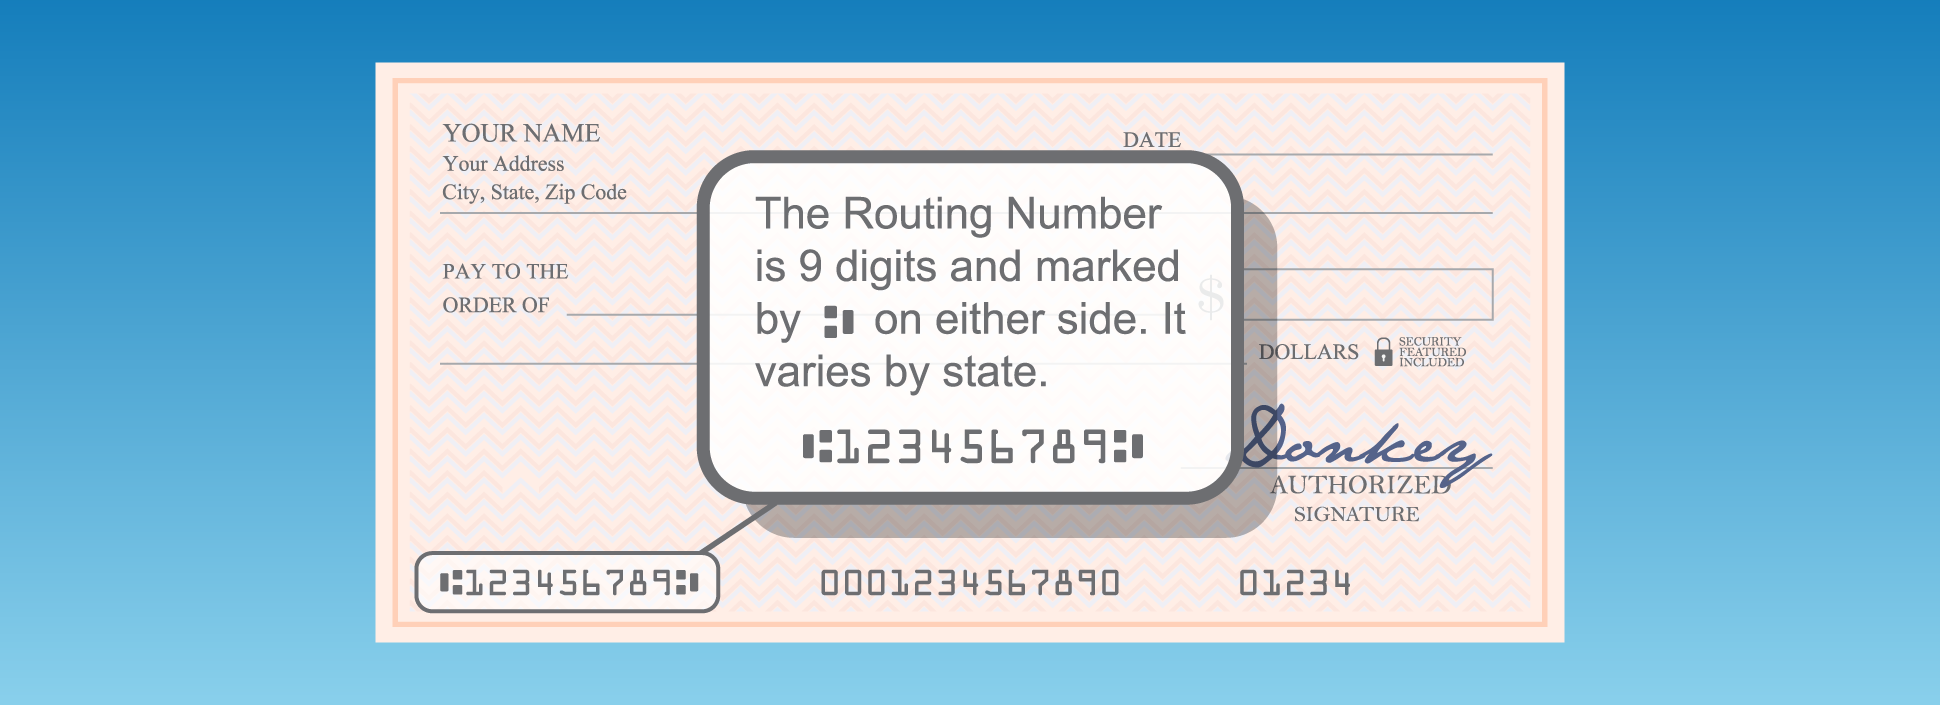
Routing Number: This is a nine-digit number that identifies your specific bank and its branch for transaction purposes, particularly within the U.S. financial system. It’s like the bank’s address.
-
Debit/Credit Card Number: These are typically 16-digit numbers (though some can vary, like Amex with 15 digits) found on the front of your plastic card. They are for point-of-sale and online purchases and are not your bank account number, although a debit card is linked to your checking account.
-
SWIFT/BIC Code: For international wire transfers, a SWIFT (Society for Worldwide Interbank Financial Telecommunication) or BIC (Bank Identifier Code) is used. This code identifies the specific bank and branch for international transactions.
Your bank account number is distinct from all these and serves its unique purpose as the direct identifier for your specific checking or savings ledger.
Navigating Your Finances: Locating Your Chase Account Number
Knowing the general digit count is one thing, but knowing your precise Chase account number is what truly matters. Fortunately, Chase provides multiple convenient and secure ways to access this critical information.
Physical Sources: Checks and Bank Statements
For many, the most traditional and readily accessible sources for their checking account number are physical documents:
-
Personal Checks: Your checking account number is prominently printed on the bottom of your personal checks, typically located between the routing number (on the left) and the check number (on the right). It’s usually the middle set of numbers. This is perhaps the most common way people retrieve their checking account number for various financial tasks.
-
Bank Statements: Whether you receive paper statements by mail or access digital PDFs, your full account number is always listed on your monthly or quarterly bank statements. This is a reliable source for both checking and savings account numbers. Always ensure you are viewing a full statement, as some summary views online might mask parts of the number for security.
Digital Access: Online Banking and Mobile App
In today’s digital age, your online banking portal and mobile app are often the quickest and most secure ways to find your account number:
-
Chase Online Banking: Log into your Chase online account. Once logged in, navigate to the specific account (checking, savings) you need information for. Look for details or account services. Chase typically provides an option to view your full account number, often requiring an additional verification step (like a security code sent to your phone) to ensure your identity.
-
Chase Mobile App: The Chase mobile app also allows you to access your account number. Similar to online banking, after logging in securely, select the desired account. There will usually be an option like “Show account number” or “Account details,” which, upon successful verification, will reveal the full number. The app’s biometric authentication (fingerprint, face ID) adds an extra layer of convenience and security to this process.
Direct Assistance: Contacting Chase Customer Service
If you’re unable to locate your account number through digital or physical means, or if you prefer speaking to a representative, Chase customer service is always an option.
-
Phone Support: Call Chase’s customer service line. Be prepared to go through rigorous identity verification processes, which might include answering security questions, providing personal details, or verifying recent transactions. This is for your protection.
-
Branch Visit: For in-person assistance, visit any Chase branch. A banker can help you retrieve your account number after verifying your identity with a valid government-issued ID.
Using any of these methods ensures you accurately retrieve your account number, a critical step before engaging in any transactions requiring it.
Beyond the Digits: The Broader Role of Your Account Number in Financial Management
While knowing your account number is fundamental, its utility extends far beyond mere identification. It’s a central component in numerous financial activities and plays a crucial role in maintaining your financial health and security.
Facilitating Transactions: Direct Deposits, ACH Transfers, and Bill Pay
Your bank account number, often paired with your bank’s routing number, is the key to executing a wide array of electronic financial transactions:
-
Direct Deposits: For receiving your salary, government benefits, tax refunds, or other regular payments, your employer or payer will require both your account and routing numbers to ensure funds are deposited directly into your designated account. This eliminates the need for physical checks and speeds up access to funds.
-
Automated Clearing House (ACH) Transfers: This electronic network facilitates interbank transactions within the U.S. Your account number is essential for setting up recurring payments (like mortgage, rent, or utility bills) and for electronic fund transfers between your accounts at different institutions.
-
Bill Pay: While many bill pay services only require the payee’s information, for certain types of payments or direct debits, providing your account number to a service provider authorizes them to withdraw funds directly from your account.
Security Implications: Protecting Your Financial Identity
Just as your account number enables convenient transactions, its exposure can pose security risks. It’s a vital piece of information that, if it falls into the wrong hands, could be exploited.
-
Fraud and Identity Theft: While an account number alone isn’t always enough for large-scale identity theft, combined with other personal information, it can be used to initiate unauthorized transactions, set up fraudulent accounts, or gain access to your funds.
-
Phishing Scams: Fraudsters often try to trick individuals into revealing their account numbers and other sensitive data through deceptive emails, texts, or calls purporting to be from banks or legitimate organizations.
Understanding these risks underscores the importance of treating your account number with the same care you would your Social Security number or credit card details.
Linking Accounts and Financial Tools: Personal Finance Management (PFM) Apps, External Services
In the era of digital finance, your bank account number is also critical for integrating your financial life with various tools and services designed to enhance management:
-
Personal Finance Management (PFM) Apps: Many popular budgeting and investment apps (e.g., Mint, YNAB, Personal Capital) allow you to link your bank accounts to track spending, monitor balances, and categorize transactions. While some use secure third-party aggregators that don’t directly require your account number, others might, especially for setting up direct transfers.
-
External Investment and Brokerage Accounts: When funding an investment account or transferring money between your bank and brokerage, your bank account number is typically required to link these accounts for seamless electronic funds transfers.
-
Payment Services: Some peer-to-peer payment platforms or online wallets might offer options to link your bank account directly for larger transfers or specific features, again requiring your account number.
This connectivity highlights the account number’s role as a bridge between different financial components of your life.
Safeguarding Your Financial Information: Best Practices for Account Security
Given the critical nature of your Chase bank account number, adopting robust security practices is non-negotiable for maintaining financial well-being and preventing fraud.
Knowing When and How to Share Your Account Number
While prudence is advised, there are legitimate scenarios where sharing your account number is necessary:
-
Setting up Direct Deposit: For payroll, benefits, or tax refunds.
-
Authorizing Recurring Payments: For legitimate billers like mortgage lenders, utility companies, or insurance providers.
-
Linking Accounts: To legitimate investment platforms or trusted financial tools.
-
With Your Bank: When communicating directly with Chase for customer service or specific transactions, they may require it after verifying your identity.
However, you should never share your full account number in response to unsolicited emails, texts, or calls, or on unsecured websites. Legitimate institutions will rarely ask for your full account number via email or text. Be suspicious of requests for immediate action or threats if you don’t comply.
Recognizing and Avoiding Common Scams
Financial scams are constantly evolving. Awareness is your best defense:
-
Phishing and Smishing: Emails (phishing) or texts (smishing) designed to look like they’re from Chase or other trusted entities, asking you to click a link and enter your account details. Always check the sender’s email address and hover over links before clicking.
-
Vishing (Voice Phishing): Phone calls from imposters claiming to be from Chase, emergency services, or government agencies, attempting to trick you into revealing personal information. Chase will never ask for your full account number or PIN over the phone unless you initiated the call to a verified number and have gone through robust security protocols.
-
Identity Theft: Be vigilant for signs of identity theft, such as unauthorized transactions, unexpected bills, or calls from debt collectors for debts you don’t owe. Regularly review your bank statements and credit reports.
Leveraging Chase’s Security Features
Chase, like other major banks, invests heavily in security measures to protect its customers:
-
Two-Factor Authentication (2FA): Always enable 2FA for your online banking. This adds an extra layer of security by requiring a code sent to your phone or email, in addition to your password, when logging in from a new device.
-
Account Alerts: Set up alerts for various account activities, such as large withdrawals, online transactions, or changes to your personal information. These real-time notifications can help you detect suspicious activity quickly.
-
Secure Browsing: Always ensure you are on Chase’s official website (look for “https://” and a padlock icon in the address bar) when logging in. Avoid using public Wi-Fi for banking transactions unless you are using a secure VPN.
-
Regular Monitoring: Routinely check your Chase bank statements and transaction history for any unauthorized activity. Report any discrepancies immediately.
By combining your knowledge of how your account number functions with proactive security habits, you create a robust defense against financial fraud and ensure the secure management of your funds.
The Ecosystem of Banking Identifiers: Account Numbers, Routing Numbers, and More
While our focus has been on the Chase bank account number, it exists within a larger ecosystem of banking identifiers, each serving a specific, crucial function. Understanding their interrelationship provides a comprehensive view of how money moves within the modern financial system.
Routing Numbers: The Bank’s Address
As mentioned, the routing number (also known as an ABA routing transit number) is a nine-digit code that identifies the financial institution and its physical location involved in a transaction. In the U.S., every bank and credit union has at least one routing number, and larger banks like Chase may have several, depending on the region or specific type of transaction. For instance, Chase might have different routing numbers for wire transfers versus ACH transfers, or for different states. When you set up direct deposit or make an electronic payment, the combination of your routing number and account number acts like a full mailing address, ensuring funds reach the correct bank and then the correct individual account within that bank.
Debit/Credit Card Numbers: For Point-of-Sale and Online Purchases
Debit and credit card numbers are distinct from account numbers. While a debit card is linked to your checking account, its primary function is to facilitate transactions at merchant terminals (point-of-sale) or online payment gateways without directly exposing your bank account number. The card number, along with the expiration date and CVV/CVC code, is designed for immediate transaction authorization. When you swipe or insert your card, the card network (e.g., Visa, Mastercard) processes the payment, which then debits your linked checking account (for debit cards) or charges your credit line (for credit cards). This abstraction layer provides an added security measure, as your core account number is not directly transmitted during a typical card transaction.
SWIFT/BIC Codes: Enabling International Transfers
For transactions that cross international borders, a different set of identifiers comes into play: SWIFT (Society for Worldwide Interbank Financial Telecommunication) or BIC (Bank Identifier Code) codes. These are standardized international codes (typically 8 or 11 characters) that identify a specific bank and branch participating in an international transaction. When you send or receive a wire transfer from abroad, you’ll need Chase’s specific SWIFT/BIC code in addition to the recipient’s bank account number. This global network ensures that funds can be accurately routed between banks in different countries, navigating diverse banking systems and currencies.

The Interplay of Identifiers in Modern Banking
The synergy between these identifiers—account numbers, routing numbers, card numbers, and SWIFT/BIC codes—is what enables the seamless, secure, and rapid movement of money in today’s financial landscape. Each has its specific domain of utility, complementing the others to create a robust and efficient global financial system. Your Chase bank account number, while a single piece of information, is thus a vital cog in this sophisticated financial machinery, essential for both your personal financial operations and your interaction with the broader economic world. Understanding its nature, how to find it, and how to protect it is not just practical; it’s a fundamental aspect of intelligent financial literacy.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.