
In the modern financial landscape, a debit card is far more than just a piece of plastic; it’s a fundamental tool for managing your money, executing everyday transactions, and maintaining a clear picture of your personal finances. For customers of J.P. Morgan Chase, one of the largest and most prominent financial institutions globally, their debit card serves as the primary gateway to their banking accounts. Whether you’ve lost your card, it’s expired, or you’re simply opening a new account, understanding the process of obtaining a new Chase debit card is crucial for uninterrupted access to your funds and effective financial management.
This guide delves into the various scenarios that might necessitate a new card, walks you through the practical steps to acquire one, and offers insights into how to integrate this essential financial instrument seamlessly into your broader personal finance strategy. We’ll explore not just the mechanics of ordering a card, but also the financial considerations, security best practices, and digital tools that empower you to leverage your Chase debit card for optimal control over your money.
The Indispensable Role of Your Debit Card in Modern Finance
At the heart of most personal financial strategies lies the debit card. It’s the tangible link between your digital bank account and the myriad of transactions that define daily life. Understanding its function and strategic importance is the first step in effective money management.
What is a Debit Card and Why is it Essential?
A debit card provides direct access to the funds in your checking account. Unlike a credit card, which allows you to borrow money up to a certain limit, a debit card only allows you to spend money you already possess. This fundamental difference makes it an incredibly powerful tool for budgeting and preventing debt. It’s essential because it offers unparalleled convenience for purchases, ATM withdrawals, and online transactions, effectively replacing cash and checks for many day-to-day financial activities. For anyone looking to maintain strict control over their spending, a debit card acts as a real-time ledger, deducting funds immediately and often making it easier to track expenditures. Moreover, the ubiquity of debit cards means you can manage your finances almost anywhere, from local grocery stores to international online retailers.
Distinguishing Debit from Credit: A Financial Perspective
While both debit and credit cards facilitate cashless transactions, their financial implications are vastly different. A credit card extends a line of credit, which you are obligated to repay, often with interest. Mismanaging credit can lead to debt accumulation and negatively impact your credit score. A debit card, on the other hand, operates on your own money, drawing directly from your checking account. This makes it an ideal instrument for those prioritizing debt avoidance and living within their means. From a financial planning standpoint, relying primarily on a debit card for routine expenses can instill disciplined spending habits, as you’re constantly aware of your available balance. It’s a key component for fostering financial responsibility and avoiding the pitfalls of overspending.
The Benefits of a Chase Debit Card for Everyday Transactions
A Chase debit card comes with a suite of features designed to enhance security and convenience for its users. Beyond merely spending your own money, Chase debit cards often include advanced fraud protection measures, such as real-time alerts for suspicious activity and zero-liability protection against unauthorized purchases. This adds a crucial layer of security, providing peace of mind as you conduct transactions. Furthermore, Chase offers extensive ATM networks, allowing for easy cash withdrawals and deposits without fees. For online shoppers, the card provides a secure way to pay, often integrated with digital wallets for added convenience. For individuals committed to astute personal finance, a Chase debit card is more than a transaction tool; it’s an enabler for budgeting, a guardian against overspending, and a secure portal to your financial resources.
Common Scenarios Necessitating a New Chase Debit Card
Life happens, and sometimes, those events directly impact the functionality and security of your financial tools. Understanding the typical scenarios that call for a new Chase debit card is crucial for proactive financial management and minimizing disruption to your daily financial activities.
Lost or Stolen Cards: Immediate Financial Protection
One of the most urgent reasons to get a new debit card is when your current one is lost or stolen. In such situations, time is of the essence. The immediate priority is to protect your funds from unauthorized access. Chase, like other reputable financial institutions, has robust procedures for reporting a lost or stolen card. This typically involves contacting them immediately, either through their mobile app, online banking platform, or dedicated customer service line. Upon reporting, Chase will promptly deactivate your old card, preventing any further fraudulent transactions. Requesting a new card in this scenario is not just about convenience; it’s a critical step in safeguarding your financial assets and mitigating potential losses, reinforcing the security aspect of your personal finance strategy.
Expired or Damaged Cards: Maintaining Seamless Access to Funds
Debit cards, like all physical objects, have a finite lifespan. They can expire after a few years, or they can become damaged through wear and tear, rendering them unreadable by card readers or ATMs. While an expired card might seem like a minor inconvenience, it can disrupt recurring payments, subscription services, and everyday purchases. Proactive replacement is key here. Chase typically mails a new card to you a month or so before your current card’s expiration date. However, if your card is damaged, you’ll need to initiate a request for a replacement. Ensuring you have a functional, unexpired card is vital for uninterrupted access to your funds, especially for critical financial obligations like bill payments and essential expenditures.
Opening a New Chase Account: The Foundation of Your Banking Relationship
For those new to Chase or opening an additional account (e.g., a new checking account for a specific savings goal or business), a new debit card is a natural and expected part of the process. When you establish a new banking relationship with Chase, a debit card is typically issued automatically to provide you with immediate and convenient access to your newly deposited funds. This foundational step is crucial for integrating your new account into your overall financial ecosystem. It allows you to start making deposits, withdrawals, and purchases right away, solidifying your engagement with Chase’s banking services and providing a tangible link to your financial resources. Choosing the right type of account for your needs is a core personal finance decision, and the debit card is the operational tool that brings that choice to life.
Security Concerns and Proactive Replacements
Beyond overt incidents like loss or theft, there might be situations where you simply feel a need for enhanced security. For example, if you’ve used your card at a merchant that later reports a data breach, even if your card hasn’t shown fraudulent activity, you might opt for a proactive replacement. This is a personal finance decision driven by risk management. While Chase has sophisticated fraud detection systems, choosing to replace a card proactively can offer an additional layer of peace of mind, ensuring that your financial data remains as secure as possible. It’s an assertion of control over your financial security, allowing you to preemptively mitigate potential future risks.
A Step-by-Step Guide to Requesting Your New Chase Debit Card
Acquiring a new Chase debit card is designed to be a straightforward process, catering to various preferences and levels of urgency. Whether you prefer digital convenience, direct human interaction, or an in-person visit, Chase offers multiple avenues to ensure you regain access to your funds promptly.
Online Through Chase’s Digital Banking Platform
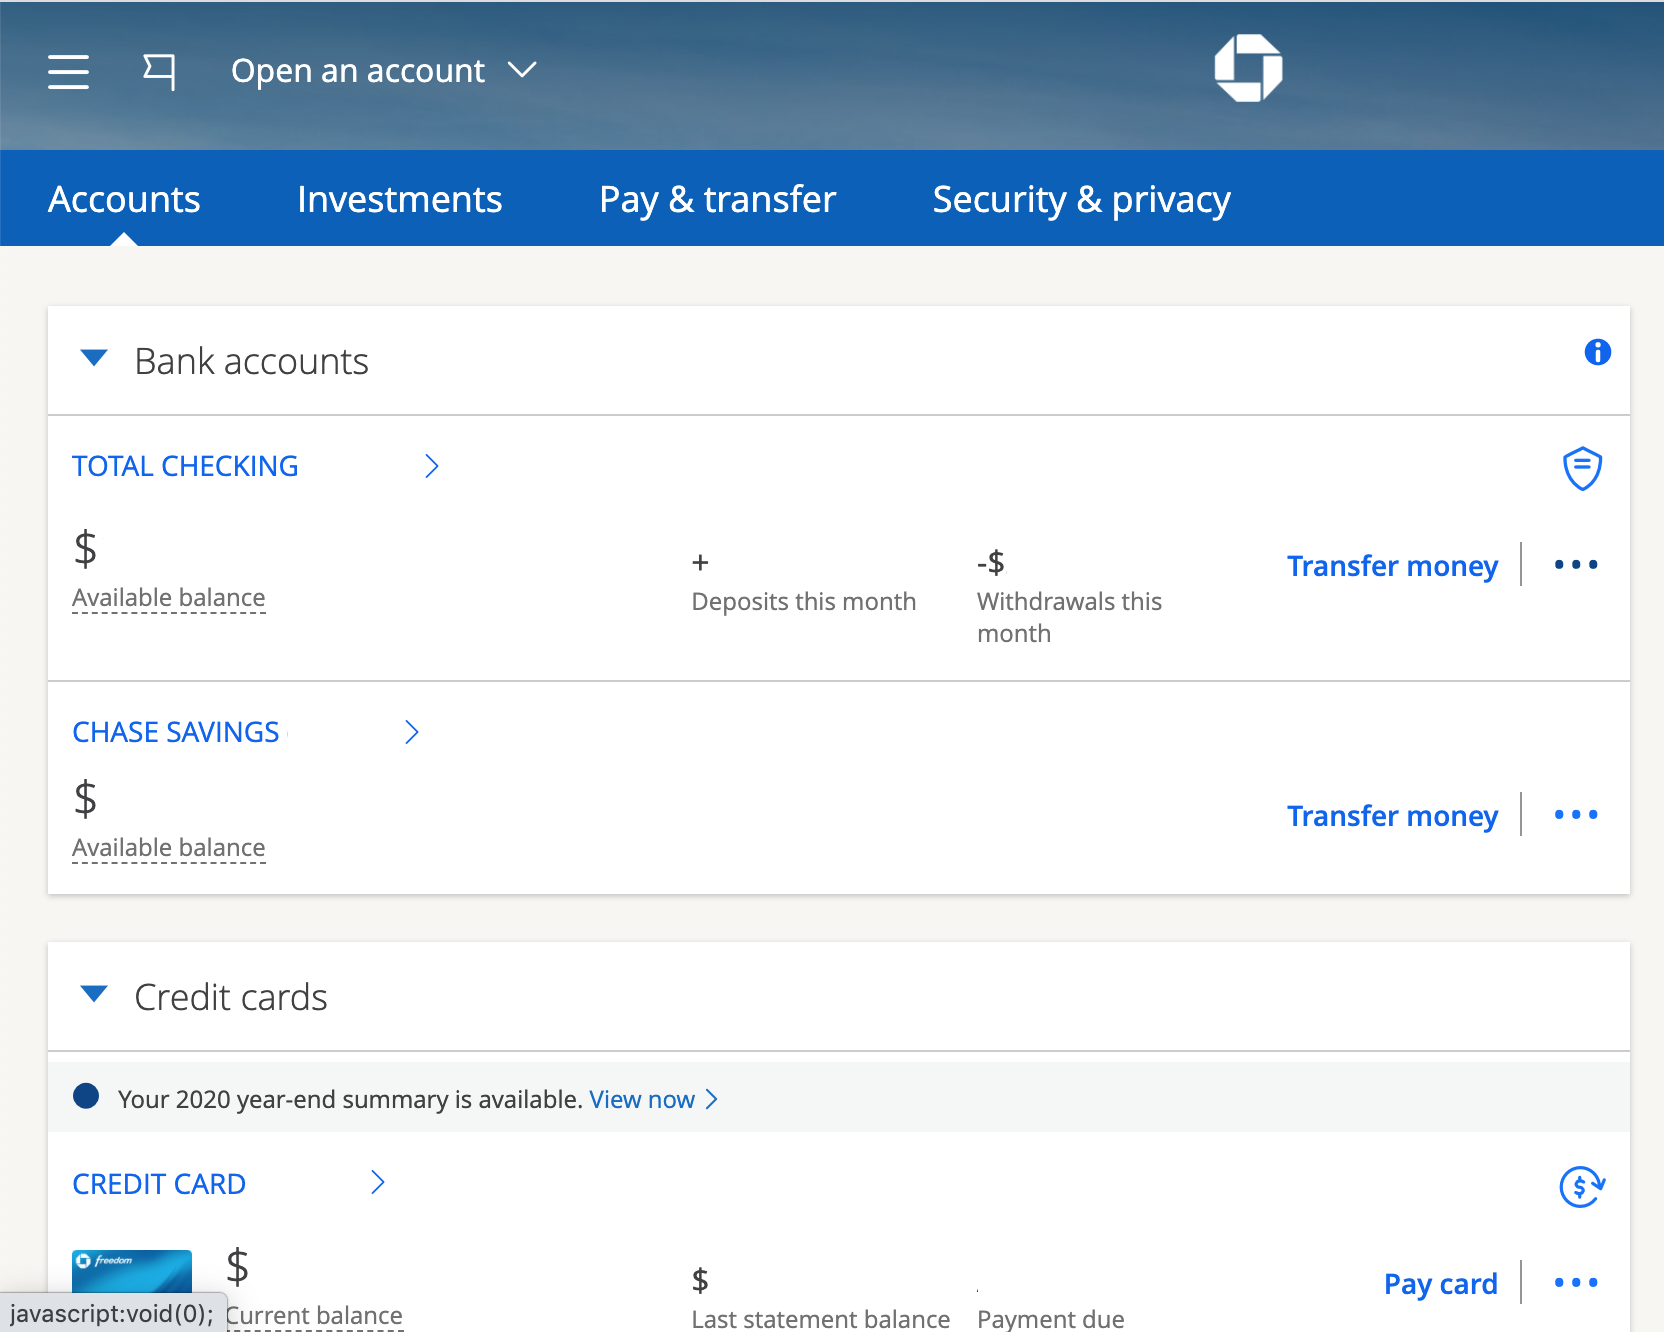
For many, the most convenient method to request a new debit card is through Chase’s secure online banking platform or the Chase Mobile app. After logging in, navigate to the “Customer Service” or “Account Services” section. Here, you’ll typically find an option like “Order a replacement card,” “Report a lost/stolen card,” or “Manage cards.” The system will guide you through confirming your mailing address and the reason for the replacement. This digital approach is efficient, available 24/7, and provides immediate confirmation of your request. It’s a testament to how digital tools have streamlined personal finance management, allowing you to handle essential banking tasks from the comfort of your home or on the go.
Via Phone: Direct Assistance from Chase Customer Service

If you prefer speaking directly with a representative or have specific questions about your account, calling Chase customer service is an excellent option. The dedicated number for debit card services is typically found on the back of your existing card, on Chase’s website, or within the mobile app. Be prepared to verify your identity through various security questions. The representative can then process your request, provide an estimated delivery date, and answer any concerns you might have regarding your account or the new card’s features. This method offers personalized assistance and can be particularly helpful in complex situations or when immediate action, such as blocking a lost card, is required alongside ordering a replacement.
In-Person at a Chase Branch
For those who prefer face-to-face interaction or require immediate card issuance, visiting a local Chase branch is an effective solution. Many Chase branches offer instant debit card issuance, meaning you can walk out with a fully activated card on the same day. This is an invaluable benefit if you’ve lost your card and need immediate access to cash or urgently need to make a purchase. When visiting a branch, remember to bring a valid form of identification (e.g., driver’s license, passport) for verification purposes. The in-person experience combines the convenience of immediate access with the assurance of speaking with a banking professional who can address all your financial needs.
Expedited Delivery Options and Associated Costs
In situations where you need your new debit card urgently, Chase typically offers expedited shipping options. While standard delivery usually takes 5-7 business days, expedited shipping can reduce this timeframe significantly, often to 2-3 business days or even overnight. It’s important to note that expedited delivery usually incurs an additional fee, which will be disclosed during the request process. For critical financial needs, such as upcoming travel or an unexpected emergency requiring immediate access to funds, this option can be a worthwhile investment. Always weigh the cost against the urgency of your financial need when considering expedited delivery.
Activating and Securing Your New Debit Card for Financial Peace of Mind
Receiving your new Chase debit card is only half the battle. The crucial next steps involve activation and implementing robust security measures to ensure your funds remain protected and your financial operations continue smoothly. These post-acquisition actions are vital components of responsible personal finance.
Activating Your Card: Essential for Transaction Readiness
Once your new Chase debit card arrives, the very first step is to activate it. An inactivated card is essentially useless for transactions. Chase offers multiple convenient ways to activate your card:
-
Online: Log in to your Chase online banking account or mobile app, navigate to the “Customer Service” or “Card Services” section, and follow the prompts to activate.
-
By Phone: Call the activation number provided on the sticker affixed to your new card or use the general customer service number. You’ll typically be guided through an automated system or speak with a representative to complete the activation process.
-
At a Chase ATM: Insert your card into a Chase ATM, enter your PIN (if you’ve received one or set it up), and conduct a transaction like checking your balance. This often activates the card automatically.
Activating your card promptly ensures you have uninterrupted access to your funds and can begin using it for purchases and withdrawals without delay.
Setting Up Your PIN: A Crucial Security Layer
Your Personal Identification Number (PIN) is a critical security feature for your debit card, required for ATM withdrawals and many in-store transactions. When you receive a new card, you may be prompted to set up a new PIN online or by phone, or Chase might send you a temporary PIN that you can change later. It’s paramount to choose a PIN that is easy for you to remember but difficult for others to guess (avoid birthdays, consecutive numbers, or repetitive digits). Never write your PIN down or share it with anyone. Regularly changing your PIN, or if you suspect it might have been compromised, is a good financial security practice that significantly reduces the risk of unauthorized access to your funds.
Updating Recurring Payments: Avoiding Financial Disruptions
One of the most commonly overlooked steps when getting a new debit card is updating recurring payments. Many individuals have automatic payments set up for utilities, subscription services, loan repayments, and other bills. Since your new card will have a new card number and expiration date, these automatic payments tied to your old card will fail. This can lead to late fees, service interruptions, and credit score impacts. As part of your financial diligence, create a list of all services linked to your old debit card and update them with the new card details as soon as possible. This proactive measure ensures financial continuity and prevents unnecessary complications in your bill payment schedule.
Vigilant Monitoring: Protecting Your Account from Fraud
Even with a new card and strong PIN, ongoing vigilance is key to protecting your financial assets. Chase offers various tools to help you monitor your account for suspicious activity:
-
Account Alerts: Set up email or text alerts for transactions above a certain amount, international purchases, or any activity that falls outside your normal spending patterns.
-
Regular Statement Review: Periodically review your bank statements and transaction history through the Chase Mobile app or online banking. Report any unfamiliar transactions immediately.
-
Zero-Liability Protection: Be aware of Chase’s zero-liability policy, which protects you from unauthorized purchases, provided you report them in a timely manner.
These practices are fundamental to a robust personal finance security strategy, allowing you to quickly identify and address potential fraud, thereby safeguarding your hard-earned money.
Maximizing Your Chase Debit Card for Optimal Financial Management
A new Chase debit card is more than just a replacement for an old one; it’s an opportunity to refine your financial habits and leverage Chase’s tools for more effective money management. Integrating your debit card strategically into your financial planning can yield significant benefits.
Budgeting with Your Debit Card: Tracking Every Dollar
One of the most powerful aspects of using a debit card is its ability to facilitate real-time budgeting. Since every transaction directly debits your account, you have an immediate and accurate record of your spending. Many personal finance apps and Chase’s own digital banking platform allow you to categorize transactions, visualize spending patterns, and set budgets for different categories (e.g., groceries, entertainment, transportation). By consistently reviewing your debit card transactions, you can identify areas where you might be overspending, make adjustments, and adhere more closely to your financial goals. It provides a transparent overview of where your money is going, empowering you to make informed financial decisions.
International Use and Travel Considerations
If your financial activities involve international travel or online purchases from foreign merchants, understanding how your Chase debit card functions abroad is crucial. Before traveling, it’s wise to notify Chase of your travel plans to prevent your card from being flagged for suspicious activity. Be aware of potential foreign transaction fees, which can add up over time. While debit cards offer convenience, using a no-foreign-transaction-fee credit card might be more financially advantageous for international spending. Additionally, familiarize yourself with currency conversion rates and the availability of ATMs in your destination. Strategic planning regarding international use ensures you maintain access to your funds while minimizing unnecessary costs, a key aspect of astute personal finance.
Leveraging Chase’s Digital Tools for Enhanced Control
Chase provides a comprehensive suite of digital tools through its mobile app and online banking platform, which significantly enhance your ability to manage your debit card and overall finances. These tools include:
-
Account Alerts: Customizable alerts for balances, transactions, and potential fraud.
-
Spending Insights: Categorized spending reports to help you track and budget.
-
Zelle: A fast, free, and secure way to send and receive money with friends and family directly from your Chase account.
-
Card Lock/Unlock: The ability to temporarily lock your card through the app if you misplace it, and unlock it when found, preventing unauthorized use.
Actively utilizing these features provides a granular level of control over your finances, making it easier to monitor, manage, and protect your money from anywhere, at any time.
Debit Card Overdraft Protection: Understanding Your Options
Overdraft protection for your debit card is an important financial consideration. Chase typically offers options to link your checking account to a savings account or a line of credit to cover transactions that exceed your available balance. While this can prevent declines, it often comes with fees. It’s crucial to understand Chase’s overdraft policy, including fees, and to decide whether to opt-in or opt-out of overdraft protection for ATM and everyday debit card transactions. For prudent financial management, avoiding overdrafts altogether through careful budgeting and monitoring your account balance is ideal. However, understanding your options provides a safety net while emphasizing the importance of managing your money within your means.
Obtaining a new Chase debit card is a straightforward process, but it’s also an opportunity to reinforce your commitment to strong personal financial management. By understanding the reasons for replacement, navigating the request process efficiently, activating and securing your card diligently, and leveraging its features for budgeting and oversight, you transform a simple banking transaction into a strategic move for greater financial control and peace of mind. Your Chase debit card is a powerful financial instrument; mastering its use is a cornerstone of effective money management in today’s digital age.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.