
At first glance, the question “what is 3/4 in fraction form?” might seem like a relic from elementary school math class. It’s a simple, fundamental concept that most of us learned years ago. However, dismiss this basic query at your peril, especially when it comes to managing your money. In the complex world of personal finance, investing, and business, a solid grasp of fractions, and the ability to interpret them, is not just helpful—it’s essential. From calculating interest rates and understanding investment returns to budgeting your monthly income and evaluating debt, fractions are the silent architects of nearly every financial decision you make.
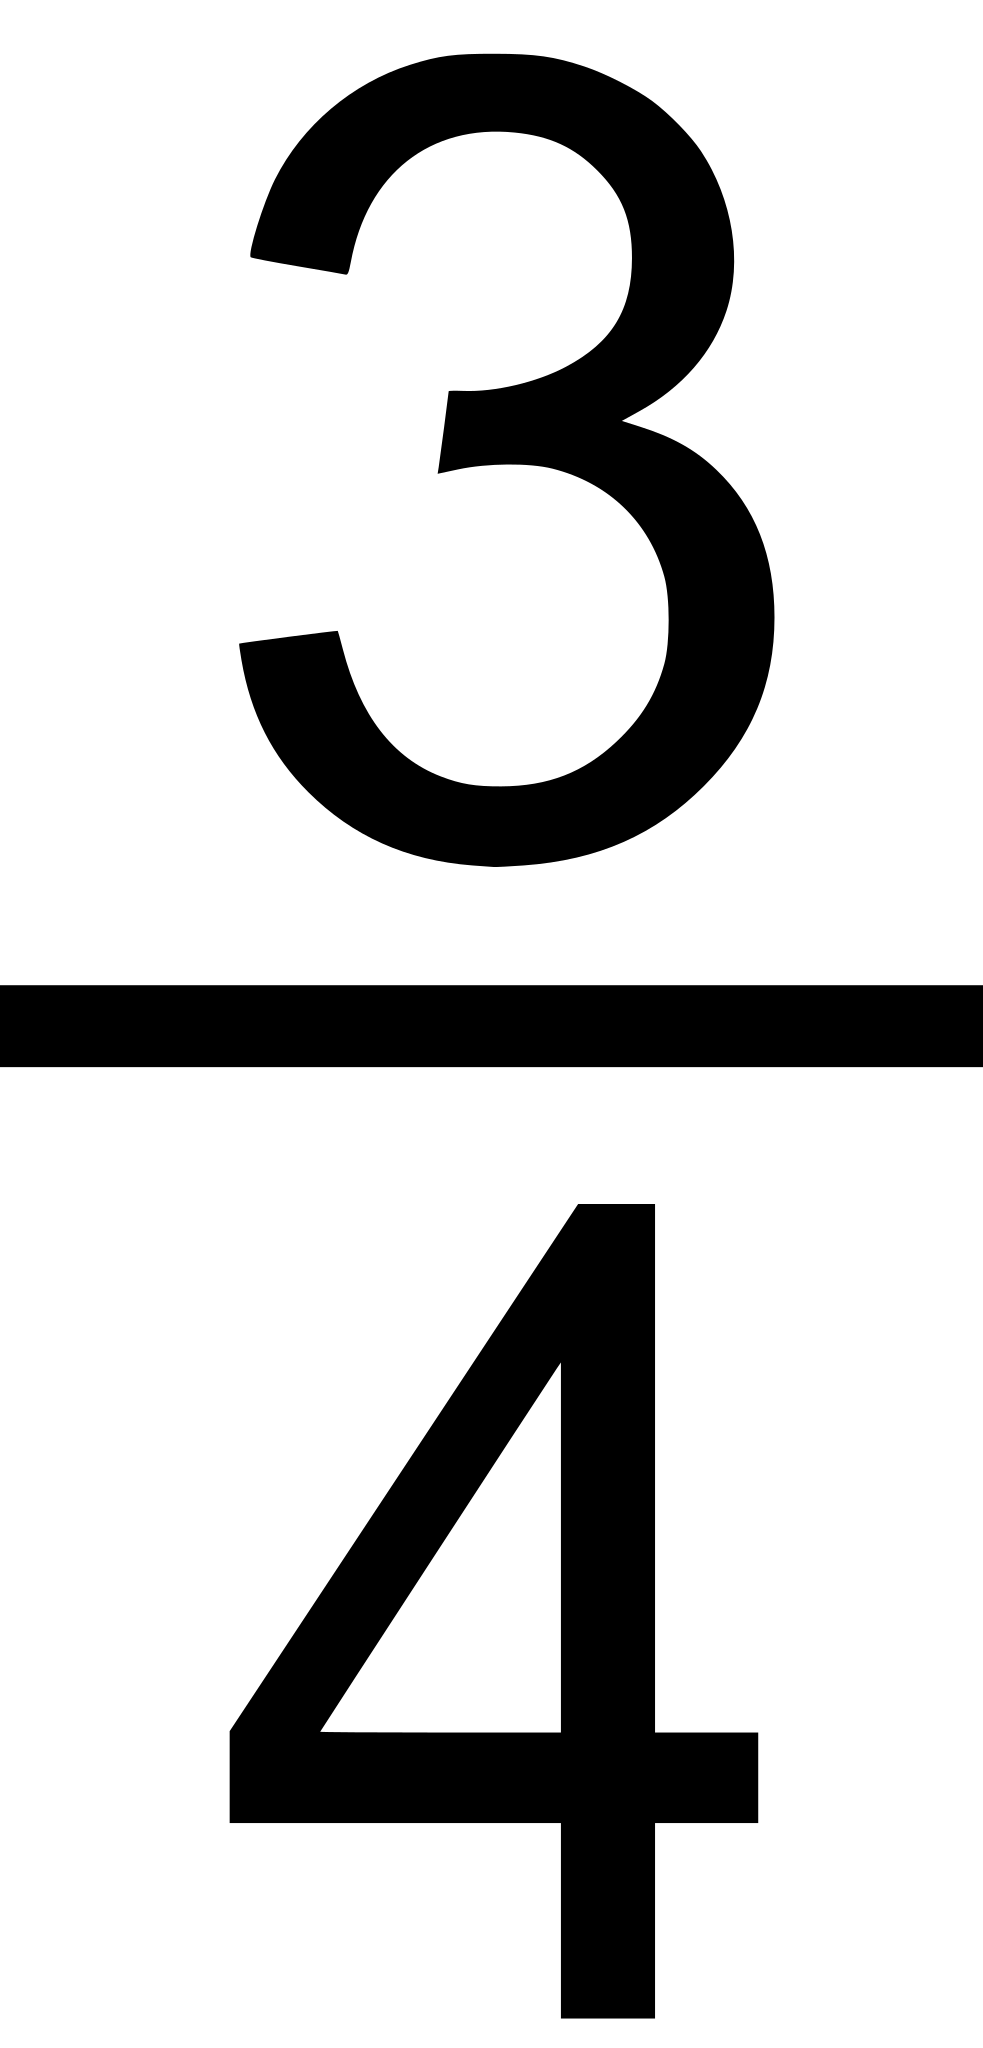
This article will delve into the deceptively simple concept of 3/4, unpacking its meaning and, more importantly, exploring the profound ways in which this foundational mathematical understanding empowers you to navigate the intricate landscape of your financial life. We will uncover how mastering fractions can transform you from a passive participant to an active, informed decision-maker in the pursuit of financial well-being.
The Foundational Role of Fractions in Financial Literacy
Before we can appreciate the practical applications of fractions in finance, it’s crucial to reaffirm our understanding of what a fraction truly represents. This basic comprehension forms the bedrock upon which all more complex financial calculations and interpretations are built. Without it, the percentages, interest rates, and allocation strategies that dominate financial discussions would be opaque and confusing.
Understanding Basic Fractional Representation (The “What” of 3/4)
A fraction, in its essence, represents a part of a whole. It’s written as a numerator (the top number) over a denominator (the bottom number), separated by a line. In the case of “3/4,” the number 3 is the numerator, and 4 is the denominator. This literally means “three out of four equal parts.” Imagine a dollar divided into four quarters; if you have three of those quarters, you have 3/4 of a dollar, or 75 cents. This simple example illustrates a core concept: fractions break down a larger entity into understandable, manageable portions.
In a financial context, this translates directly to situations where resources, profits, or expenditures need to be divided. If a partnership dictates that you receive 3/4 of the profits, you instantly understand your share relative to the total. If a budget allocates 3/4 of a certain fund to a specific project, you can visualize the proportion and impact. The ability to quickly grasp these relationships without needing a calculator is a hallmark of strong financial literacy, allowing for faster decision-making and a clearer understanding of your financial standing.
Bridging Fractions to Percentages and Decimals (The “How” of Conversion)
While fractions are fundamental, the financial world often prefers to communicate in decimals and percentages. This is where the true power of understanding fractions like 3/4 comes into play: the seamless ability to convert between these forms.
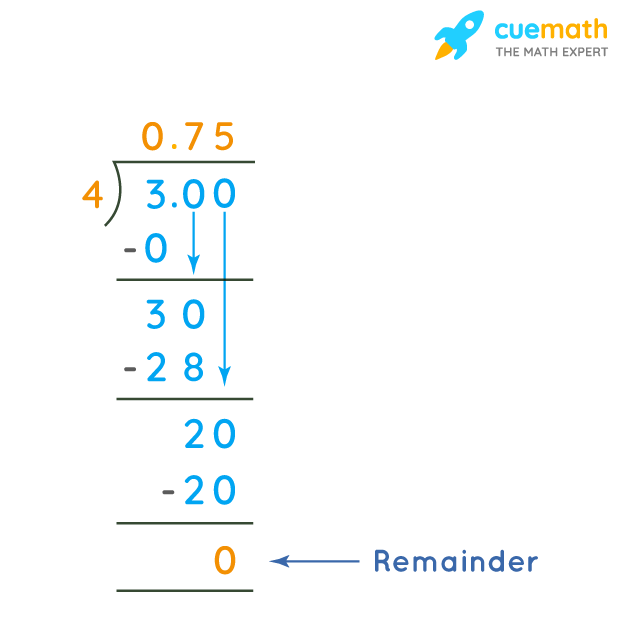
To convert a fraction to a decimal, you simply divide the numerator by the denominator. For 3/4, this means 3 ÷ 4 = 0.75. To convert a decimal to a percentage, you multiply by 100. So, 0.75 x 100 = 75%. Thus, 3/4 is equivalent to 0.75 and 75%.
This interchangeability is critical in finance. When a stock’s value rises by 0.75 points, or an interest rate is expressed as 3/4 of a percentage point, or a financial report shows 75% market share, a financially literate individual can instantly connect these figures. They know that these are all different ways of expressing the same proportion. This flexibility allows for better comparison, analysis, and communication of financial data, making complex reports more accessible and decision-making more intuitive. Being able to mentally switch between these forms is a key skill for interpreting everything from sales figures to investment growth.
Fractions in Personal Budgeting and Expense Management
Effective personal finance begins with a robust budget. At its core, budgeting is an exercise in fractional allocation—dividing your income into various categories for needs, wants, and savings. Understanding fractions makes this process intuitive and powerful, transforming arbitrary numbers into proportional, actionable insights.
Allocating Income with Fractional Thinking
Many popular budgeting strategies are inherently fractional. Consider the widely adopted 50/30/20 rule: 50% of your income for needs, 30% for wants, and 20% for savings and debt repayment. Expressed in fractions, this is 1/2 for needs, 3/10 for wants, and 1/5 for savings. While the rule uses percentages, the underlying logic is entirely fractional. When you budget, you are essentially asking: “What fraction of my income am I dedicating to housing, food, transportation, and discretionary spending?”
Imagine you earn $4,000 per month. If you decide that 3/4 of your income will be allocated to essential living expenses (rent, utilities, groceries), you immediately calculate that $3,000 (0.75 x $4,000) will be spent on these items. This fractional approach provides a clear visual of how much of your total financial pie each category consumes. It helps you identify if any single category is disproportionately large, perhaps taking up more than its fair “fraction” of your funds, and allows you to adjust accordingly. This proportional view of your finances is far more insightful than simply looking at raw dollar amounts alone.
Tracking and Reducing Fractional Spending
Beyond initial allocation, fractions are invaluable in tracking where your money actually goes and identifying areas for reduction. Often, small, seemingly insignificant expenditures accumulate to substantial amounts over time. These are “fractions” of your budget that, if left unchecked, can derail your financial goals.
For example, if you realize that 3/4 of your weekly entertainment budget is consistently spent on impulse purchases, understanding this fractional breakdown highlights a specific area for intervention. Similarly, discovering that a recurring subscription accounts for a surprising fraction (say, 1/10 or even 1/20) of your monthly discretionary spending can prompt you to re-evaluate its necessity. By thinking in terms of “what fraction of my monthly coffee budget,” or “what fraction of my transportation costs,” you can pinpoint leakages more effectively. Cutting even a small fraction from multiple categories can free up significant funds for savings or debt repayment, demonstrating the power of micro-adjustments guided by fractional understanding.
Investing and Wealth Building: The Fractional Advantage

In the realm of investing, fractions are not just theoretical concepts; they are the language of returns, diversification, and ownership. A nuanced understanding of fractions can significantly enhance your ability to make informed investment decisions, manage risk, and grow your wealth effectively.
Understanding Investment Returns and Dividends
Investment performance is almost universally expressed in percentages, which, as we know, are direct derivatives of fractions. A stock that returns 75% on your investment means you’ve gained 3/4 of your initial capital back in profit. Understanding this fractional relationship allows for quicker mental calculations and comparisons of different investment opportunities.
Furthermore, the concept of fractional shares has revolutionized investing, making it more accessible. Historically, if a stock was priced at $1,000 per share, you needed $1,000 to buy it. Now, many platforms allow you to buy fractions of a share—for instance, 0.75 of a share—with a smaller amount of money. This means you can invest a fixed dollar amount, rather than being limited by share price, enabling greater diversification for smaller investors. Dividend yields, too, are fractional. A dividend yield of 3% means you receive $3 for every $100 invested, essentially 3/100 of your investment back annually in cash. Knowing that 3/4 of a percentage point increase in dividend yield could mean a tangible difference in your passive income helps you evaluate investments more precisely.
Diversification and Asset Allocation
One of the golden rules of investing is diversification, which involves spreading your investments across different asset classes to mitigate risk. This entire strategy is built upon fractional allocation. A common portfolio might be allocated as 60% stocks, 30% bonds, and 10% cash. In fractional terms, this is 3/5 stocks, 3/10 bonds, and 1/10 cash. These fractions represent your strategic choices about where to put your capital.
Understanding these fractions allows investors to construct portfolios that align with their risk tolerance and financial goals. If you’re a conservative investor, you might allocate a larger fraction to bonds; if you’re aggressive, a larger fraction to stocks. The constant rebalancing of a portfolio involves adjusting these fractions over time to maintain the desired risk profile. For instance, if your stock holdings grow significantly, they might now represent 3/4 of your portfolio, making it riskier than intended. Recognizing this fractional shift prompts you to rebalance by selling some stocks and buying more bonds, bringing your portfolio back to its target fractions.
Loans, Interest, and Debt Management: Fractional Calculations
Debt is an inevitable part of most people’s financial lives, whether it’s a mortgage, car loan, student loan, or credit card balance. The terms of these debts—especially interest rates and payment structures—are deeply rooted in fractional mathematics. A clear understanding here can save you significant money and stress.
Deconstructing Interest Rates and Loan Terms
Interest rates are essentially fractions (or percentages, which are fractions of 100) charged on borrowed money. An annual percentage rate (APR) of 6% is 6/100 of the principal balance each year. When you hear about an interest rate changing by “3/4 of a percentage point,” this specific fractional adjustment can have a substantial impact on your monthly payments and the total cost of your loan over its lifetime.
For example, on a large mortgage, a 0.75% increase in your interest rate can translate to hundreds of dollars more in payments each month and thousands over the loan term. Understanding that this 3/4 increase is 0.0075 added to your interest factor allows you to instantly grasp the magnitude of the change and plan accordingly. Furthermore, a significant fraction of your early mortgage payments often goes towards interest, with only a small fraction reducing the principal. Recognizing this helps borrowers understand the true cost of their loan and motivates them to make extra payments to reduce the interest component.
Understanding Mortgage and Credit Card Payments
Every payment you make on a loan or credit card can be broken down into two fractional components: the principal and the interest. Early in a loan’s life, a larger fraction of your payment typically goes towards interest, while a smaller fraction goes towards reducing the principal. As the loan matures, these fractions reverse.
For credit cards, understanding fractions is vital for managing revolving debt. If you only pay the minimum payment, a very small fraction of that payment actually reduces your principal balance, while a large fraction covers the accumulating interest. This fractional insight explains why minimum payments perpetuate debt. Conversely, making extra payments or understanding how to pay off 3/4 of your credit card balance (the 75% of it) rather than the minimum can dramatically accelerate debt reduction, saving you immense amounts in interest charges over time. This foundational math empowers you to calculate the real cost of debt and strategize for faster liberation from it.
Empowering Your Financial Future with Fractional Fluency
The simple question “what is 3/4 in fraction form?” opens a gateway to profound financial understanding. From the smallest daily purchases to the most significant investment decisions, fractions are constantly at play, shaping the outcomes of our financial lives. Embracing fractional fluency isn’t just about passing a math test; it’s about gaining a competitive edge in managing your money.
The Power of Small Incremental Changes
Understanding fractions highlights the cumulative power of small changes. Saving 3/4 of a dollar each day might seem insignificant ($0.75), but over a year, that’s $273.75—money that could be invested or used to pay down debt. Similarly, finding ways to cut 3/4 of your discretionary spending on a certain category can free up meaningful funds. Compound interest, the engine of wealth building, relies heavily on fractional growth over time. Even a modest fractional return, consistently applied, can lead to substantial wealth accumulation. The ability to visualize and calculate these incremental gains (or losses) makes financial goals feel more tangible and achievable.
Making Informed Financial Decisions
Ultimately, a strong grasp of fractions, decimals, and percentages empowers you to become a more informed and confident financial decision-maker. You can critically evaluate financial products, scrutinize loan offers, optimize your budget, and strategically invest your money. You move beyond simply accepting numbers at face value and begin to understand the proportional relationships and underlying mechanics that drive financial outcomes. This foundational mathematical competence builds a robust framework for long-term financial health.
In conclusion, while “what is 3/4 in fraction form?” is a basic mathematical query, its implications for your financial life are anything but trivial. It represents a fundamental building block of financial literacy that, when mastered, can unlock a world of understanding, control, and opportunity. By embracing and applying fractional thinking to your personal finance, you gain a powerful tool to navigate the complexities of money, make smarter choices, and ultimately secure a more prosperous future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.