
At first glance, the question “what is 3 1/4 as a decimal?” might appear to be a simple arithmetic exercise, a relic from grade school mathematics. The answer, of course, is 3.25. However, to dismiss this conversion as merely trivial would be to overlook a fundamental cornerstone of financial literacy. In the intricate world of personal finance, investing, business operations, and economic analysis, the ability to effortlessly navigate between fractions and decimals is not just a convenience—it’s an absolute necessity.
From calculating interest rates and understanding stock prices to budgeting effectively and managing investments, financial decisions are constantly informed by numerical precision. Fractions, while conceptually useful for representing portions, often lack the universality and direct applicability of decimals in financial contexts. Imagine trying to compare an interest rate of 3 1/4% with another of 3.2% without converting one to the other. Or consider allocating a budget where some percentages are whole numbers and others are mixed fractions. The potential for error, confusion, and ultimately, suboptimal financial outcomes, is significant.

This article delves beyond the simple mathematical conversion, exploring why 3.25, derived from 3 1/4, is more than just a number. It represents a foundational skill that empowers individuals and businesses to make informed, accurate, and strategic financial decisions. By understanding this seemingly basic concept, we unlock a deeper appreciation for the precision required to thrive in the complex landscape of money.
The Foundation: Converting Fractions to Decimals for Financial Accuracy
The immediate answer to “what is 3 1/4 as a decimal?” is 3.25. While straightforward, the process of converting fractions to decimals is a foundational skill that underpins nearly every aspect of financial calculation. Without this basic understanding, individuals and businesses would struggle to interpret financial data, compare investment opportunities, or accurately track expenses and revenues.
The Simple Math Behind 3 1/4: Step-by-Step Conversion
Converting a mixed number like 3 1/4 to a decimal involves two simple steps:
-
Identify the Whole Number: In 3 1/4, the whole number is clearly 3. This part remains unchanged as we convert to a decimal.
-
Convert the Fractional Part: The fraction is 1/4. To convert any fraction to a decimal, you divide the numerator by the denominator. So, 1 divided by 4 equals 0.25.
-
Combine the Parts: Add the whole number to the decimal equivalent of the fraction: 3 + 0.25 = 3.25.
This process is universal. Whether dealing with 1/2 (0.5), 3/4 (0.75), or even more complex fractions, the principle of dividing the numerator by the denominator remains constant. This consistency is precisely what makes decimals the preferred language of finance.
Why This Conversion is Indispensable in Money Matters
The reliance on decimals in finance isn’t arbitrary; it’s a matter of practicality, precision, and universal understanding.
-
Universality and Clarity: Decimals provide a universally understood and unambiguous way to represent monetary values, percentages, and rates. Financial institutions, software, and international markets predominantly operate using decimals. A stock price of $3.25 is immediately clear, whereas $3 and a quarter might require a moment of mental processing, particularly in diverse financial reports.
-
Ease of Comparison and Calculation: Comparing 3.25% to 3.20% is much quicker and less prone to error than comparing 3 1/4% to 3 1/5%. Decimals allow for straightforward arithmetic operations (addition, subtraction, multiplication, division) without the complexities of finding common denominators inherent in fraction arithmetic. When running calculations for interest, returns, or budgets across multiple line items, decimals streamline the process significantly.
-
Preventing Errors: In finance, even minor misinterpretations or calculation errors can have substantial consequences. Using decimals reduces the likelihood of such mistakes by standardizing numerical representation. Imagine miscalculating an interest payment on a large loan simply because a fraction was misinterpreted. The financial repercussions could be severe.
-
Integration with Technology: Modern financial tools, from spreadsheets to sophisticated trading algorithms, are built on decimal logic. An ability to understand and input values as decimals ensures seamless interaction with these essential technologies, making financial management more efficient and accurate.
By mastering the conversion of fractions like 3 1/4 to their decimal equivalent, 3.25, individuals and businesses lay a robust foundation for more advanced financial literacy and responsible money management.
Real-World Financial Applications: Where 3.25 Comes into Play
The seemingly simple conversion of 3 1/4 to 3.25 finds its practical application in countless financial scenarios, illustrating its direct impact on everyday money management, investment decisions, and business operations. Understanding these contexts highlights why such numerical fluency is not just academic but profoundly practical.
Personal Budgeting and Expense Tracking
Effective personal finance begins with meticulous budgeting and expense tracking. Here, decimals are paramount.
-
Splitting Bills and Shared Expenses: Imagine dining with friends, and the total comes to $13.25 per person. While someone might jokingly say, “That’s 13 and a quarter dollars,” the actual payment and tracking will use $13.25. Similarly, if you lend a friend “three and a quarter dollars,” you’d expect to be paid back $3.25, which is easier to track in any budgeting app or personal ledger.
-
Allocating Income and Savings: Many financial strategies involve allocating portions of income. If you decide to put 1/4 of your bonus into savings, plus a base amount of $3, your total contribution would be $3 plus 25% of the bonus, translating directly into decimal calculations. Budget categories often need to be precise; 3.25% of your income might go towards a specific discretionary fund, and without decimal understanding, these allocations become murky.
-
Understanding Discounts and Offers: Retailers frequently offer “an extra 1/4 off” or a discount that, when applied, results in a final price with a fractional component. Converting these to decimals ensures you calculate the final price accurately and understand the true value of the discount.
Investing and Asset Management
The investment world, with its complex calculations of returns, yields, and share prices, relies almost exclusively on decimal precision.
-
Stock Prices and Trading: Historically, stock prices were quoted in fractions (e.g., a stock might be $3 1/4). While modern exchanges typically use decimals (e.g., $3.25), understanding the fractional origin can still be relevant for historical analysis or specific niche markets. Moreover, when you buy 100 shares at $3.25 per share, the total cost ($325) is a direct result of decimal multiplication.
-
Yields and Returns: Whether it’s the dividend yield of a stock, the yield-to-maturity of a bond, or the return on an investment portfolio, these are almost universally expressed as percentages, which are essentially decimals. A “yield of 3 1/4%” immediately translates to 0.0325 when performing calculations to determine your actual earnings.
-
Portfolio Allocation: Investors often allocate their portfolios by percentage (e.g., 25% in bonds, 50% in equities). If you have a specific asset class that constitutes “3 and a quarter portions” out of a theoretical whole, converting this to 3.25 units simplifies the entire allocation model and ensures your portfolio remains balanced according to your strategy.
Interest Rates and Loan Calculations
Interest is the lifeblood of banking and lending, and its calculation is inherently decimal-driven.
-
Annual Percentage Rates (APRs): Every loan, credit card, or savings account advertises an APR or interest rate. If you encounter an offer of “3 1/4% interest,” you immediately convert this to 0.0325 to calculate your interest payments on a loan or your earnings on savings. Small differences in these decimal points can lead to significant financial disparities over time.
-
Simple and Compound Interest: The formulas for calculating both simple and compound interest rely on interest rates expressed as decimals. For instance, the formula for simple interest (Principal × Rate × Time) absolutely requires the rate to be in decimal form (e.g., 0.0325, not 3.25 or 3 1/4).
-
Mortgage Payments: Mortgage rates, often the largest financial commitment for many individuals, are quoted as percentages and then used in complex amortization schedules that are entirely based on decimal calculations to determine monthly payments, interest accrual, and principal reduction.
Business Finance and Accounting
For businesses, accurate financial conversion is critical for everything from pricing to profitability.

-
Calculating Profit Margins: If a product’s cost makes up a certain fraction of its selling price, converting that fraction to a decimal allows for precise profit margin calculations. For instance, if raw materials cost $3.25 for an item, this precise decimal is used in calculating gross profit margins.
-
Inventory Management and Pricing: Businesses often deal with fractional units or partial completion of goods. Converting these to decimals provides accuracy in valuing inventory, calculating unit costs, and setting competitive prices.
-
Shareholder Equity and Dividends: When distributing dividends or calculating per-share earnings, fractional ownership or earnings often need to be converted to decimals to ensure fair and accurate distribution among shareholders. For example, if a company declares a dividend of “three and a quarter cents per share,” this must be treated as $0.0325 per share.
In each of these diverse financial contexts, the seemingly simple conversion of 3 1/4 to 3.25 emerges as a powerful tool for clarity, precision, and informed decision-making.
The Perils of Ignoring Decimal Precision in Finance
While converting 3 1/4 to 3.25 might seem elementary, overlooking or mismanaging such basic decimal precision in financial contexts can lead to significant and often costly consequences. The subtle differences between fractions and decimals, or slight errors in conversion, can propagate into major financial discrepancies, impacting personal wealth, business profitability, and financial stability.
Misinterpretation and Costly Errors
One of the primary dangers of neglecting decimal precision is the increased risk of misinterpretation and subsequent calculation errors.
-
Mistakes in Interest Calculations: Imagine a loan with an interest rate of “three and a quarter percent.” If someone mistakenly interprets this as 3.25 (as a whole number) instead of 0.0325 (the decimal equivalent for calculation), the interest payment would be dramatically overstated or understated. On a large mortgage or business loan, such an error could lead to thousands of dollars in overpayments or underpayments over the loan’s lifetime, creating either financial strain or legal complications. Even small rounding errors, if accumulated over many transactions or long periods, can become substantial.
-
Budgeting Inaccuracies: Personal budgets are designed to provide a clear picture of income and expenses. If fractional amounts are consistently rounded or inaccurately converted to decimals, the budget quickly loses its accuracy. A budget showing an expense of $100 “and a quarter” might be mentally rounded to $100 or $100.50, when it should be $100.25. Over time, these small discrepancies can accumulate, leading to a distorted view of cash flow and potentially derailing financial goals like saving for a down payment or retirement.
-
Investment Miscalculations: In the fast-paced world of investing, every cent matters. Miscalculating a stock’s value, a bond’s yield, or an investment fund’s expense ratio due to decimal errors can lead to suboptimal decisions. For instance, if an investor miscalculates a 3 1/4% return as 3.25 times the investment instead of 0.0325 times, the projected gains would be wildly inaccurate, potentially leading to over-risking or missed opportunities. These errors can directly impact portfolio performance and long-term wealth accumulation.
Lack of Financial Clarity and Comparative Analysis
Beyond outright errors, a lack of decimal precision can severely impede one’s ability to gain clarity on their financial situation and effectively compare different financial products or opportunities.
-
Difficulty Comparing Financial Products: Consider trying to choose between two savings accounts: one offering 3 1/4% interest and another offering 3.2% interest. Without converting 3 1/4% to 3.25%, it’s not immediately obvious which rate is higher. A quick mental comparison might even lead to the wrong conclusion if one isn’t accustomed to converting fractions instantly. This inability to quickly and accurately compare can lead to choosing less advantageous financial products, costing money over time.
-
Inability to Quickly Grasp Financial Scale: Decimals provide a standardized, linear scale that makes it easy to visualize and compare magnitudes. A value like $3.25 is immediately understood in relation to $3.00 or $3.50. If financial figures are consistently presented in mixed fractional forms, grasping the true scale of transactions, investments, or debts becomes more challenging and time-consuming, hindering rapid decision-making in critical financial moments.
-
Hindrance to Strategic Planning: Whether personal or business-related, financial strategy relies on precise numerical inputs. If the underlying data is muddled by inconsistent fractional and decimal representations, strategic models and forecasts will be inherently flawed. This can lead to ineffective business plans, inaccurate cash flow projections, and ultimately, a compromised ability to achieve long-term financial objectives.
Ultimately, the act of converting 3 1/4 to 3.25, while basic, is a microcosm of the precision demanded by the financial world. Ignoring this fundamental principle is not just an academic oversight; it’s a practical vulnerability that can undermine financial well-being and strategic success.
Tools and Strategies for Mastering Financial Conversions
In an increasingly data-driven financial landscape, mastering conversions like 3 1/4 to 3.25 is not just about understanding the math, but also about leveraging modern tools and cultivating an ongoing commitment to financial literacy. While the principle is simple, applying it consistently across various complex financial scenarios requires both the right resources and a proactive mindset.
Leveraging Digital Calculators and Spreadsheet Software
Modern technology has made numerical conversions incredibly accessible, greatly reducing the potential for manual error.
-
Dedicated Financial Calculators: Many online and handheld financial calculators are specifically designed to handle complex financial formulas, but they also effortlessly manage basic conversions. These tools ensure accuracy, especially when dealing with multiple conversions in a row or when preparing data for more intricate analyses.
-
Spreadsheet Software (Excel, Google Sheets): Programs like Microsoft Excel and Google Sheets are indispensable financial tools. They allow users to input fractional values and automatically convert them to decimals using simple formulas. For instance, you can enter ‘3 1/4’ (formatted as a fraction) and convert it to its decimal equivalent ‘3.25’ with a function, or simply by entering ‘3 + 1/4’ directly into a cell. This is particularly useful for tracking budgets, investment portfolios, or business finances where numerous figures require consistent decimal representation. The ability to automate these conversions ensures consistency across large datasets and minimizes the human error factor.
-
Online Converters and Apps: Numerous free online fraction-to-decimal converters and mobile apps can instantly perform these operations. While perhaps overkill for a simple conversion like 3 1/4, they are valuable resources for less common or more complex fractions, providing quick verification and saving time.
Cultivating Mental Math Skills
While technology provides invaluable assistance, developing strong mental math skills for common conversions offers immediate benefits in everyday financial interactions.
-
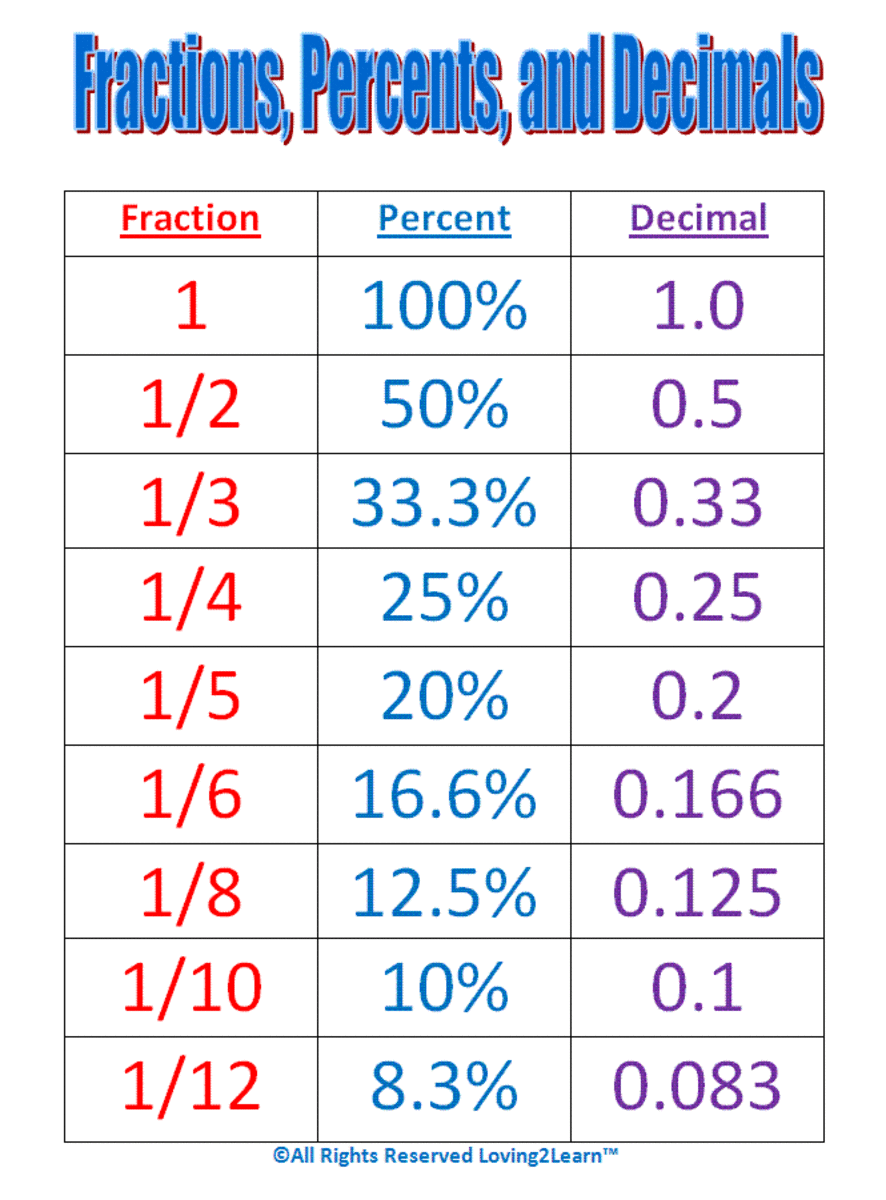
Memorizing Common Conversions: For frequently encountered fractions like 1/2 (0.5), 1/4 (0.25), 3/4 (0.75), 1/5 (0.2), and 1/3 (0.333…), committing their decimal equivalents to memory significantly speeds up financial understanding. When someone mentions “3 and a quarter percent,” instantly knowing that means 3.25% allows for quicker assessment without reaching for a tool.
-
Practicing Quick Estimation: Even for less common fractions, practicing mental estimation can be beneficial. Understanding that 1/8 is half of 1/4 (0.125) helps build numerical intuition. This skill is crucial for quickly evaluating deals, comparing rates, or making on-the-spot financial judgments when a calculator isn’t immediately available.
-
Building Financial Confidence: Regular practice with mental conversions builds confidence in numerical reasoning, which translates directly into greater comfort and assertiveness in managing personal and business finances. It empowers individuals to engage more actively and intelligently with financial statements, market reports, and investment discussions.
Continuous Learning and Financial Literacy Programs
Mastering financial conversions is not a one-time achievement but an ongoing commitment to financial literacy.
-
Formal and Informal Education: Engaging with financial literacy courses, workshops, or even reputable online resources can deepen one’s understanding of how mathematical concepts apply to real-world financial scenarios. Many institutions offer free resources that cover foundational math relevant to finance.
-
Staying Informed: The financial world is dynamic. While basic conversions remain constant, understanding how they are applied in new financial products or market trends requires continuous learning. Reading financial news, books, and articles helps contextualize these numerical skills within broader economic realities.
-
Applying Knowledge Consistently: The most effective strategy for mastering financial conversions is consistent application. Whether it’s balancing a checkbook, reviewing an investment statement, or evaluating a business proposal, consciously applying decimal precision reinforces the skill and highlights its practical value.
By embracing these tools and strategies, individuals and businesses can move beyond simply knowing “what is 3 1/4 as a decimal” to truly understanding its implications and leveraging that knowledge for smarter, more secure financial futures.
Conclusion: Empowering Your Financial Journey with Decimal Fluency
The seemingly straightforward question, “what is 3 1/4 as a decimal?”, yielding the answer 3.25, serves as a powerful metaphor for the meticulous precision required in navigating the financial world. It underscores that financial literacy is not merely about understanding complex algorithms or market trends, but fundamentally about mastering the basic building blocks of numerical representation.
In the realm of money, whether personal or corporate, fractions often introduce ambiguity and complexity, whereas decimals provide the clarity, universality, and computational ease that are absolutely essential for accurate decision-making. We’ve explored how this simple conversion permeates every facet of financial life: from the precise allocation of a personal budget and the interpretation of interest rates on loans, to the sophisticated calculations behind investment yields and the accurate accounting within a business. Ignoring this foundational principle can lead to costly errors, misjudgments, and a significant lack of clarity that impedes financial progress.
By actively leveraging digital tools, cultivating mental math skills, and committing to continuous financial education, individuals and businesses can transform a basic mathematical conversion into a powerful financial advantage. Understanding that 3 1/4 unequivocally translates to 3.25 is more than just academic knowledge; it is a critical step towards empowering yourself to analyze, compare, and manage your financial resources with confidence and competence. In a world increasingly driven by data and numerical analysis, decimal fluency is not just a desirable trait—it is an indispensable skill for achieving lasting financial success and security.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.