
In the world of finance, precision is not merely a preference; it is a requirement. Whether you are calculating the interest on a high-yield savings account, determining the allocation of fractional shares in a diversified portfolio, or analyzing the debt-to-equity ratio of a potential investment, the ability to manipulate fractions and ratios is fundamental. At first glance, the question “What is 1 3/4 divided by 1/2?” appears to be a relic of middle-school arithmetic. However, in a financial context, this equation represents the core logic of leverage, distribution, and scalability.
To solve the mathematical problem: 1 3/4 is equivalent to the improper fraction 7/4. Dividing by 1/2 is mathematically identical to multiplying by its reciprocal, 2/1. Therefore, (7/4) * (2/1) equals 14/4, which simplifies to 3.5. In financial terms, this represents a 350% increase or a 3.5x multiplier. Understanding how these figures interact is the first step toward mastering the quantitative side of personal and business finance.

The Mathematics of Leverage and Multipliers in Investing
The result of our calculation, 3.5, is more than just a number; in the context of money, it often represents a multiplier. Multipliers are essential in understanding leverage. When an investor uses margin to increase their buying power, they are essentially dividing their available capital by a fraction to see how much more market exposure they can obtain.
Understanding Margin and Buying Power
In a standard brokerage account, a 2:1 margin ratio is common. If you have $1,750 (representing our 1 3/4 in a larger denomination) and you divide your capital requirement by 1/2, you effectively double your purchasing power to $3,500. This is the practical application of the division of fractions in real-time wealth management. The ability to see your capital not as a static whole, but as a divisible asset that can be leveraged, is what separates passive savers from active investors.
Leverage acts as a double-edged sword. While the “3.5x” result of our initial equation suggests a significant expansion of capital, it also implies a 3.5x expansion of risk. If the underlying asset moves against the investor, the losses are magnified by that same factor. Financial literacy requires an intrinsic understanding that whenever you divide your risk or multiply your exposure, the structural integrity of your portfolio must be able to withstand the resulting pressure.
The Role of Ratios in Fundamental Analysis
Financial analysts use ratios to determine the health of a corporation. The debt-to-equity (D/E) ratio, for instance, is a direct application of fractional division. If a company has 1.75 million dollars in liabilities and 0.5 million dollars in shareholder equity, its D/E ratio is 3.5. In most industries, a ratio of 3.5 would be considered aggressive, signaling that the company is heavily reliant on debt to fund its growth. By understanding the math behind the fraction, an investor can quickly conclude that for every dollar of equity, the company has three and a half dollars of debt. This “fractional thinking” allows for rapid assessment of financial statements without getting bogged down in raw, uncontextualized data.
Fractional Shares: Modernizing Asset Allocation
The rise of fintech platforms has democratized investing through “fractional shares.” Historically, if an investor wanted to buy a single share of a high-priced tech stock trading at $3,500, they needed the full amount. Today, the math of 1 3/4 divided by 1/2 is at the heart of how these platforms function, allowing investors to own 1.75 shares or even 0.5 shares of an asset.
Lowering the Barrier to Entry
Fractional investing allows an individual to allocate a specific dollar amount to an asset rather than a specific number of shares. Suppose you have a set budget and want to distribute it across several high-value equities. You are essentially performing the inverse of our primary calculation. You are taking a “whole” amount of capital and dividing it into fractional components. This allows for hyper-diversification, even with a small portfolio.
The precision of these calculations ensures that dividends are distributed fairly. If you own 1 3/4 shares of a company that pays a dividend, the platform must divide that payout precisely. If the dividend is $1.00 per share, you receive $1.75. Understanding the “point-five” or “point-seven-five” of a share is vital for accurate retirement planning and dividend reinvestment strategy (DRIP) calculations.
Micro-Investing and the Compound Effect
Many “round-up” apps utilize fractional math to build wealth. Every time you spend $1.50, the app rounds up to $2.00 and invests the $0.50 (the 1/2 in our equation). While $0.50 seems negligible, the division of your spending into “investable units” creates a consistent flow of capital into the market. Over time, these fractions aggregate. If you consistently divide your surplus into small investment tranches, the 3.5x growth over a decade or two becomes a mathematical certainty through the power of compounding interest, rather than a mere theoretical exercise.

Debt Management and the Division of Interest Rates
The most common place where people encounter “1 3/4” or “1/2” is in the world of interest rates and APRs. A mortgage rate might be 7% (which is 4 times 1 3/4), or a savings account might offer a 3.5% yield (the exact result of our division). Understanding how these fractions are divided over time is the key to minimizing debt and maximizing returns.
The Impact of Compounding Frequency
When a bank quotes an annual interest rate, the “division” happens in the compounding period. If you have a 3.5% annual percentage yield (APY), the bank doesn’t give you the full 3.5 at once. They divide that rate by the number of compounding periods in a year—often 12 (monthly) or 365 (daily).
If we look at our equation 1 3/4 (1.75%) divided by 1/2 (two periods a year), we see how interest accrues semi-annually. In debt management, understanding this division is crucial for those looking to pay off loans early. By making bi-weekly payments (effectively dividing your monthly payment by 1/2 but increasing the frequency), you end up making an extra full payment each year. This mathematical shift significantly reduces the total interest paid over the life of a 15- or 30-year loan.
Amortization and Fractional Progress
In the early years of a mortgage or car loan, the division of your payment is heavily weighted toward interest rather than principal. If your interest rate is expressed as a mixed number, like 5 3/4%, and you are trying to calculate the impact of a 1/2 point rate drop, you are engaging in the exact type of fractional analysis we started with. A reduction from 5 3/4% to 5 1/4% may seem small, but when that fraction is applied to a $400,000 balance, the division of interest over 360 months results in tens of thousands of dollars in savings.
Strategic Budgeting: The Ratio-Based Approach
Financial success is often predicated on the ratios we set for our income. The “50/30/20” rule is a popular budgeting framework that essentially divides one’s income into fractions: 1/2 for needs, 3/10 for wants, and 1/5 for savings/debt.
Applying the 3.5 Multiplier to Savings Goals
If your goal is to save enough for an emergency fund that covers 3.5 months of expenses—the result of our 1 3/4 divided by 1/2 calculation—you must understand the relationship between your monthly “burn rate” and your liquid assets. If you can live on 1/2 of your income, you can build that 3.5-month cushion much faster than someone living on 1 3/4 of their income (spending more than they earn).
Budgeting is, at its core, a game of division. You take the “1” (your total paycheck) and divide it into various buckets. The efficiency with which you divide those fractions determines your ultimate financial freedom. When you can look at a number like 3.5 and see it as a goal for your “liquidity ratio,” you are moving from a consumer mindset to a CFO mindset.
Business Finance and Unit Economics
For entrepreneurs, dividing the “whole” into “parts” is the only way to determine profitability. If a product costs $1.75 to manufacture (1 3/4) and you sell it in half-units or half-sized portions, your pricing strategy depends entirely on the math of division. Understanding your unit economics—how much profit is generated per fraction of a sale—allows a business to scale. If the division results in a healthy margin, the business can afford to spend more on customer acquisition, effectively using the “3.5” multiplier to grow the company’s footprint in the market.
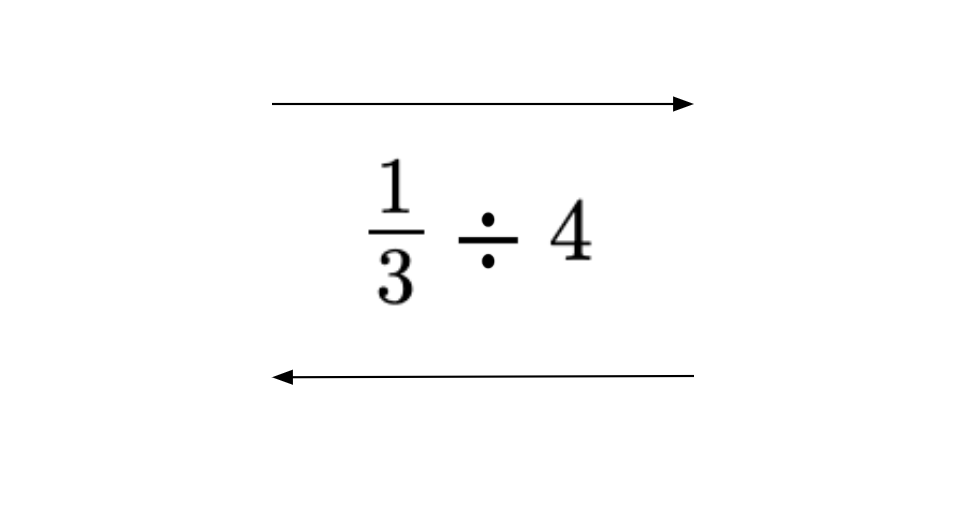
The Value of Quantitative Literacy in a Digital Economy
As we move toward an increasingly automated and algorithmic economy, the importance of basic quantitative literacy cannot be overstated. While AI tools can perform the calculation of 1 3/4 divided by 1/2 in milliseconds, the human ability to interpret that “3.5” in the context of a bank statement, a stock ticker, or a business contract remains an invaluable skill.
Money is, essentially, a language of numbers. Those who speak it fluently—who can see the fractions within the totals and the ratios within the trends—are the ones who find the most success. Whether you are dividing your time, your labor, or your capital, the principles of arithmetic remain the foundation of all financial strategy. By mastering the simple division of 1 3/4 by 1/2, you are not just solving a math problem; you are practicing the very logic required to navigate the complexities of the modern financial landscape.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.