
The question “what fraction is half of 1/4?” might seem like a simple arithmetic problem, a relic from grade school. The answer, of course, is 1/8. Yet, embedded within this seemingly trivial calculation lies a profound truth about financial literacy: a deep understanding of basic mathematical concepts, particularly fractions, is not just a cornerstone, but a powerful lever for sound money management, astute investing, and robust financial planning. In an era saturated with complex financial products and jargon, the ability to grasp and apply fundamental arithmetic is an indispensable skill that empowers individuals to navigate their financial landscape with confidence and precision.
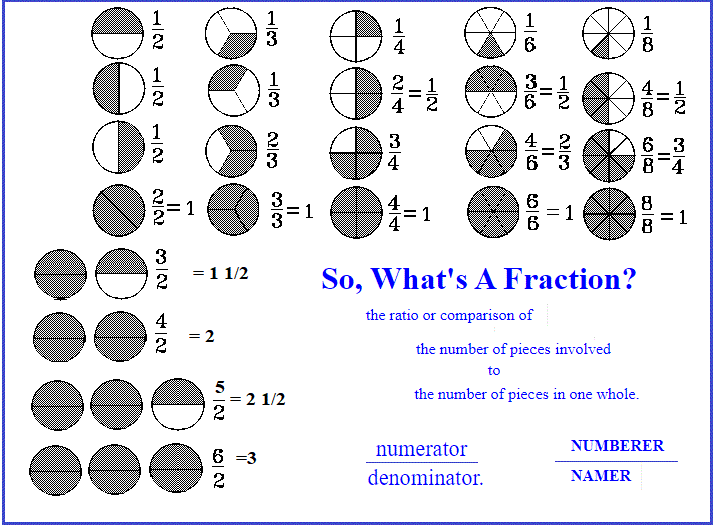
This article delves into why mastering simple fractional calculations, like determining “half of 1/4,” is not merely an academic exercise but a critical component of personal and business finance. From budgeting and investment allocation to understanding debt and optimizing profits, fractions provide a foundational language for translating complex financial realities into actionable insights.
The Foundational Role of Fractions in Personal Finance
At its core, personal finance is about managing limited resources – your income – and allocating them effectively across various needs, wants, and future goals. Fractions provide the most intuitive way to conceptualize and execute this division, transforming abstract figures into tangible portions.
Budgeting and Expense Allocation: Dividing Your Financial Pie
Budgeting is arguably the most fundamental aspect of personal finance, and it is inherently fractional. When you set a budget, you are essentially dividing your total income into various categories: savings, housing, food, transportation, debt repayment, and discretionary spending.
For example, a common budgeting rule is the 50/30/20 rule, where 50% of your income goes to needs, 30% to wants, and 20% to savings and debt repayment. While often expressed as percentages, these are fundamentally fractions (1/2, 3/10, 1/5). Understanding that 50% is the same as 1/2 allows for quicker mental calculations and a more intuitive grasp of how your money is being distributed.
Consider a scenario where you’ve decided to dedicate 1/4 of your discretionary income to a specific hobby, and then you further decide that half of that 1/4 will be saved for a big purchase related to that hobby. Knowing that half of 1/4 is 1/8 immediately tells you what proportion of your total discretionary fund is being set aside. This precision prevents overspending and ensures your funds align with your priorities. Without this basic understanding, you might simply approximate, leading to budget shortfalls or inefficient allocation.
Understanding Investments and Returns: Beyond Simple Percentages
The world of investing, while often appearing complex, relies heavily on fractional concepts. Whether you’re dealing with stock shares, mutual funds, or real estate, you’re always dealing with portions of ownership, returns, or assets.
When you buy shares in a company, you own a fraction of that company. If a company announces a stock split, say a 2-for-1 split, your existing shares are effectively doubled, meaning your ownership fraction changes in terms of quantity but not necessarily in terms of your overall proportional stake (unless new shares are issued). Understanding the proportional impact of such events is crucial for investors.
Furthermore, investment returns are frequently discussed as fractions or percentages. A return of 1/4 (or 25%) on your initial investment tells you precisely how much your money has grown relative to the principal. Interest rates, whether on savings accounts or loans, are also expressed fractionally (e.g., 0.5% interest is 1/200th of the principal per period). When a financial news report mentions a “quarter point” interest rate hike, it means a 0.25% increase, or 1/4 of a percentage point. For investors, understanding these fractional nuances allows for more accurate projections of future earnings or costs.
Deconstructing Financial Concepts with Simple Math
Many financial decisions hinge on correctly interpreting and calculating proportions. Simple fractions are the bedrock for these interpretations, enabling individuals to make informed choices rather than relying on guesswork.
Calculating Discounts, Sales, and Proportions
Everyday commerce is rife with fractional calculations. Sales often advertise “half off” or “an additional 1/4 off the marked price.” Misinterpreting these can lead to paying more than necessary or missing out on actual savings. If an item is already 1/4 off its original price, and then an additional “half off” is applied to that discounted price, understanding “half of 1/4” (which is 1/8) helps you quickly calculate the total discount from the original price (1/4 + 1/8 = 3/8 off). This clarity empowers consumers to discern genuine deals from marketing ploys.
Similarly, when dealing with bulk purchases or unit pricing, understanding fractions helps you determine the best value. If one package offers “1/4 more for free,” and another offers “half price for a second item,” a quick fractional comparison can reveal which deal is genuinely more beneficial based on your needs.
Debt Management and Interest: The Cost of Borrowing

Debt is a ubiquitous aspect of modern finance, and managing it effectively requires a clear understanding of interest calculations, which are inherently fractional. An annual interest rate of 12% means you pay 12/100 (or 3/25) of the principal amount in interest over a year. If interest is compounded monthly, you’re paying 1/12th of that annual rate each month.
Understanding how minimum payments function is another critical application. If your minimum payment is a small fraction of your total balance (e.g., 1/50th), knowing how long it will take to repay the debt and the total interest accrued becomes clearer. Recognizing that making only the minimum payment on a credit card balance often means a very large fraction of your payment goes towards interest rather than principal highlights the importance of paying more than the minimum to reduce the total cost of borrowing.
Building Financial Acumen: From Basic Fractions to Advanced Strategies
The foundation laid by understanding simple fractions extends into more sophisticated financial strategies, providing the quantitative backbone for complex decision-making.
Empowering Investment Decisions: Analyzing Portfolios and Diversification
Diversification is a core principle of risk management in investing, often conceptualized using fractions. An investor might decide to allocate their portfolio such that 1/4 is in large-cap stocks, 1/4 in small-cap stocks, 1/4 in bonds, and 1/4 in real estate. This deliberate fractional allocation helps spread risk and optimize returns.
Rebalancing a portfolio also involves fractional adjustments. If your stock portion grew significantly, it might now represent more than your initial 1/4, perhaps becoming 1/3 of your portfolio. Rebalancing would involve selling a fraction of your stocks to bring them back to the desired 1/4 allocation and investing that capital into underperforming asset classes to maintain your desired fractional distribution. This disciplined approach prevents overexposure to any single asset class and ensures your portfolio remains aligned with your risk tolerance and financial goals.
Entrepreneurship and Profit Sharing: Dividing the Rewards
For small business owners, entrepreneurs, or those engaged in side hustles with partners, fractional understanding is essential for profit sharing, equity distribution, and cost allocation. If a business partner is entitled to “half of 1/4 of the annual profits” after certain expenses, the ability to quickly calculate this as 1/8 of the total profits streamlines financial agreements and ensures fair distribution.
Similarly, when determining ownership stakes in a startup, founders often divide equity using fractions (e.g., Founder A gets 1/2, Founder B gets 1/4, and 1/4 is reserved for future employees). Any dilution events (e.g., bringing in new investors) will further reduce these fractions, and understanding the proportional impact of such changes is vital for maintaining control and valuing one’s stake.
Practical Applications: Financial Tools and Everyday Scenarios
While modern financial tools simplify many calculations, the underlying logic is still rooted in basic arithmetic. Understanding fractions provides the conceptual framework that makes these tools truly effective.
Digital Tools and Fraction-Based Calculations
Budgeting apps, investment platforms, and financial calculators automate many fractional calculations. However, without a foundational understanding of what those fractions represent, users might blindly accept outputs without truly comprehending their implications. For instance, an investment app might show your portfolio allocation as percentages, but knowing that 25% is 1/4 helps you quickly visualize the distribution and mentally cross-check the app’s figures.
Financial modeling in spreadsheets also heavily relies on fractional inputs and formulas. Whether calculating compound interest, amortization schedules, or projected returns, understanding the fractional components of these formulas allows users to build robust models and interpret results accurately, rather than just plugging in numbers.

Real-World Examples: Making Informed Financial Choices
Consider a scenario: You want to save for a down payment on a house. You’ve calculated that you need to save 1/4 of your take-home pay each month. To accelerate this, you decide to dedicate half of your annual bonus to this down payment goal as well. If your bonus is typically 1/20th of your annual salary, then “half of 1/20th” of your salary (which is 1/40th) will go towards your down payment. This simple calculation gives you a clear picture of how different income streams contribute fractionally to your overall financial objective.
Another example is understanding the impact of fees. If an investment fund charges 1/4 of a percentage point in fees annually, it might seem small. But over decades, this small fraction can accumulate to a significant sum, eating into your returns. Being able to conceptualize this fraction (1/400th of your investment value annually) allows for a more informed assessment of the true cost of investing.
In conclusion, the answer to “what fraction is half of 1/4?” is 1/8, a simple mathematical truth. However, its implications for personal and business finance are far-reaching. Mastering this and other basic fractional concepts is not merely about numerical proficiency; it’s about gaining financial independence, making informed decisions, and building a robust framework for managing wealth. In a world where financial complexity often obscures clarity, a firm grasp of foundational arithmetic provides the invaluable lens through which to simplify, understand, and ultimately master your financial destiny.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.