
In the realm of mathematics, the fraction 1/3 represents a repeating decimal, an infinite sequence of threes that suggests a sense of ongoing momentum. In the world of finance, however, 1/3 is much more than a numerical value; it is a structural cornerstone. Whether you are managing a household budget, balancing a multi-million dollar investment portfolio, or scaling a startup, the “Rule of Thirds” acts as a stabilizing force.
Understanding what fraction 1/3 represents in your financial life is the difference between erratic growth and sustainable wealth. By breaking down complex financial systems into three distinct parts, investors and savers can simplify their decision-making processes, mitigate risk, and ensure that no single area of their economic life is neglected.
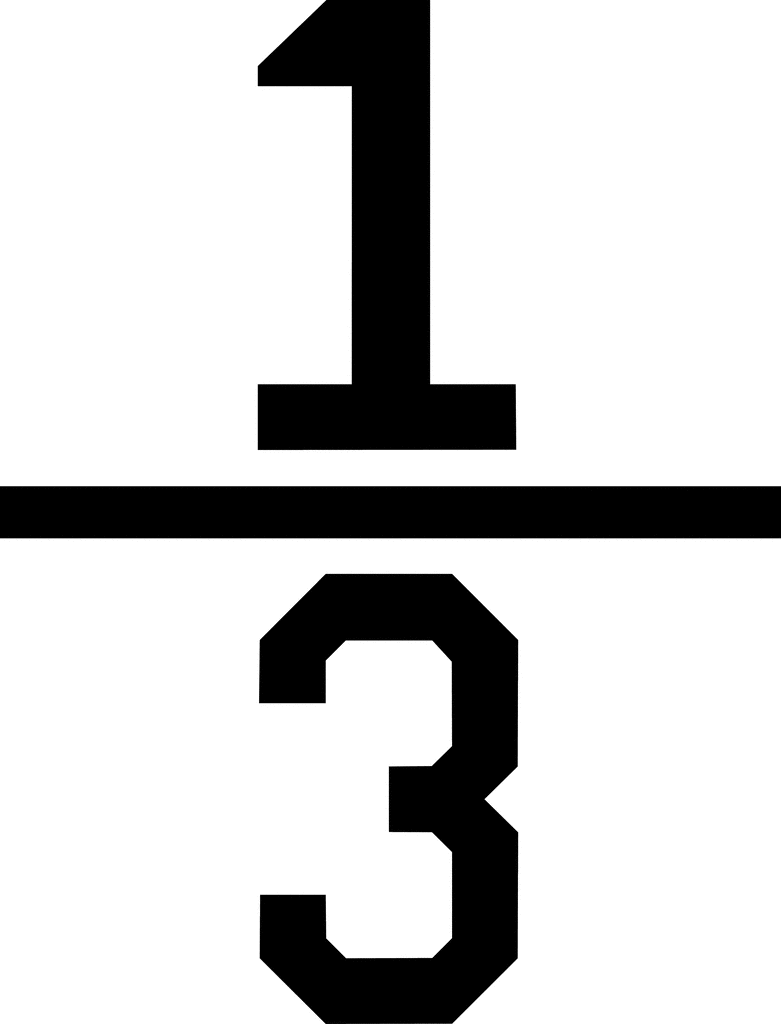
The Rule of Thirds in Personal Finance: A Framework for Spending, Saving, and Investing
The most immediate application of the 1/3 fraction is found in income allocation. While many financial advisors promote the 50/30/20 rule (necessities, wants, and savings), the 33/33/33 split offers a more aggressive and balanced approach for those seeking rapid financial independence.
Allocating Income: The 33/33/33 Split
When we view our net income through the lens of one-third, we create a disciplined environment for wealth accumulation. In this model, one-third of your income is dedicated to essential living expenses—housing, utilities, and groceries. The second third is allocated to lifestyle and discretionary spending, ensuring that the psychological need for enjoyment is met without compromising the future. The final third is strictly reserved for debt repayment and long-term investments.
By keeping essential costs to just one-third of your take-home pay, you create a massive buffer against economic downturns. If a job loss occurs or inflation spikes, the 1/3 spent on lifestyle and the 1/3 spent on investing can be redirected to cover essentials. This fractional approach provides a level of security that more lopsided budgets simply cannot match.
Breaking Down the Essentials, the Future, and the Present
The power of 1/3 lies in its symmetry. Unlike other budgeting methods that treat savings as a leftover “fraction” of what remains after spending, the 1/3 rule elevates savings to the same level of importance as your housing and your lifestyle.
For high-income earners, this fraction is particularly potent. As income increases, the “1/3 for lifestyle” category often grows faster than necessary—a phenomenon known as lifestyle creep. By maintaining the 1/3 discipline, investors ensure that every dollar of a raise is split proportionally, automatically increasing their investment rate as their career progresses.
Asset Allocation and the Power of Fractional Diversification
In the context of investing, the fraction 1/3 is the basis for one of the most resilient portfolio strategies ever devised: the equal-weight allocation. Diversification is often called the “only free lunch” in finance, and dividing your capital into thirds is a primary way to consume it.
The 1/3 Equity, 1/3 Fixed Income, 1/3 Alternative Model
Modern portfolio theory often oscillates between aggressive stocks and conservative bonds. However, many sophisticated investors utilize a three-part split to handle market volatility.
-
Equities (1/3): This portion captures market growth through stocks, ETFs, and index funds. It is the engine of the portfolio.
-
Fixed Income and Cash (1/3): This provides a safety net. It includes government bonds, high-yield savings, and certificates of deposit. This fraction protects the principal during market crashes.
-
Hard Assets and Alternatives (1/3): This includes real estate, gold, commodities, or even private equity. Because these assets often have a low correlation with the stock market, they provide a hedge against inflation and systemic risk.
When one-third of your wealth is in a different asset class, the failure of one sector cannot destroy your entire net worth. If the stock market drops by 30%, it only affects one-third of your total holdings, significantly dampening the emotional and financial impact.
Risk Management Through Equal Weighting
The simplicity of 1/3 is its greatest strength. Rebalancing a portfolio becomes an intuitive task. If your stocks perform exceptionally well and now represent 45% of your portfolio, you simply sell the excess and redistribute it to the other two categories until each returns to 1/3. This mechanical process forces you to “buy low and sell high,” a fundamental principle of investing that many struggle to execute emotionally.
1/3 as a Metric for Business Growth and Debt Management
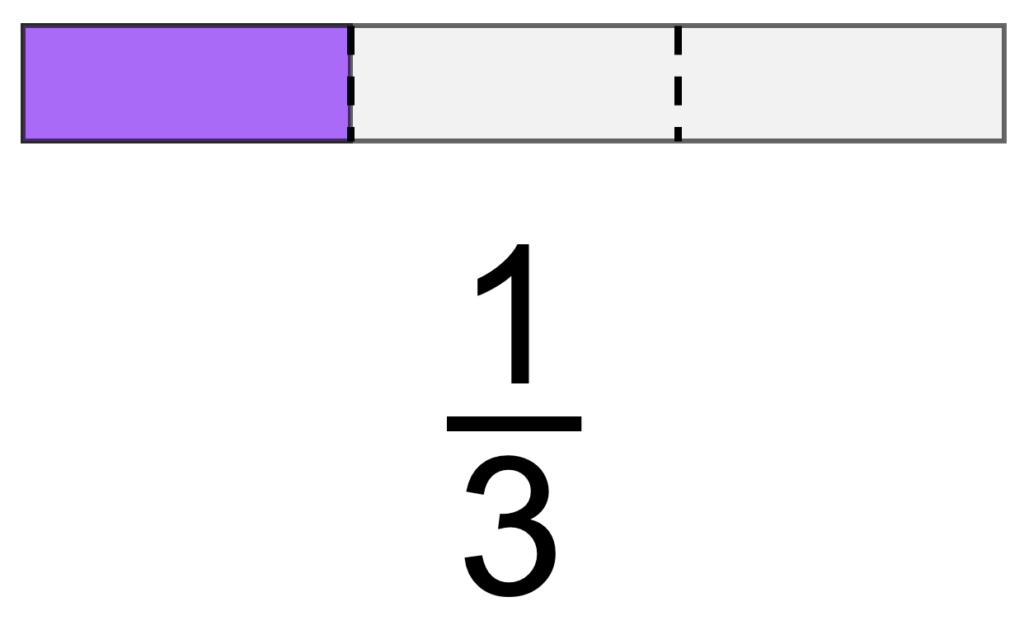
For entrepreneurs and business owners, the fraction 1/3 is a vital diagnostic tool. It serves as a benchmark for health across balance sheets and income statements.
The Debt-to-Income Ratio: Keeping Liabilities Below One-Third
In the mortgage and lending industry, the “front-end ratio” typically dictates that your housing costs should not exceed 28% to 33% of your gross monthly income. This 1/3 threshold is not arbitrary; it is the point at which debt begins to crowd out the ability to handle emergencies.
Staying under the 1/3 mark for total debt obligations—including car loans, student loans, and credit cards—is the “gold standard” for financial health. When debt consumes more than one-third of your cash flow, you lose the “fractional flexibility” required to pivot in a changing economy.
Reinvestment Fractions for Small Business Owners
In business operations, the 1/3 rule is often applied to margins. A common target for a healthy service-based business is to spend 1/3 of revenue on labor, 1/3 on overhead and materials, and retain 1/3 as net profit.
This net profit fraction is then further divided. A disciplined business owner might take 1/3 of that profit as a distribution, keep 1/3 in the business as a cash reserve, and use the final 1/3 for aggressive R&D or marketing. This “fraction within a fraction” creates a self-sustaining cycle of growth that doesn’t rely on outside venture capital.
The Psychology of One-Third: Why Fractional Thinking Leads to Better Decisions
Money is as much about psychology as it is about math. The fraction 1/3 appeals to the human brain’s affinity for “The Rule of Three.” We find three-part structures easier to remember, process, and execute.
Avoiding the All-or-Nothing Trap
Many investors fall into the trap of binary thinking: “Should I be all-in on Bitcoin, or all-in on gold?” “Should I pay off my mortgage, or invest in the S&P 500?”
Fractional thinking breaks this stalemate. Instead of choosing between two extremes, you can allocate 1/3 to Option A, 1/3 to Option B, and 1/3 to a liquid cash reserve. This “middle path” reduces the “regret risk” associated with making the wrong choice. If you are 1/3 right, you still profit; if you are 1/3 wrong, you haven’t lost everything.
Long-term Wealth vs. Short-term Gratification
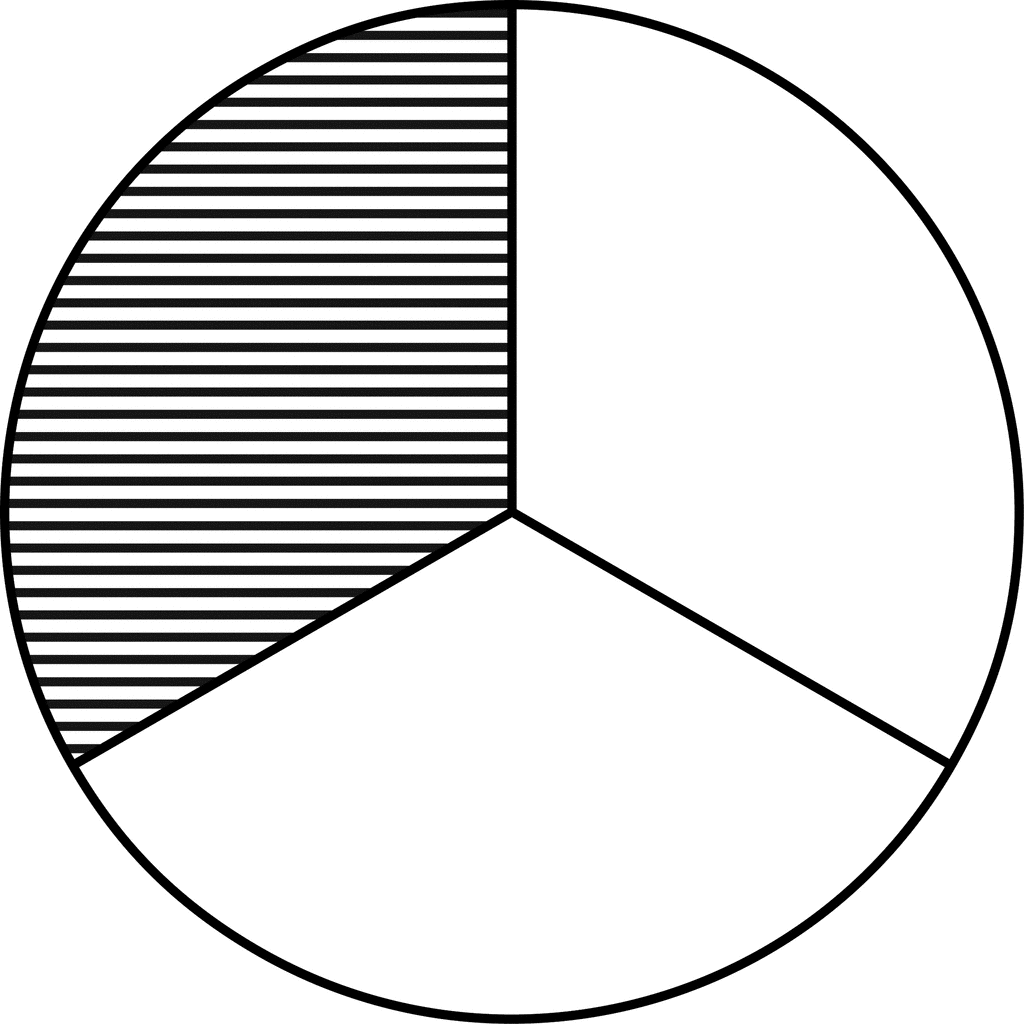
The fraction 1/3 also helps in conceptualizing time. If we divide our productive lives into thirds—the learning phase (20-40), the earning phase (40-60), and the legacy phase (60+)—we can better align our financial tools with our life stages.
In the first third, the focus is on human capital and skill acquisition. In the second third, the focus shifts to maximizing the fraction of income saved. In the final third, the focus moves to the fraction of assets that can be safely withdrawn without depleting the principal.
Leveraging Digital Tools to Automate Your Fractions
In the modern financial landscape, you no longer need a slide rule to calculate these fractions. Fintech tools and AI-driven banking apps allow users to set “rules” that automate the 1/3 split.
-
Automated Transfers: Most modern banks allow you to split your direct deposit. Setting your account to automatically send 33% to a brokerage account ensures that the fraction is honored before you even see the money.
-
Fractional Share Investing: The rise of fractional shares has democratized the 1/3 rule. Previously, an investor with $1,000 might not have been able to diversify across expensive stocks. Now, you can buy exactly 1/3 of a share or allocate exactly $333.33 across different sectors regardless of the share price.
-
Robo-Advisors: These platforms use algorithms to maintain your desired fractions. They perform the “fractional rebalancing” mentioned earlier, selling high and buying low across your 1/3 allocations without any manual intervention.
By utilizing these tools, the abstract concept of “1/3” becomes a concrete reality. It moves from a mathematical idea to a functional system that builds wealth silently in the background.
Ultimately, asking “what fraction is 1/3” in a financial context reveals a philosophy of balance. It is a rejection of excess in any one direction. By committing to the 1/3 rule in budgeting, investing, and debt management, you create a robust financial architecture that can withstand the infinite variables of the global economy. 1/3 is not just a repeating decimal; it is the repeating pattern of financial success.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.