
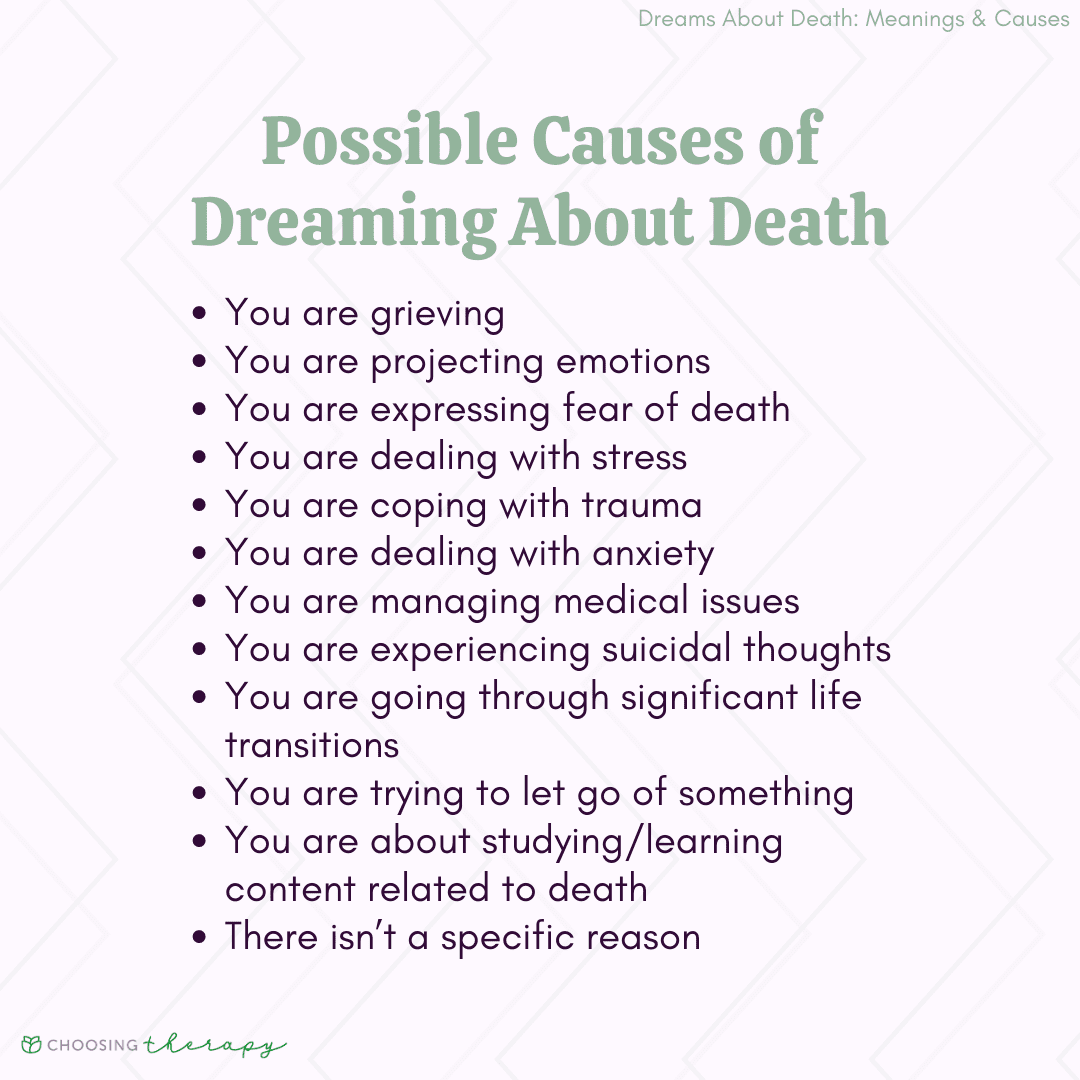
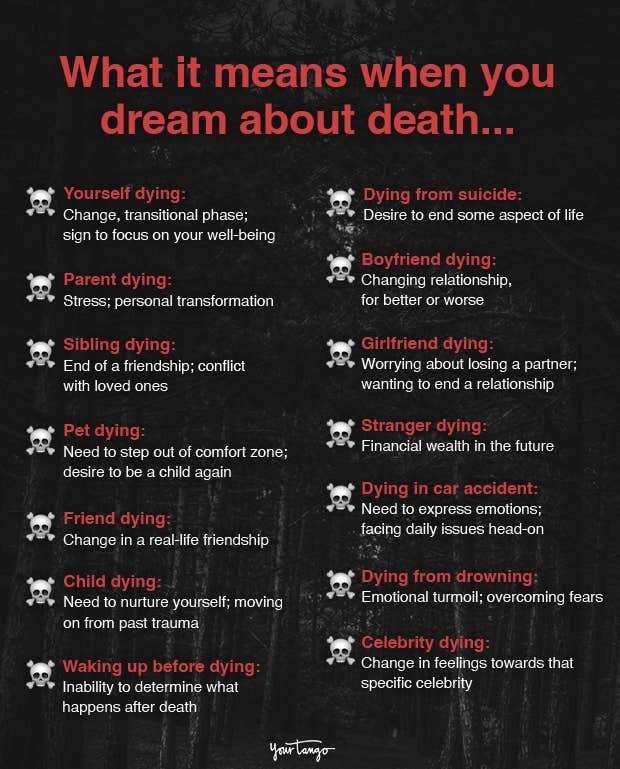
The imagery of death in a dream can be startling, evoking primal fears and deep introspection. While often dismissed as mere subconscious wanderings or morbid curiosity, such dreams, when viewed through a pragmatic lens, can serve as powerful psychological prompts. In the realm of personal finance and wealth management, “dreaming about death” transcends its literal interpretation to become a profound metaphor: a call to confront our mortality, evaluate our financial preparedness, and strategically plan for the future—both our own and that of our loved ones. It’s not about impending doom, but about the “death” of complacency and the “rebirth” of proactive financial stewardship. This article delves into how this metaphorical awakening can catalyze essential financial planning, securing legacies, and fostering enduring peace of mind.
The Metaphor of Mortality: A Financial Wake-Up Call
The unsettling nature of dreams involving death often forces us to consider the impermanence of life. Instead of succumbing to existential dread, those who are financially astute recognize this introspection as a critical opportunity. It prompts a shift from short-term financial gratification to long-term strategic thinking, acknowledging that life is finite and responsible planning is paramount. This metaphorical “death” is the death of procrastination, of putting off difficult but necessary financial conversations, and of neglecting the foundational pillars of a robust financial future.
Shifting Perspectives: From Existential Dread to Strategic Action
When confronted with the concept of mortality, either consciously or subconsciously through dreams, our priorities often sharpen. The fleeting nature of existence can illuminate the importance of financial security, not just for ourselves, but for those we care about most. This shift in perspective transforms potential anxiety into actionable steps. Instead of dwelling on the “what ifs,” individuals begin to ask “what should I do now?” This includes assessing current assets, liabilities, income streams, and future financial needs. It’s about converting a potentially unsettling thought into a powerful motivational force for wealth accumulation, protection, and distribution. The goal moves from simply accumulating wealth to ensuring its purpose and continuity beyond one’s immediate control.
Recognizing the Value of Time and Resources
A dream about death, even metaphorically, underscores the finite nature of time—our most precious resource. In financial terms, this translates into recognizing the diminishing window for investment growth, career earnings, and active management of assets. It encourages individuals to maximize the utility of their present resources, making informed decisions about saving, investing, and spending. Understanding that wealth is not just about accumulation but about strategic deployment over time becomes crucial. It compels us to move beyond passive observation of our finances to active engagement, leveraging every moment and every dollar towards creating a secure and lasting financial legacy. This proactive stance ensures that wealth serves its intended purpose, whether it’s funding retirement, supporting family, or contributing to charitable causes, rather than being squandered due to inertia or lack of foresight.
Safeguarding Your Legacy: Estate Planning as a Cornerstone
If “dreaming about death” serves as a wake-up call, then robust estate planning is the definitive answer within the financial realm. Estate planning is not solely for the ultra-wealthy; it is a fundamental component of financial responsibility for anyone who wishes to control how their assets are distributed and managed after their passing. It’s about ensuring that your wishes are honored, your loved ones are protected from undue financial burdens, and your legacy endures according to your principles. It meticulously addresses the “what happens next?” question, providing clarity and comfort for all involved.
Wills and Trusts: Directing Your Wealth
At the heart of estate planning are wills and trusts, the legal instruments that articulate your intentions for your assets. A Last Will and Testament is a foundational document, outlining who will inherit your property, who will be responsible for administering your estate (the executor), and often, who will be guardian to minor children. Without a will, state laws dictate asset distribution, which may not align with your desires, leading to potential disputes and delays.
Trusts, on the other hand, offer more intricate control and can be particularly beneficial for specific goals, such as asset protection, privacy, or staggered distribution to beneficiaries. A revocable living trust, for instance, allows assets to bypass probate, a potentially lengthy and costly court process, and can provide for management of your assets if you become incapacitated. Other trusts, like testamentary trusts (created through a will) or irrevocable trusts (offering greater asset protection and tax benefits), serve various strategic purposes. Understanding the differences and selecting the appropriate instruments is crucial for effectively directing your wealth.
Beneficiary Designations: Ensuring Smooth Transitions
Often overlooked, but equally vital, are beneficiary designations on financial accounts like life insurance policies, retirement accounts (401(k)s, IRAs), and annuities. These designations dictate who receives the assets upon your death, often superseding instructions in a will. Properly completed beneficiary forms ensure that funds are transferred directly to your chosen recipients, bypassing probate and minimizing delays. Regularly reviewing and updating these designations is imperative, especially after significant life events such as marriage, divorce, birth of children, or death of a previous beneficiary. Incorrect or outdated designations can lead to unintended consequences, diverting funds from your desired heirs or creating unnecessary legal complications and financial stress for your family during a difficult time.
The Importance of Digital Estate Planning
In our increasingly digital world, a comprehensive estate plan must extend beyond tangible assets to include your digital estate. This encompasses everything from online bank accounts and investment portfolios to social media profiles, email accounts, digital photos, cryptocurrencies, and even loyalty program points. Access to these digital assets can be challenging for executors or family members without proper authorization and passwords. Digital estate planning involves creating an inventory of all online accounts, specifying access instructions, and appointing a digital executor or trustee. Services exist that allow secure storage of this information, which can then be released to designated individuals upon notification of your death. Ignoring the digital aspect of your legacy can lead to inaccessible assets, lost memories, and a digital footprint that remains unmanaged, highlighting the need for a modern, holistic approach to estate planning.
Protecting Your Loved Ones: Insurance and Contingency Planning
The metaphorical “dreaming about death” also shines a light on our profound responsibility to protect those we leave behind. While estate planning directs assets, insurance and robust contingency planning provide the financial safety net that ensures your family’s financial stability and continuity of life without your direct income or support. These tools mitigate the unforeseen risks of life, transforming potential catastrophes into manageable challenges. They are the practical manifestation of care and foresight, ensuring that your loved ones can grieve without the added burden of financial distress.
Life Insurance: A Shield Against Financial Hardship
Life insurance is perhaps the most direct financial answer to the contemplation of mortality. Its primary purpose is to provide a financial payout to your beneficiaries upon your death, replacing lost income and covering essential expenses. This can include mortgage payments, children’s education costs, daily living expenses, and outstanding debts. Without adequate life insurance, a family accustomed to a certain lifestyle could face significant hardship, potentially losing their home or delaying crucial life milestones.
There are various types of life insurance, each serving different needs:
-
Term life insurance provides coverage for a specific period (e.g., 10, 20, or 30 years) and is generally more affordable, suitable for covering needs during prime earning years.
-
Whole life insurance provides lifelong coverage and accumulates cash value over time, which can be borrowed against or withdrawn.
-
Universal life insurance offers more flexibility in premiums and death benefits.
Choosing the right type and amount of coverage requires careful consideration of your family’s current and future financial obligations, ensuring a robust shield against the sudden financial void your absence could create.
Long-Term Care Insurance: Preserving Assets in Advanced Age
While not directly tied to death, long-term care insurance is a critical component of end-of-life financial planning that protects assets and ensures dignity in advanced age. As lifespans increase, so does the probability of needing long-term care services due to illness, disability, or cognitive impairment. These services, which can include in-home care, assisted living, or nursing home care, are incredibly expensive and typically not covered by standard health insurance or Medicare.
Without long-term care insurance, the substantial costs can rapidly deplete savings and assets intended for heirs, effectively diminishing the legacy you worked so hard to build. Long-term care insurance helps cover these expenses, allowing individuals to receive necessary care without becoming a financial burden on their families or eroding their estate. It’s an investment in both your future well-being and the preservation of your financial legacy for your loved ones.
Emergency Funds: The Immediate Safety Net
Beyond catastrophic events, the metaphorical “death” of financial stability due to unexpected circumstances highlights the importance of an immediate safety net: an emergency fund. While life insurance addresses the ultimate contingency, an emergency fund protects against shorter-term financial shocks—job loss, medical emergencies, unforeseen home repairs, or temporary incapacitation.
Typically, an emergency fund should hold three to six months’ worth of essential living expenses, stored in an easily accessible, liquid account (like a high-yield savings account). This fund acts as a crucial buffer, preventing you from dipping into long-term investments, incurring high-interest debt, or disrupting your overall financial plan when unexpected challenges arise. It’s a fundamental step in building financial resilience, ensuring that minor crises don’t escalate into major setbacks, thereby safeguarding your ongoing ability to build and protect your wealth.
Generational Wealth and Values: Beyond Monetary Inheritance
The introspection prompted by “dreaming about death” can extend beyond mere asset distribution to a deeper contemplation of legacy: what values, wisdom, and opportunities do we wish to pass down? Generational wealth is not solely about transferring money; it’s about instilling financial literacy, fostering responsible stewardship, and leaving a positive social imprint. It acknowledges that true wealth encompasses more than just bank balances; it includes intellectual, social, and human capital. This holistic view ensures that your influence extends far beyond your material possessions.
Fostering Financial Literacy in Heirs
One of the most valuable gifts you can bestow upon your heirs is financial literacy. Simply inheriting money without the knowledge to manage it responsibly can often lead to its rapid dissipation. Educating children and grandchildren about budgeting, saving, investing, debt management, and philanthropy is crucial for ensuring the longevity of family wealth. This involves open conversations about money, involving them in age-appropriate financial decisions, and perhaps even formal education or mentorship. By teaching sound financial principles, you empower your heirs to not only preserve their inheritance but to grow it, contributing to their own financial independence and the continued prosperity of future generations. This intellectual legacy can be far more enduring than any monetary gift alone.
Philanthropy and Charitable Giving: Leaving a Social Imprint
For many, the contemplation of their mortality sparks a desire to leave a legacy that transcends personal gain and contributes to the greater good. Philanthropy and charitable giving allow individuals to direct a portion of their wealth to causes they deeply care about, leaving a lasting social imprint. This can be achieved through direct donations, establishing charitable trusts, or creating a family foundation. Strategic charitable giving can also offer tax advantages, but its primary motivation is often the profound satisfaction of knowing one’s resources are making a tangible difference in the world. Whether supporting education, environmental conservation, medical research, or social justice, aligning your financial legacy with your values allows your impact to continue long after you’re gone, enriching communities and inspiring future generations.
The Gift of Time and Wisdom: Non-Monetary Legacy
Finally, “dreaming about death” reminds us that our most profound legacy may not be financial at all, but rather the intangible gifts of time, wisdom, and guidance. While not directly “money” in the traditional sense, these non-monetary inheritances significantly impact the financial and overall well-being of our heirs. Sharing life lessons, moral compass, family history, and personal experiences provides a rich tapestry of values that can guide future generations in their decisions, including financial ones. Mentoring young family members, sharing insights from your own successes and failures, and fostering strong family bonds contribute to a robust “human capital” that often proves more valuable than any sum of money. This holistic legacy ensures that the family’s identity, resilience, and wisdom are passed down, creating a foundation upon which future prosperity can be built.
Embracing Financial Clarity: Actionable Steps Today
The metaphorical “dreaming about death” is not an invitation to despair, but a powerful impetus for clarity and action. It encourages us to take control of our financial narrative, transforming vague anxieties into concrete plans. The realization of life’s finite nature should motivate us to seek knowledge, engage with professionals, and consistently review our strategies. This proactive approach culminates in profound peace of mind, knowing that we have done everything within our power to secure our own future and provide for those we love.
Seeking Professional Guidance
Navigating the complexities of estate planning, insurance, investments, and tax laws can be daunting. This is where the expertise of financial professionals becomes invaluable. Engaging a qualified financial advisor, estate planning attorney, and tax specialist ensures that your plans are comprehensive, legally sound, and optimized for your specific circumstances. These professionals can help you:
-
Assess your current financial situation.
-
Clarify your goals and values.
-
Develop a personalized financial roadmap.
-
Implement appropriate legal documents and investment strategies.
-
Navigate complex regulations and minimize potential pitfalls.
Their objective insights and specialized knowledge provide the confidence and assurance that your “death dream” catalyst is translated into effective, real-world financial solutions, providing peace of mind knowing your affairs are in order.
Regular Review and Adaptation
Financial planning is not a one-time event; it is an ongoing process that requires regular review and adaptation. Life circumstances change—marriages, births, deaths, career shifts, inheritances, and market fluctuations all impact your financial picture. Tax laws evolve, and your own priorities may shift over time. Just as a dream about death might prompt initial reflection, regular financial check-ups ensure your plan remains relevant and effective.
Schedule annual reviews with your financial team to:
-
Update beneficiary designations.
-
Adjust investment strategies.
-
Re-evaluate insurance needs.
-
Amend wills and trusts as necessary.
This dynamic approach ensures that your financial legacy accurately reflects your current wishes and continues to serve its intended purpose through all stages of life.
The Peace of Mind from Preparedness
Ultimately, the most profound meaning of “dreaming about death” in a financial context is the immense peace of mind that comes from being prepared. Knowing that your financial affairs are in order, that your loved ones are protected, and that your legacy will endure according to your wishes alleviates a significant source of anxiety. This peace allows you to live more fully in the present, free from the worry of an uncertain future. It transforms a potentially unsettling psychological trigger into a catalyst for empowerment, responsibility, and profound tranquility. By actively addressing the financial implications of mortality, you don’t just plan for death; you plan for life—a life lived with purpose, security, and a lasting legacy.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.