
In the world of personal and business finance, maturity often brings a peculiar set of challenges. Just as the human body develops wisdom teeth late in its physical growth—often causing sudden, throbbing pain that requires professional intervention—an investment portfolio or a scaling business frequently encounters “financial wisdom teeth.” These are the legacy liabilities, high-interest debts, and unforeseen tax implications that emerge precisely when you feel you have finally reached a stage of stability.
When your financial wisdom tooth hurts, it is a signal that your current structure can no longer accommodate your growth. Ignoring the ache leads to systemic infection—or in financial terms, a liquidity crisis. This guide explores how to identify, treat, and if necessary, “extract” these financial burdens to ensure long-term fiscal health.

Identifying the Financial Wisdom Tooth: What are Legacy Liabilities?
Before you can treat the pain, you must identify its source. In finance, a “wisdom tooth” is any obligation or asset that served a purpose during your “adolescent” growth phase but has now become crowded, obsolete, or actively harmful to your mature financial goals.
The Hidden Costs of Scaling
In the early stages of a side hustle or a startup, we often take shortcuts. We might use high-interest personal credit lines to fund inventory, or we might neglect complex tax structuring in favor of simple “cash-in, cash-out” accounting. As the venture matures, these shortcuts begin to ache. What was once a manageable $5,000 balance at 22% APR becomes a “wisdom tooth” that prevents you from reinvesting profits into more lucrative opportunities. Scaling requires a shift from survival-based financing to strategic capital management.
High-Interest Debt: The Impacted Molar of Finance
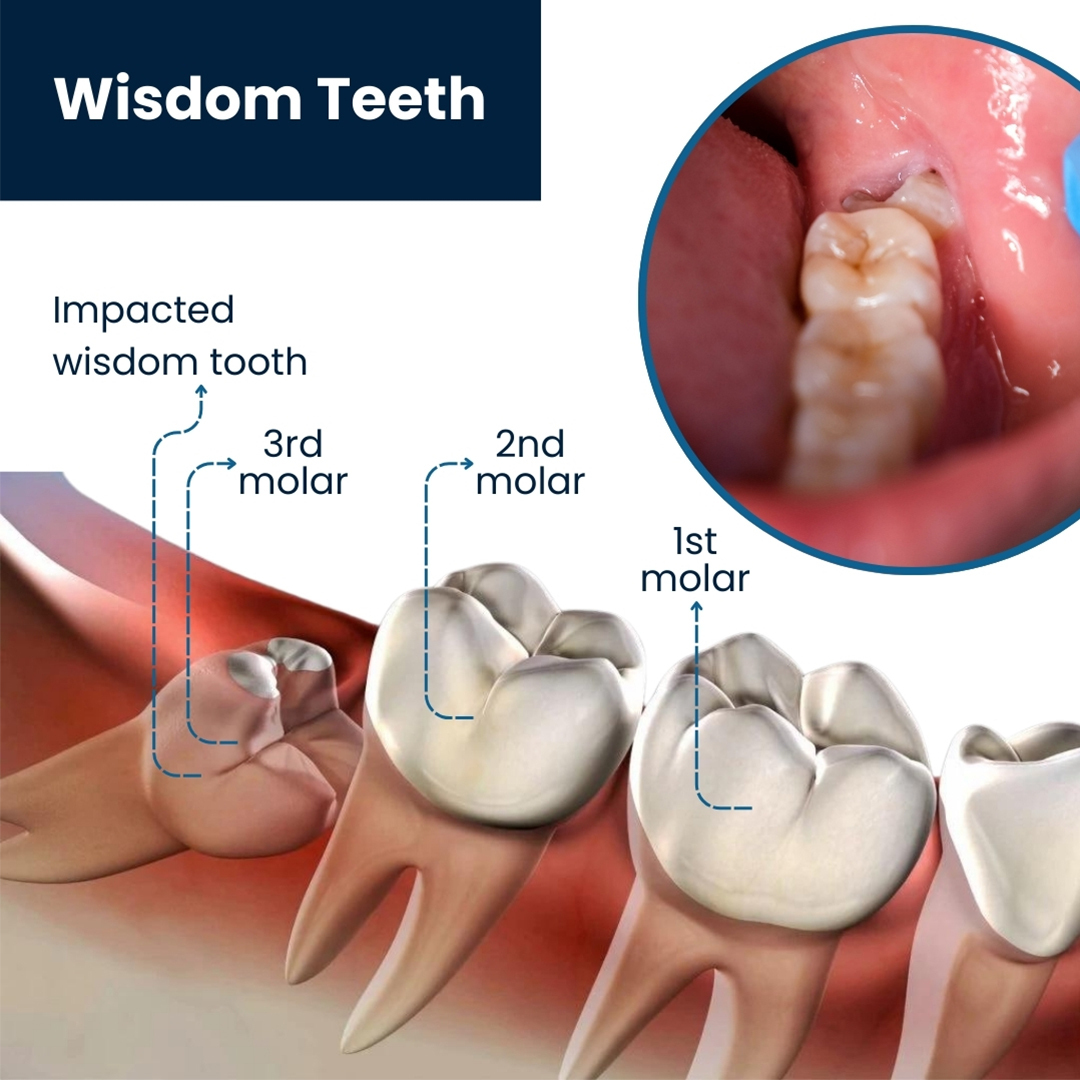
High-interest debt is the most common form of financial wisdom tooth pain. Like an impacted molar, it sits beneath the surface, slowly pushing against your healthy assets. If you are carrying credit card debt or high-interest bridge loans while simultaneously trying to build an investment portfolio, the “pain” you feel in your monthly cash flow is the interest eating your margins. Identifying these high-cost liabilities is the first step toward relief.
Outdated Asset Allocations
Sometimes the pain comes from an investment that worked five years ago but no longer fits your risk profile. An aggressive, small-cap heavy portfolio might have been appropriate in your 20s, but as you approach a need for liquidity—perhaps for a home purchase or business expansion—that volatility becomes a source of stress. This “wisdom tooth” isn’t necessarily a “bad” asset; it’s simply one that is out of place in your current financial anatomy.
Immediate Pain Relief: Short-Term Strategies for Cash Flow Crises
When financial pain becomes acute—perhaps due to a sudden market downturn or an unexpected tax bill—you need immediate intervention. You cannot perform a full “extraction” of a complex liability while in the middle of a crisis; you must first stabilize the situation.
Assessing the Damage: Audit and Analysis
The first step in any financial emergency is a comprehensive audit. You must look at your debt-to-income ratio and your current liquidity. When the “tooth hurts,” the worst thing you can do is apply a temporary bandage, like taking out a “payday” style business loan. Instead, categorize your expenses into “vital” and “discretionary.” This clarity acts as the diagnostic X-ray, showing exactly where the pressure is coming from and which liabilities are causing the most significant drag on your net worth.
Debt Restructuring and Consolidation
If the pain is caused by multiple high-interest obligations, consolidation is your anesthesia. By moving high-interest balances to a lower-interest personal loan or a 0% APR balance transfer card (for those with the credit standing), you stop the immediate throbbing of compound interest. In a business context, this might involve refinancing short-term debt into a long-term SBA loan. The goal is to lower the monthly “pain” (cash outflow) to allow for a more strategic, long-term solution.
Enhancing Immediate Liquidity
Sometimes the “pain” is simply a lack of cash. In these moments, you must look for “low-hanging fruit.” This might mean selling off underperforming assets or tightening your accounts receivable processes. If you are a freelancer or business owner, “what to do when it hurts” often translates to: get paid faster. Offering a 2% discount for invoices paid within ten days can provide the immediate liquid “pain relief” needed to settle pressing liabilities without taking on new debt.
Extraction vs. Treatment: When to Cut Your Losses
In dentistry, some teeth can be saved with a filling, while others must be pulled. Finance operates on the same principle. You must decide whether to “treat” a financial problem (restructure it) or “extract” it (liquidate or write it off).
Evaluating ROI on Failing Assets
Every asset in your portfolio and every line item in your business budget should have a Return on Investment (ROI). When a particular venture or investment is consistently “hurting” your bottom line, you must perform a cold, calculated analysis. Is the pain temporary market volatility, or is it a fundamental shift in the asset’s value? If an investment has a “negative carry”—meaning it costs more to maintain than it produces in value—it is a candidate for extraction.
The Sunk Cost Fallacy in Business Finance
The biggest obstacle to “extracting” a financial wisdom tooth is the sunk cost fallacy. We tend to hold onto losing investments or failing business departments because we have already “invested so much.” However, professional financial management requires looking forward, not backward. If a project is draining $2,000 a month in capital that could be earning 8% elsewhere, the most “wise” move is to cut the cord. Extraction might be painful in the short term (realizing a loss), but it prevents the “infection” from spreading to the rest of your portfolio.
Tax Loss Harvesting: Turning Extraction into Advantage
One of the most sophisticated ways to handle a “painful” financial asset is through tax-loss harvesting. If you have an investment that has lost value, selling it (extracting it) allows you to use that loss to offset capital gains elsewhere. This turns a negative situation into a strategic financial tool, reducing your overall tax liability and freeing up capital to be moved into more productive, “painless” assets.
Preventative Care: Building a Resilient Financial Infrastructure
Once the immediate pain is managed and the problematic liabilities are extracted, the focus must shift to preventative care. You want to ensure that as you continue to grow and gain “wisdom,” you don’t face the same level of discomfort again.
Implementing Robust Cash Reserves
The best “mouthwash” for financial health is a robust emergency fund. For individuals, this is typically 3–6 months of expenses; for businesses, it’s a “burn rate” cushion. When you have a cash reserve, minor “aches” (like a broken piece of equipment or a slow sales month) don’t turn into full-blown emergencies. This liquidity provides the freedom to make decisions based on strategy rather than desperation.
Diversification as a Shield Against Market Volatility
Pain often stems from over-exposure. If 80% of your net worth is tied up in a single stock or a single business, you are at the mercy of factors beyond your control. Diversification across asset classes—equities, real estate, fixed income, and commodities—ensures that even if one “tooth” starts to ache, the rest of your financial structure remains sound. Professional wealth management is less about picking winners and more about building a structure that can survive losers.
Automating Financial Hygiene
Finally, just as daily brushing prevents cavities, automated financial systems prevent the buildup of “plaque” (unnecessary fees and late payments). Automating your savings, your debt repayments, and your investment contributions ensures that your financial health is maintained even when you aren’t actively thinking about it. Using AI-driven financial tools can help track your spending patterns and alert you to “inflammation” in your budget before it becomes a painful crisis.
In conclusion, when your “financial wisdom tooth” hurts, it isn’t a sign of failure—it’s a sign of transition. It means you have outgrown your old ways of managing money. By identifying the source of the pain, utilizing short-term relief strategies, making the hard decision to extract failing assets, and committing to long-term preventative care, you can move past the discomfort and into a stage of mature, stable wealth. Don’t ignore the ache; address it with the precision and professional insight your future self deserves.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.