
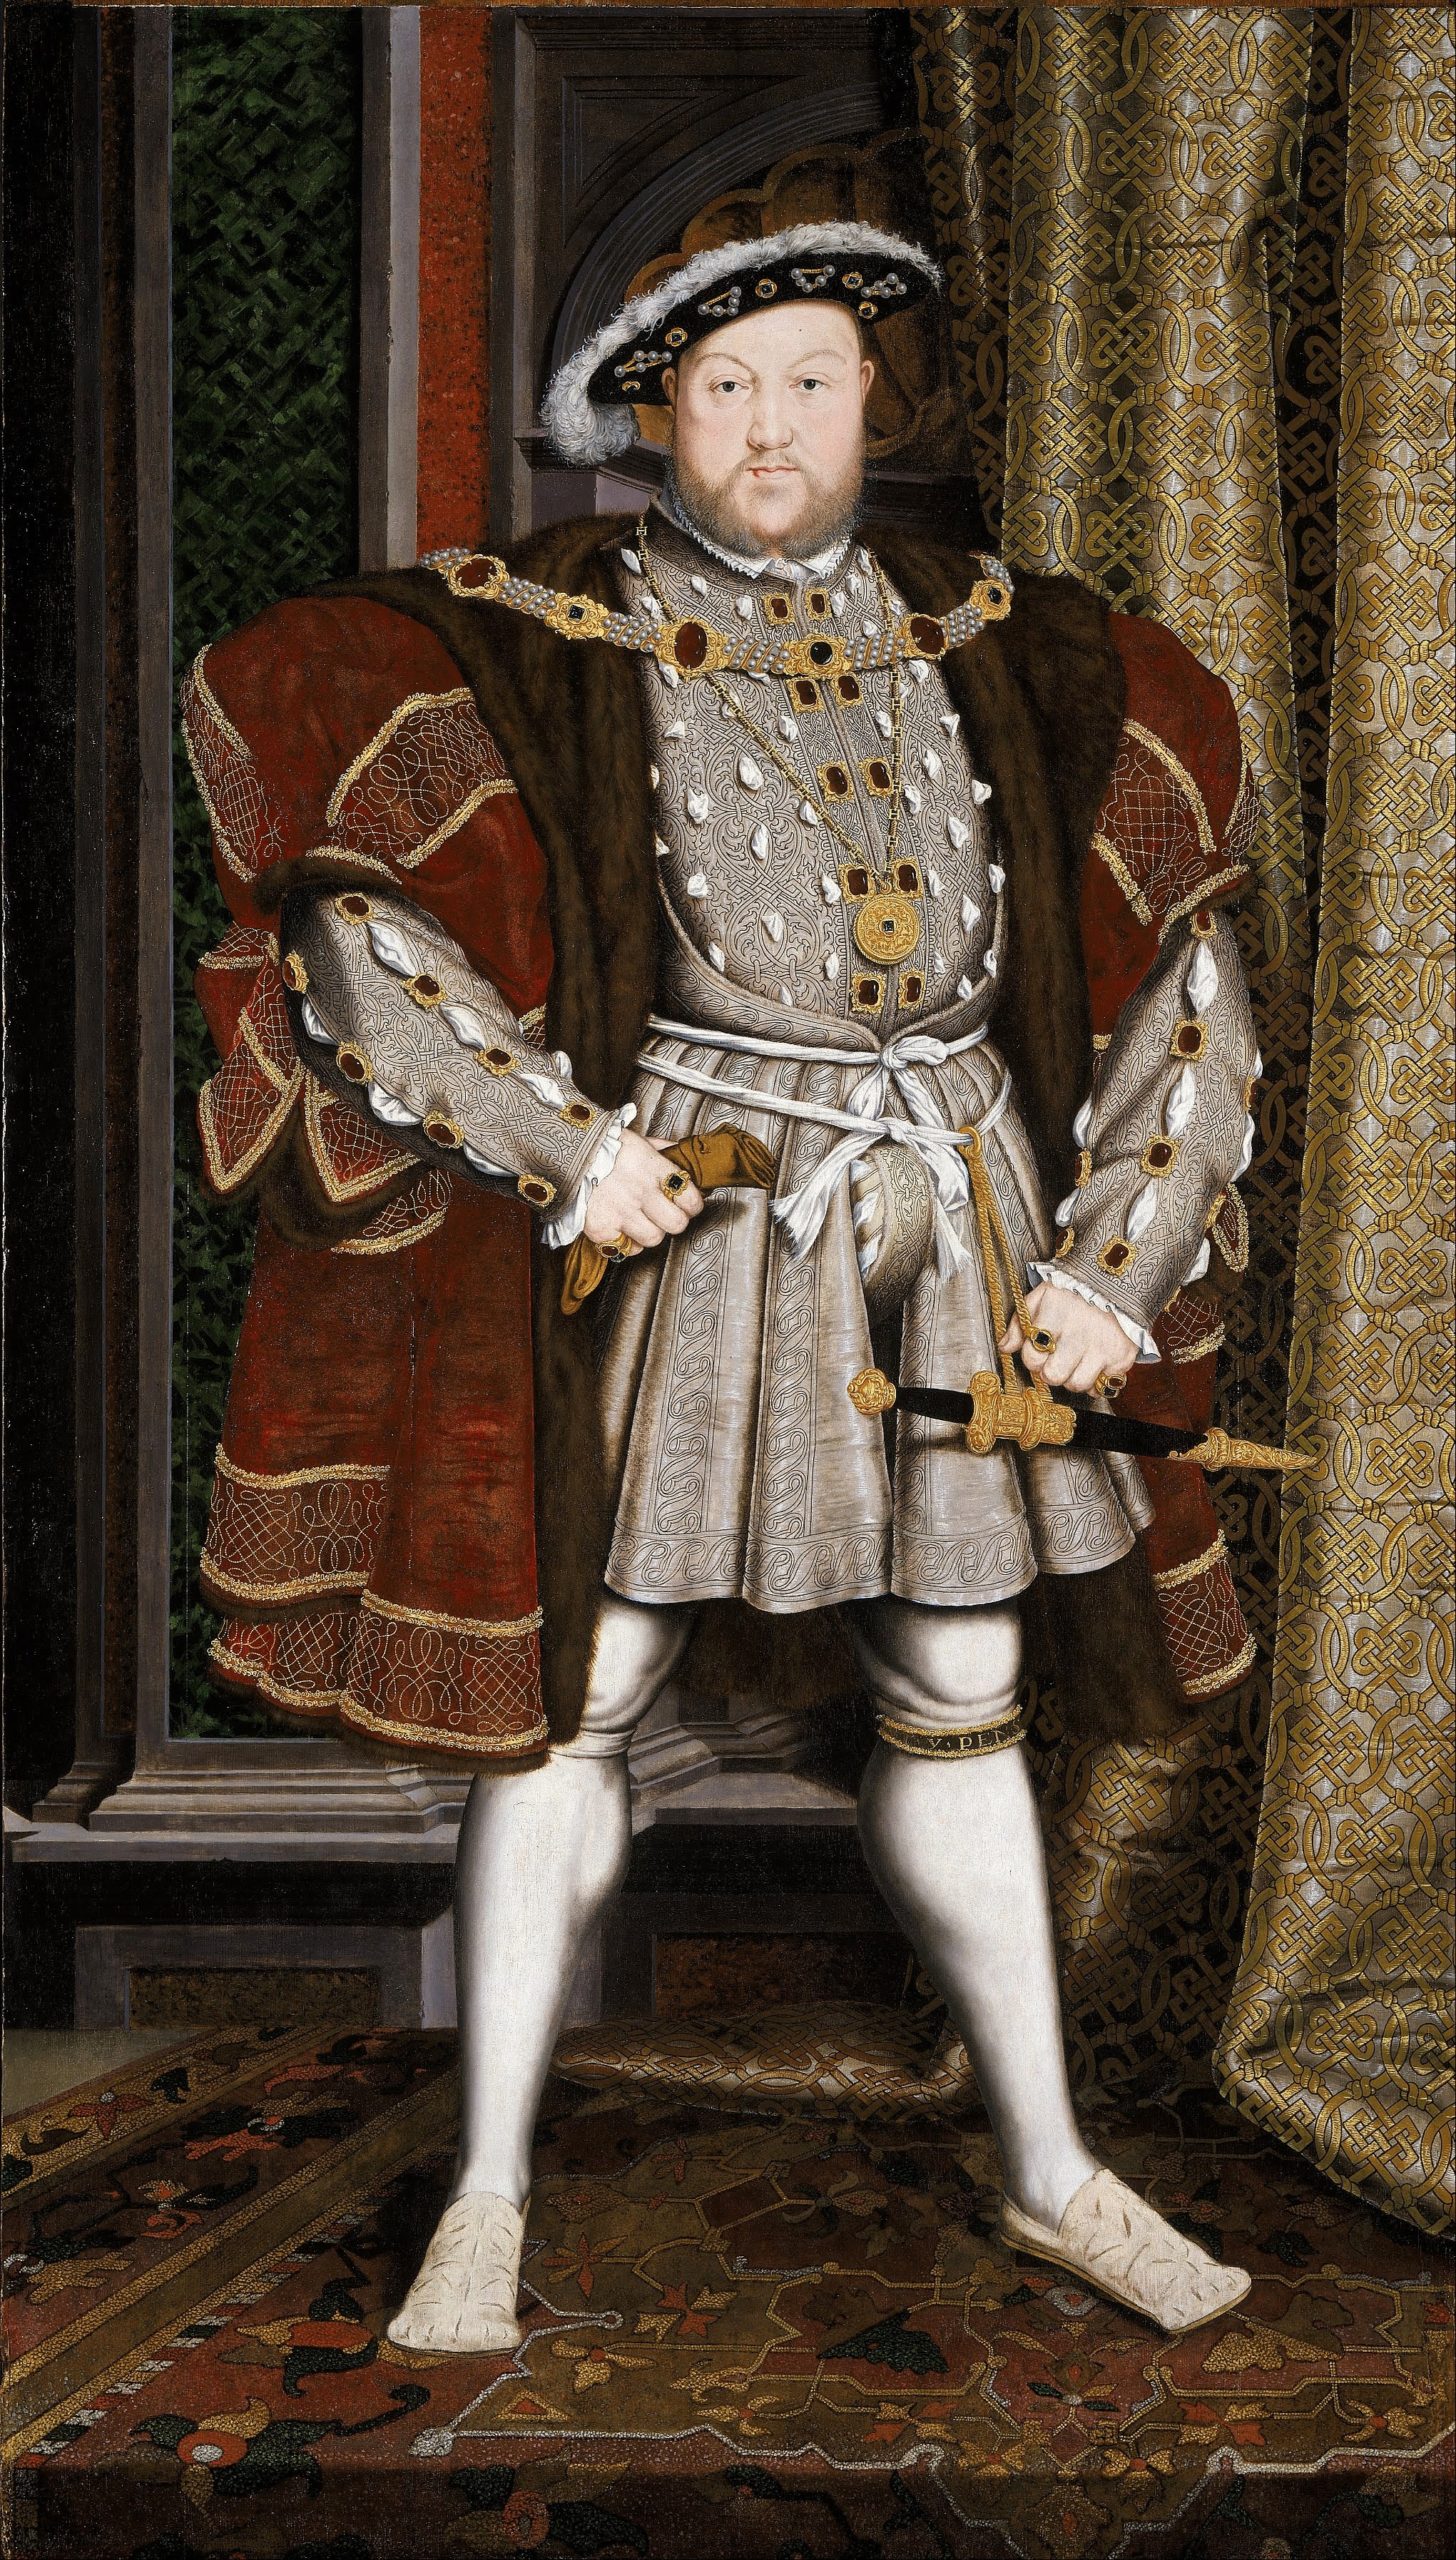
For centuries, the global financial landscape has been dominated by a traditional orthodoxy centered in the City of London. Much like the historical shifts that redefined societal structures, we are currently witnessing a “Reformation in England”—not of the church, but of the very fabric of money, banking, and investment. This modern upheaval is characterized by the dismantling of legacy banking monopolies and the rise of a decentralized, digital-first financial theology. As England navigates the complexities of a post-Brexit economy and the rapid advancement of financial technology (FinTech), the way individuals and corporations manage wealth is undergoing a permanent transformation.

The End of the High Street Monarchy: The Shift from Traditional to Digital
The “High Street” bank was once the undisputed sovereign of English personal finance. For generations, the “Big Four”—Barclays, HSBC, Lloyds, and NatWest—held a near-monopoly on consumer trust and capital. However, the modern financial reformation has begun to strip away this absolute power, driven by a consumer base that values agility over heritage.
The Decline of Brick-and-Mortar Dominance
In the past decade, thousands of bank branches have vanished from English town centers. This physical retreat is not merely a cost-cutting measure; it is a symptom of a deeper systemic shift. As digital literacy increases across all demographics, the necessity of a physical vault and a face-to-face teller has diminished. This “Great Closure” has forced a migration of capital toward digital platforms that offer 24/7 accessibility, lower overhead costs, and higher interest rates for savers. For the modern English investor, the “branch” is now an app in their pocket, representing a total detachment from the geography of traditional finance.
Challenging the “Big Four” Banks
The rise of “Challenger Banks” represents the most visible front of the English financial reformation. Institutions like Monzo, Starling, and Revolut have successfully dismantled the barriers to entry that once protected legacy giants. By eliminating hidden fees and providing real-time data analytics, these newcomers have won the hearts of the younger generation. The shift is not just aesthetic; it is structural. Traditional banks have been forced to overhaul their legacy IT systems—many of which were built in the 1970s—just to compete with the seamless user experiences offered by these digital natives. This competition has democratized banking, transferring power from the institution back to the account holder.
The Proclamation of Open Banking: Regulatory Catalysts
Every reformation requires a set of laws to institutionalize change. In England’s financial sector, this was achieved through the implementation of “Open Banking.” This regulatory framework, mandated by the Competition and Markets Authority (CMA) and influenced by European PSD2 standards, has been the primary catalyst for the decentralization of financial data.
PSD2 and the Democratization of Data
Open Banking operates on a simple yet radical premise: your financial data belongs to you, not your bank. By requiring banks to share customer data (with permission) via secure Application Programming Interfaces (APIs), the UK government effectively ended the data silos that had long stifled innovation. This has allowed third-party providers to create bespoke financial products that were previously impossible. Whether it is an automated savings bot or an investment platform that aggregates all your accounts into one view, Open Banking is the “Common Prayer Book” of the new financial era—standardizing the language through which different systems communicate.
Consumer Empowerment and Personal Finance Management
The practical result of this data democratization is the rise of hyper-personalized finance. In the old regime, financial advice was the province of the wealthy, delivered by expensive consultants. Today, English consumers use Open Banking-enabled apps like Emma or Money Dashboard to track every penny, categorize spending, and identify “leakage” in their budgets. This reformation has made financial literacy more accessible, allowing individuals to optimize their cash flow and debt management with a level of precision that was once reserved for corporate treasuries.
The Protestant Work Ethic of the Startup Scene: Growth Drivers

London remains the jewel in the crown of the English financial reformation, serving as a global magnet for venture capital and entrepreneurial talent. The city’s unique position—sitting between the time zones of New York and Tokyo—combined with a sophisticated regulatory environment, has created a “Protestant Work Ethic” among FinTech startups that are determined to outwork and out-innovate the old guard.
Venture Capital and the London Ecosystem
Despite economic headwinds, the UK continues to attract billions in FinTech investment, often outpacing the rest of Europe combined. This influx of capital is the fuel for the reformation. It allows “unicorns” to scale rapidly, moving beyond simple checking accounts into complex lending, mortgage brokerage, and insurance (InsurTech). The government’s Enterprise Investment Scheme (EIS) and Seed Enterprise Investment Scheme (SEIS) have further incentivized this shift, offering tax breaks to those willing to fund the “reformers” of the financial world.
Case Studies: Revolut and Monzo as the New Clergy
If we look at the leaders of this movement, companies like Revolut have moved far beyond their origins as travel cards. They have become “super-apps,” offering everything from stock trading and commodities to crypto-assets and business accounts. Meanwhile, Starling Bank has demonstrated that a digital-only bank can achieve sustained profitability while maintaining high levels of customer satisfaction. These companies are no longer “alternatives”; for many in England, they are the primary financial institution. Their success has forced a total re-evaluation of what a “bank” should be in the 21st century.
Decentralized Finance (DeFi) as the New Theology
As the reformation matures, it is moving into more radical territory: the complete decentralization of the financial system through blockchain and Distributed Ledger Technology (DLT). This is the “radical reformation” of the money world, questioning the very necessity of a central intermediary or a state-controlled currency.
Crypto-Assets and the Bank of England’s Stance
While the initial hype surrounding cryptocurrencies has fluctuated, the underlying technology—blockchain—is being taken very seriously by English authorities. The Bank of England (BoE) has moved from a position of skepticism to one of active engagement. The discussion is no longer about whether digital assets have value, but how they can be integrated into a stable financial system. For the private investor, this has meant the inclusion of digital assets as a legitimate, albeit volatile, asset class within a diversified portfolio.
The Future of CBDCs (Central Bank Digital Currencies)
The most significant development on the horizon is the potential “Digital Pound,” often nicknamed “Britcoin.” This would represent a state-backed digital currency that combines the stability of the Pound Sterling with the efficiency of digital technology. This move by the Bank of England is a defensive play against the total decentralization of money, ensuring that the state remains relevant in a world where “programmable money” is becoming the norm. It represents the ultimate synthesis of the old and new worlds—a reformation that preserves the core of the institution while adopting the tools of the revolution.
Navigating the New Financial Landscape: Practical Advice
For the individual looking to manage their money in the midst of this reformation, the old rules no longer apply. Wealth preservation and growth now require a proactive approach to technology and a willingness to diversify away from traditional safe havens.
Diversifying Investments in a Digital Age
Modern English investors are increasingly moving away from simple savings accounts, which often struggle to keep pace with inflation. Instead, they are utilizing low-cost “Robo-advisors” like Nutmeg or Wealthify to access global markets. These platforms use algorithms to manage risk and rebalance portfolios, providing sophisticated investment strategies to the masses. Furthermore, the reformation has opened doors to “fractional investing,” allowing individuals to own portions of high-value assets—be it real estate, fine art, or blue-chip stocks—with as little as £10.
Digital Security and Wealth Protection
As money becomes more digital, the “cathedrals” of the new era are no longer made of stone and iron, but of code and encryption. The reformation brings new risks, specifically in the realm of cybersecurity. Investors must now be as concerned with two-factor authentication and cold storage as they once were with physical safes. Understanding the security protocols of your chosen FinTech provider is now a fundamental part of financial due diligence. In this new era, the greatest threat to wealth is not a bank run, but a data breach or a lost private key.
In conclusion, the reformation in England is far from over. What began as a few digital apps has evolved into a total restructuring of the financial ecosystem. From the halls of the Bank of England to the smartphones of millions of citizens, the way money is created, moved, and invested has changed forever. To survive and thrive in this new era, one must embrace the tools of the reformation, moving beyond the traditions of the past toward a more transparent, efficient, and democratized financial future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.