
At first glance, the question “how many 1/3 are in 3/4” appears to be a simple arithmetic problem, a relic from grade school math. It’s a fundamental exercise in understanding fractions and division. Yet, beneath its unassuming exterior lies a profound metaphor for navigating the complex world of personal finance, investment, and wealth management. Far from a mere academic exercise, grasping the underlying principle of breaking down larger wholes into smaller, constituent parts – and understanding how those parts interrelate – is a cornerstone of financial literacy. In the realm of money, where every dollar, every investment, and every financial decision represents a fraction of a larger economic picture, mastering this “fractional thinking” isn’t just an advantage; it’s a necessity. This article will delve into how the seemingly simple concept of dividing fractions offers invaluable insights into managing your money, building wealth, and making astute financial decisions.
The Foundational Math: Beyond Simple Division to Financial Proportions
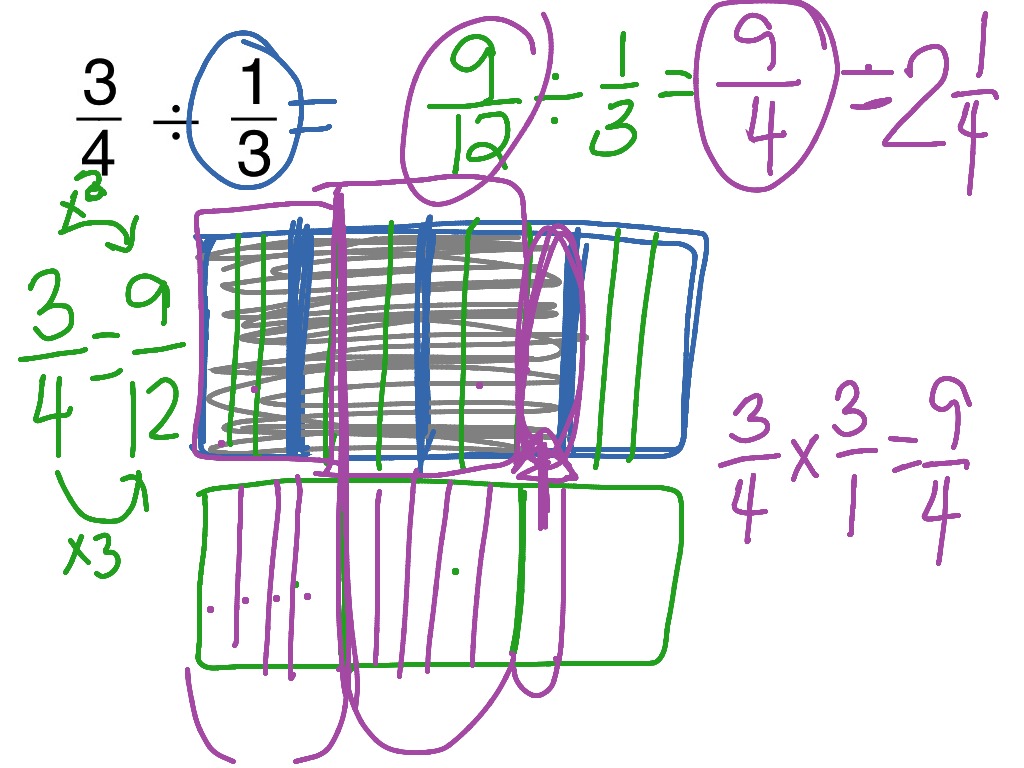
The mathematical solution to “how many 1/3 are in 3/4” is straightforward: you divide 3/4 by 1/3, which involves multiplying 3/4 by the reciprocal of 1/3 (which is 3/1). The answer is 9/4, or 2 and 1/4. This means there are two full 1/3 segments and an additional 1/4 of a 1/3 segment within 3/4. This precise breakdown of a whole into its constituent parts, or understanding how many smaller units fit into a larger fraction, is precisely the mental framework required for effective financial management.
Deciphering the “How Many”: Unpacking the Core Calculation
In finance, the “how many” question manifests in countless ways. How many units of a stock can you buy with a certain capital? How many months will it take to pay off a debt if you allocate a specific fraction of your income? How many percentage points of return do you need to achieve a financial goal within a certain timeframe? Each of these questions demands a similar approach to the fraction problem: understanding the total resource, the size of the individual unit, and then calculating how many of those units fit into the total. It’s about more than just numerical answers; it’s about developing an intuitive sense of scale, proportion, and allocation. When you look at your salary, it’s not just a lump sum; it’s a whole that must be fractioned out for taxes, living expenses, savings, and investments. Each of these categories represents a 1/3, or a 1/5, or a 1/X of your total.
From Abstract Fractions to Tangible Assets: A Paradigm Shift
The real magic happens when we shift our perspective from abstract numbers to tangible financial assets. Consider a portfolio of investments. The total value of your portfolio is the “3/4” in our analogy – it’s a significant portion of your financial picture. Each individual asset class – stocks, bonds, real estate, commodities – could be considered a “1/3” or some other fraction. Understanding “how many 1/3s” (or how many units of a specific asset) are within your overall 3/4 (your total portfolio) is critical for diversification, risk management, and strategic growth. This isn’t just theoretical; it impacts real-world decisions about asset allocation, rebalancing, and even understanding the impact of single investment performance on the entire portfolio. This fundamental understanding prevents an investor from seeing their portfolio as a single, monolithic entity, instead encouraging a more nuanced view of its diverse components.
Budgeting and Resource Allocation: Dividing Your Financial Pie
Perhaps nowhere is fractional thinking more evident and critical than in personal budgeting and resource allocation. Every income stream is a whole that must be systematically divided, and every expense represents a fraction of that whole. Without a clear understanding of how these fractions combine and subtract, financial stability becomes a precarious balancing act.
Strategic Spending: Allocating Income in Fractional Parts
The concept of “how many 1/3s are in 3/4” directly translates to how you manage your monthly income. Your paycheck is the “whole,” and your financial commitments – housing, utilities, food, transportation, entertainment, savings, debt payments – are the “1/3s” (or varying fractions) that must fit within it. A common budgeting strategy, for instance, is the 50/30/20 rule: 50% for needs, 30% for wants, and 20% for savings and debt repayment. This is precisely fractional thinking in action. You are asking: how many “units” of your income should go towards needs, wants, and savings? Each percentage point is a smaller fraction, and understanding how many of those smaller fractions make up your overall financial picture is paramount. Failing to account for each fractional outflow can lead to overspending, shortfalls, and a constant struggle to make ends meet. It requires a disciplined assessment of where each dollar is going, ensuring that the sum of your fractional expenditures does not exceed your total income.
Optimizing Savings: Understanding the Compounding Power of Small Increments
Savings, too, benefit immensely from fractional thinking. When aiming for a significant financial goal, such as a down payment on a house or retirement, the sheer size of the target can seem daunting. However, by breaking it down into smaller, manageable fractions – monthly or weekly contributions – the goal becomes attainable. “How many 1/3s do I need to save to reach my goal?” becomes the guiding question. Each regular contribution, no matter how small, is a fraction that accumulates over time. This also ties into the power of compound interest. A small fraction saved consistently today, earning interest, becomes a significantly larger fraction of your total wealth tomorrow. Understanding that these seemingly insignificant 1/3s add up to a substantial 3/4 (or even a whole) is key to sustained wealth accumulation. It’s the consistent allocation of a specific fraction of your income to savings and investments that builds genuine long-term financial security.
Investment Portfolios: Constructing Your Financial Future in Pieces
In the world of investing, fractional thinking is not just useful; it’s fundamental to understanding risk, return, and diversification. A diversified portfolio is, by its very nature, a collection of different “fractions” of assets, each contributing to the overall whole in a unique way.

Diversification as Fractional Ownership: Spreading Risk and Reward
Consider your investment portfolio as the “3/4” – your total investable capital. Diversification means not putting all your money into one type of asset (e.g., one stock or one bond). Instead, you allocate fractions of your capital to different asset classes: a fraction to large-cap stocks, another fraction to international equities, a fraction to bonds, and perhaps a smaller fraction to alternative investments. Each of these allocations is a “1/3” (or a 1/5, 1/10, etc.) of your total portfolio. The question “how many 1/3s are in 3/4” becomes: how many different fractional investments do I have, and what percentage (fraction) does each represent of my total portfolio? This strategic division helps mitigate risk. If one “1/3” (e.g., a specific stock sector) performs poorly, the other fractional investments can cushion the blow, preventing your entire “3/4” from being severely impacted. It’s about ensuring that your financial whole is robust, even if some of its parts experience volatility.
Calculating Returns and Distributions: Understanding Your Share of the Gains
Fractional thinking also extends to understanding investment returns and distributions. When you receive dividends from stocks or interest from bonds, these are often fractions of the underlying asset’s value or profits. If a company distributes 1/3 of its earnings as dividends, and you own 3/4 of the available shares, understanding “how many 1/3s are in 3/4” helps you quickly estimate your share of that distribution. More broadly, understanding your proportional ownership in a company (e.g., owning 0.1% of a large corporation) allows you to grasp the financial impact of broader corporate decisions or market movements on your fractional stake. Similarly, when evaluating the performance of an individual investment relative to your overall portfolio, you are engaging in fractional analysis: what fraction of my total return came from this specific asset? This level of detail allows for more informed portfolio adjustments and strategic rebalancing.
Debt Management and Goal Setting: Conquering Big Objectives, One Fraction at a Time
The journey to financial independence often involves tackling significant challenges, whether it’s paying down substantial debt or achieving ambitious savings goals. In both scenarios, fractional thinking transforms seemingly insurmountable tasks into manageable steps.
Deconstructing Debt: Tackling Liabilities in Manageable Slices
Debt can feel like an oppressive whole, a heavy burden that looms over one’s financial future. However, just as we break down an income into fractional expenses, we can apply the same logic to debt. Your total debt amount is the “whole.” Your monthly payment, or the extra principal you choose to pay, is a “1/3” or some other fraction. The question becomes: “How many of these monthly ‘1/3s’ do I need to pay to eliminate the total debt?” The debt snowball or avalanche methods are prime examples of fractional thinking. You tackle one fractional piece of debt at a time, celebrating the elimination of each “1/3” to gain momentum towards conquering the entire “3/4” (or total debt burden). This systematic approach makes the journey to becoming debt-free less daunting and more actionable, replacing a sense of being overwhelmed with a clear, step-by-step plan.
Building Wealth Incrementally: The Journey to Financial Independence
Similarly, monumental financial goals, such as saving for retirement or a child’s education, can seem impossibly large. But applying the “how many 1/3s are in 3/4” principle simplifies the process. Your retirement nest egg is the “3/4” you’re aiming for. Your annual or monthly savings contributions are the “1/3s.” By consistently contributing these fractions over time, you build towards your goal incrementally. Each contribution, each investment gain, each percentage of return, is a fraction that brings you closer to your financial independence. This understanding fosters patience and discipline, recognizing that significant wealth is rarely built overnight but is rather the cumulative result of countless fractional contributions and wise financial decisions made consistently over time. It’s the enduring power of small, consistent actions leading to massive long-term results.
The Mindset of Fractional Financial Literacy: Empowering Your Decisions
Ultimately, embracing fractional thinking transcends mere mathematical calculation; it cultivates a powerful mindset that empowers better financial decision-making. It shifts one’s perspective from viewing money as a monolithic entity to understanding it as a dynamic system of interconnected parts.
The Power of Perspective: Seeing the Whole Through Its Parts
When you can intuitively see “how many 1/3s are in 3/4” in your financial life, you gain clarity and control. You no longer see just a lump sum in your bank account, but understand it as a collection of allocated fractions for different purposes. You don’t just see a large investment gain, but can discern which fractional components of your portfolio contributed most significantly. This perspective allows you to identify inefficiencies, reallocate resources strategically, and pinpoint areas for improvement. It transforms a vague sense of financial standing into a precise, actionable understanding of where you are, where you’re going, and how each small part contributes to the bigger picture. This holistic view, built from an understanding of the parts, is invaluable for strategic financial planning.
Cultivating Financial Agility: Adapting to Changing Economic Landscapes
The ability to think in fractions also fosters financial agility. Economic landscapes are constantly shifting. Income might fluctuate, expenses can arise unexpectedly, and investment markets are volatile. When you understand your finances in fractional terms, you can quickly assess the impact of changes. If one “1/3” of your income is suddenly reduced, you can immediately identify which other “1/3s” (expenses, savings) need to be adjusted to maintain balance within your overall “3/4” (your financial reality). This adaptability is crucial for navigating recessions, capitalizing on opportunities, and ensuring your financial plan remains robust against unforeseen circumstances. It’s about having the mental models to quickly re-evaluate and reallocate, ensuring resilience in the face of change.
In conclusion, the simple question “how many 1/3 are in 3/4” serves as an enduring reminder of a fundamental principle applicable across all facets of finance. From meticulous budgeting and strategic investment diversification to aggressive debt reduction and ambitious goal setting, the ability to break down complex financial realities into their constituent fractions is an indispensable skill. It cultivates a powerful analytical mindset, fostering clarity, control, and resilience in an ever-evolving economic world. By embracing this fractional thinking, individuals can transform intimidating financial challenges into manageable tasks, paving a clearer path toward lasting financial success and independence.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.