
Starting a business is an exhilarating journey, filled with ambition, innovation, and often, a critical question: how do I fund this vision without significant upfront capital? The phrase “no money” can mean different things – perhaps you lack personal savings, collateral, or a track record of revenue. Traditional lenders typically favor applicants with a solid financial history, personal investment, and tangible assets. However, the entrepreneurial spirit isn’t always constrained by existing wealth. This guide will delve into strategies, alternative financing options, and critical preparations that can help aspiring business owners secure the funding they need, even when their pockets feel empty.
The Reality of “No Money” in Business Lending
When approaching financial institutions for a business loan, the concept of “no money” can be a significant hurdle. Lenders operate on risk assessment, and a lack of personal investment or collateral often signals higher risk. Understanding this fundamental dynamic is the first step toward overcoming it.
Why Lenders Seek Personal Investment
From a lender’s perspective, requiring a borrower to invest their own money, or provide collateral, serves several crucial purposes. Firstly, it demonstrates commitment and belief in the business venture. If an entrepreneur is unwilling to risk their own capital, why should a lender risk theirs? This “skin in the game” signals a higher likelihood of dedication and effort to ensure the business’s success and, consequently, the loan’s repayment. Secondly, personal investment or collateral mitigates the lender’s risk. In the unfortunate event of business failure, collateral provides a fallback mechanism, allowing the lender to recover some of their losses. Without these assurances, lenders perceive a much higher chance of default, making them less likely to approve a loan.
Defining “No Money”: More Than Just Cash-in-Hand
The term “no money” in the context of business lending is multifaceted. It doesn’t always strictly mean an entrepreneur has zero dollars in their bank account. More broadly, it can refer to a lack of:
-
Personal Capital: Insufficient savings or equity to inject into the business.
-
Collateral: No valuable assets (like real estate, equipment, or accounts receivable) that can be pledged to secure the loan.
-
Established Revenue: For existing businesses, a lack of consistent, strong cash flow can be seen as a form of “no money” in terms of fundability.
-
Strong Credit History: A poor personal or business credit score can be perceived as an inability to manage financial obligations, akin to not having “money” in terms of reliability.
-
Professional Track Record: Sometimes, a lack of experience or a proven track record in the specific industry can be a barrier, signaling higher risk.
Addressing these underlying factors, rather than just the literal absence of cash, is key to navigating the lending landscape effectively.
Laying the Groundwork: What You Can Offer Without Capital
While direct capital might be scarce, an entrepreneur still possesses invaluable assets that can strengthen a loan application significantly. These intangible assets often speak volumes to lenders about your potential for success and your commitment to the venture.
The Power of a Robust Business Plan
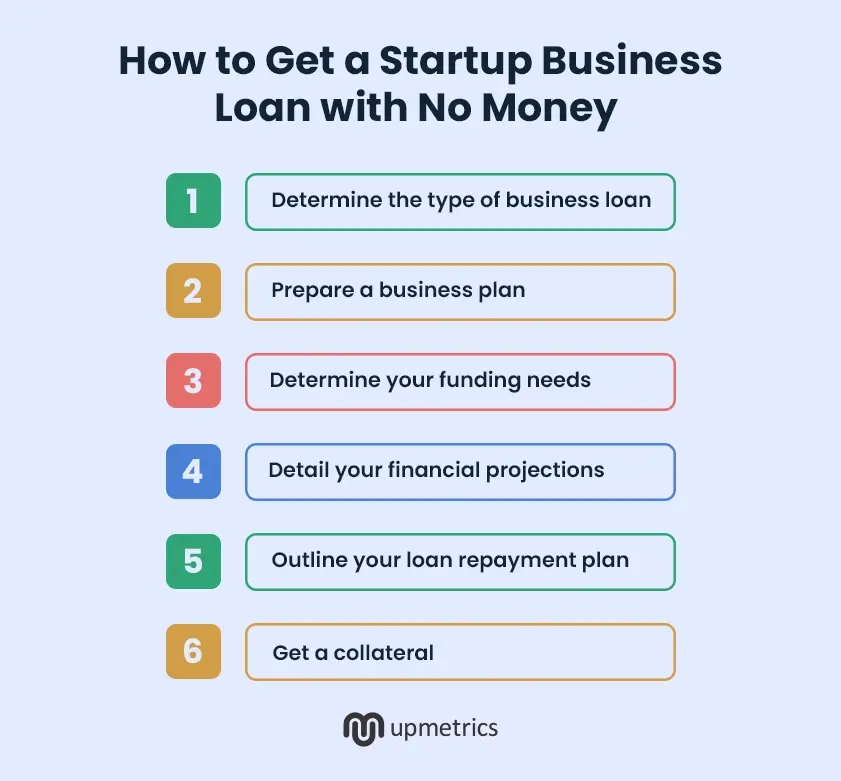
Your business plan is arguably the most critical document when seeking funding with limited personal capital. It serves as your roadmap and your primary tool for convincing lenders that your venture is viable and worth investing in. A well-researched and meticulously crafted business plan demonstrates:
-
Understanding of the Market: Deep insights into your target audience, competitors, and industry trends.
-
Clear Value Proposition: What problem your business solves and how it stands out.
-
Operational Strategy: A detailed outline of how the business will function day-to-day.
-
Marketing and Sales Plan: How you will acquire customers and generate revenue.
-
Financial Projections: Realistic and conservative forecasts of revenue, expenses, and profitability, even if based on initial assumptions. This section is particularly crucial as it shows the lender how their money will be used and repaid.
A compelling business plan can compensate for a lack of personal investment by showcasing your thorough preparation, strategic thinking, and the inherent strength of your business idea.
Personal Credit as Your Foundation
In the absence of business collateral or significant personal equity, your personal credit score becomes paramount. For startups or new businesses, lenders often lean heavily on the entrepreneur’s personal credit history to assess risk. A strong personal credit score indicates:
-
Financial Responsibility: You have a proven track record of managing debt responsibly and making timely payments.
-
Reliability: You are likely to honor your financial commitments, including loan repayments.
Before applying for any business loan, dedicate time to reviewing and improving your personal credit score. This might involve paying down existing debts, correcting any errors on your credit report, and ensuring all payments are made on time. A score above 680 is generally considered good, while scores above 720 are excellent and significantly improve your chances of approval.
Demonstrating Expertise and Commitment
Beyond financial metrics, lenders are keen to see the human element behind the business. Your expertise, experience, and unwavering commitment can be powerful persuaders.
-
Industry Expertise: Highlight any relevant experience you or your team members have in the industry. Deep knowledge can mitigate perceived risk, as it suggests you understand the challenges and nuances of the market.
-
Skills and Qualifications: Showcase any professional certifications, educational background, or specialized skills that are directly applicable to your business.
-
Vision and Passion: While less tangible, your enthusiasm and clear vision for the business can be contagious. Be prepared to articulate your mission, values, and long-term goals with conviction. Lenders want to see that you are not just chasing a quick profit, but building a sustainable venture you genuinely believe in.
By effectively showcasing these non-monetary assets, you can build a credible and compelling case for funding, even when starting with limited personal capital.
Exploring Non-Traditional and Alternative Funding Solutions
When traditional bank loans seem out of reach due to a lack of collateral or personal investment, a diverse landscape of alternative funding options becomes vital. Many of these avenues are specifically designed to support entrepreneurs who are rich in ideas but lean on capital.
Microloans and Community Development Financial Institutions (CDFIs)
Microloans are small, short-term loans, typically ranging from a few hundred to $50,000, often provided by non-profit organizations or CDFIs. These institutions are dedicated to serving economically disadvantaged communities and entrepreneurs who may not qualify for traditional bank loans. They prioritize community impact and often offer:
-
Flexible Lending Criteria: More lenient requirements regarding collateral and credit scores compared to traditional banks.
-
Business Support: Many CDFIs also offer technical assistance, mentorship, and business training to help borrowers succeed.
-
Focus on Underserved Groups: Often target women, minorities, veterans, and low-income individuals.
Organizations like Accion or Kiva are prominent examples, connecting aspiring entrepreneurs with the capital and support they need.
Government-Backed Loans (e.g., SBA Loans)
The U.S. Small Business Administration (SBA) doesn’t lend money directly but guarantees a portion of loans made by commercial lenders, reducing the risk for banks and encouraging them to lend to small businesses. SBA loans, particularly the SBA Microloan Program and some 7(a) loan options, can be a lifeline for businesses with limited collateral.
-
Reduced Lender Risk: The government guarantee makes banks more willing to lend.
-
Lower Down Payments & Flexible Terms: Often require less upfront capital and offer longer repayment periods than conventional loans.
-
Strict Eligibility: While more flexible than direct bank loans, SBA loans still require a solid business plan, good personal credit, and a demonstrated ability to repay.
Working with an SBA-approved lender is the way to access these programs, and they can guide you through the specific requirements.
Crowdfunding Platforms
Crowdfunding allows entrepreneurs to raise capital by soliciting small amounts of money from a large number of people, typically online. This can be an excellent option for businesses with compelling stories or innovative products that resonate with a wide audience.
-
Reward-Based Crowdfunding (e.g., Kickstarter, Indiegogo): Donors receive a product or service in return for their pledge. This is ideal for pre-selling products and gauging market interest without incurring debt.
-
Equity Crowdfunding (e.g., SeedInvest, StartEngine): Investors receive a small equity stake in the company. This is more akin to seeking angel investment but on a broader scale.
-
Debt Crowdfunding (e.g., Funding Circle, LendingClub): Lenders provide a loan that is repaid with interest, similar to a traditional loan but sourced from multiple individuals.
The success of crowdfunding often hinges on effective marketing, a strong narrative, and a clear presentation of your business idea.
Grants for Specific Industries or Demographics
Unlike loans, grants do not need to be repaid, making them highly desirable. While competitive, grants are available from government agencies, corporations, and foundations, often targeting specific industries, research areas, or demographics.
-
Federal Grants (e.g., SBIR/STTR for tech/research): Often focused on innovation and scientific development.
-
State and Local Grants: May target businesses that create jobs or contribute to local economic development.
-
Non-Profit and Corporate Grants: Many organizations support specific causes or entrepreneurial groups (e.g., women-owned businesses, minority-owned businesses).
Researching and applying for grants can be time-consuming, but the reward of non-dilutive capital is substantial.
Friends, Family, and Angel Investors
Leveraging your personal network can be one of the most accessible ways to secure initial funding. Friends and family might be willing to invest or lend money based on their belief in you, often with more flexible terms than traditional lenders.
-
Angel Investors: High-net-worth individuals who invest their own money in early-stage companies, often in exchange for equity. They typically look for high-growth potential and often bring valuable mentorship and connections.
-
Structured Agreements: Even with friends and family, it’s crucial to formalize the agreement with clear terms, outlining repayment schedules or equity stakes, to avoid future misunderstandings.
While not entirely “no money,” these sources often require less formal collateral and can be more receptive to early-stage ideas.
Equipment Financing and Invoice Factoring
For businesses with some operational history but limited cash, these options leverage existing assets or future revenue.
-
Equipment Financing: If your business needs specific machinery or technology, you can often secure a loan using the equipment itself as collateral. This allows you to acquire necessary assets without significant upfront capital, as the equipment secures the loan.
-
Invoice Factoring (Accounts Receivable Financing): If your business issues invoices to customers with delayed payment terms, you can sell those invoices to a factoring company at a discount for immediate cash. While not a loan, it provides working capital by accelerating your cash flow, essentially using your future income stream to fund current operations. These are particularly useful if your “no money” refers to a lack of liquidity rather than a complete absence of assets or revenue.
These alternative options require a proactive and strategic approach, often focusing on the strength of your idea, your personal commitment, and your ability to demonstrate future potential rather than solely relying on existing financial resources.
Strategies for Boosting Your Fundability Without Direct Capital
Securing a business loan with “no money” is as much about strategic preparation as it is about finding the right funding source. By proactively strengthening key areas of your business and personal profile, you can significantly enhance your appeal to lenders.
Cultivating a Strong Personal and Business Credit Profile
As mentioned, your personal credit is vital for startups. Continuously working to improve and maintain an excellent personal credit score should be a top priority. This includes:
-
Paying Bills on Time: Consistency is key for all credit accounts.
-
Minimizing Debt: Lowering your credit utilization ratio.
-
Reviewing Credit Reports: Regularly checking for errors and disputing them promptly.
Once your business is established and generates revenue, actively building a strong business credit profile becomes equally important. This involves:
-
Getting an EIN: Your Employer Identification Number is crucial for your business’s financial identity.
-
Opening Business Bank Accounts: Separating personal and business finances is fundamental.
-
Obtaining a DUNS Number: Many lenders use Dun & Bradstreet for business credit assessments.
-
Establishing Vendor Credit: Securing credit from suppliers and ensuring timely payments helps build your business credit history.
A robust credit profile, both personal and business, demonstrates financial reliability and reduces perceived risk, even in the absence of significant collateral.
Building a Network and Seeking Mentorship
The adage “it’s not what you know, but who you know” holds considerable truth in the entrepreneurial world. Your network can open doors to opportunities and advice that no amount of money can buy.
-
Networking Events: Attend industry meetups, conferences, and local chamber of commerce events to connect with potential mentors, partners, and even investors.
-
Mentorship Programs: Seek out experienced entrepreneurs or business leaders who can offer guidance, introduce you to valuable contacts, and help you navigate challenges. A mentor’s endorsement or connection can sometimes be more valuable than a high credit score to certain lenders or investors.
-
Advisory Board: Consider forming an informal or formal advisory board with individuals who bring diverse expertise to your business. Their collective wisdom and credibility can significantly enhance your business’s standing.
Strong relationships can lead to introductions to angel investors, grant opportunities, or even more flexible lending options from individuals who believe in your vision and your character.
Starting Small and Proving Concept (Bootstrapping)
Sometimes, the best way to get a business loan with “no money” is to generate some money yourself first. Bootstrapping involves funding your business primarily from personal finances or from the operating revenues of the new company.
-
Minimal Viable Product (MVP): Launching a basic version of your product or service to test the market and generate initial revenue or user engagement.
-
Freelancing or Side Hustles: Using income from other sources to self-fund initial business expenses.
-
Pre-Sales: Selling products or services before they are fully developed (as seen in reward-based crowdfunding).
By proving your concept, demonstrating early customer traction, and generating even a modest amount of revenue, you transform your “no money” situation into a “some money and proven concept” situation. This significantly improves your appeal to lenders and investors, as you’ve de-risked the venture to some extent.
Crafting a Compelling Pitch and Presentation
Even with a strong business plan, you need to be able to articulate your vision and value proposition concisely and persuasively. Whether it’s to a bank loan officer, an angel investor, or a crowdfunding audience, your ability to “sell” your idea is paramount.
-
Elevator Pitch: Develop a brief, engaging summary of your business that can be delivered in a minute or less.
-
Pitch Deck: Create a visual presentation that clearly outlines your problem, solution, market opportunity, business model, team, and financial projections.
-
Storytelling: Weave a compelling narrative around your business, explaining your motivation, the journey, and the impact you aim to create. People connect with stories, and a strong narrative can make your business memorable.
Confidence, clarity, and passion in your presentation can bridge gaps in your financial resources, conveying to potential funders that you possess the drive and vision to succeed.
Post-Funding: Responsible Financial Management
Securing a business loan, especially when starting with limited capital, is a significant achievement. However, it’s merely the beginning. Responsible financial management post-funding is crucial for the survival and growth of your business, ensuring you can meet repayment obligations and build a sustainable future.
Strict Budgeting and Cash Flow Management
Once funds are secured, establishing and adhering to a strict budget is paramount. Every dollar borrowed must be allocated strategically and tracked meticulously.
-
Detailed Expense Tracking: Categorize and monitor all expenditures to ensure they align with your business plan and projections.
-
Cash Flow Projections: Continuously forecast your cash inflows and outflows. Understand your burn rate (how quickly you’re spending money) and anticipate potential shortfalls to address them proactively.
-
Emergency Fund: Even with a loan, maintain a buffer for unexpected expenses or slower-than-anticipated revenue generation.
Effective cash flow management is the lifeblood of any business, particularly one that started with limited initial capital. It ensures you can cover operational costs, pay your employees, and meet your loan obligations.
Reinvesting Wisely for Growth
The purpose of a business loan is to fuel growth, not merely to stay afloat. Strategic reinvestment is essential to maximize the impact of the funds and generate future revenue streams.
-
Prioritize Growth Initiatives: Allocate funds to areas that will directly contribute to customer acquisition, product development, or operational efficiency improvements.
-
Measure ROI: For every significant investment, track its return on investment (ROI) to understand its effectiveness and inform future spending decisions.
-
Avoid Unnecessary Spending: Resist the temptation to splurge on non-essential items. Every dollar saved or strategically invested contributes to your business’s long-term health.
A disciplined approach to reinvestment ensures that your borrowed capital generates maximum value, paving the way for self-sufficiency and profitability.

Maintaining Lender Relationships
A business loan is a partnership. Nurturing a positive and transparent relationship with your lender is crucial for long-term success and potentially for future financing needs.
-
Open Communication: Keep your lender informed about your business’s progress, successes, and any challenges you might face. Transparency builds trust.
-
Timely Payments: Consistently make your loan payments on schedule. This reinforces your reliability and strengthens your business’s credit profile.
-
Financial Reporting: Be prepared to provide financial statements and updates as requested by your lender.
A good relationship with your initial lender can be an invaluable asset, making it easier to secure additional funding or more favorable terms down the line as your business grows and proves its worth.
In conclusion, while starting a business with “no money” presents formidable challenges, it is far from an impossible dream. By understanding the lender’s perspective, preparing a robust business plan, leveraging personal credit and expertise, exploring alternative funding channels, and committing to diligent financial management, aspiring entrepreneurs can secure the capital needed to transform their innovative ideas into thriving realities. The journey requires perseverance, strategic thinking, and a steadfast belief in your vision, proving that ingenuity can often be a more powerful asset than a hefty bank account.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.