
In the dynamic world of personal finance, few questions hold as much immediate relevance and financial weight for individuals and families as “What is the current interest rate on home mortgages?” This seemingly simple query unlocks a complex interplay of economic forces, individual financial health, and strategic decision-making that can profoundly impact one’s long-term financial stability and housing affordability. Mortgage interest rates are not static figures; they are living, breathing indicators of the broader economic climate, influenced by global events, domestic policy, and market sentiment. Understanding them is paramount for anyone considering buying a home, refinancing an existing mortgage, or simply planning their financial future.
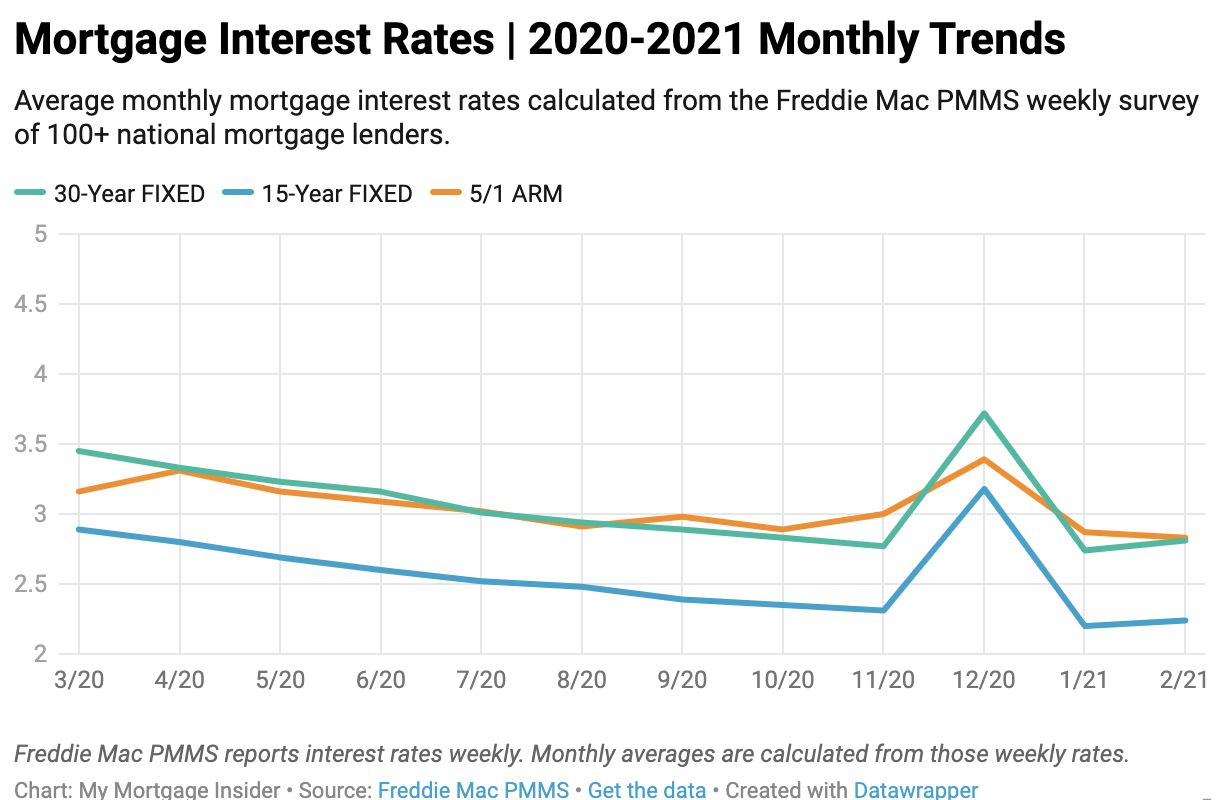
At any given moment, providing a single, definitive “current interest rate” is akin to trying to catch smoke. Rates fluctuate not just daily, but sometimes hourly, and vary significantly based on the lender, the borrower’s creditworthiness, the specific loan product, and prevailing market conditions. However, what we can do is provide a comprehensive framework for understanding what drives these rates, how to interpret them, and how to position yourself to secure the most favorable terms possible in the current economic landscape. This article will delve into the mechanics behind mortgage rates, explore different loan types, offer strategies for navigating the market, and discuss what influences their trajectory.
Understanding Mortgage Interest Rates in Today’s Market
The journey to understanding mortgage rates begins with recognizing their inherent volatility and the multitude of forces that sculpt them. While financial news outlets and online tools often report “average” rates, these are merely snapshots. A borrower’s individual rate can deviate significantly.
The Dynamic Nature of Rates
Mortgage rates are a product of supply and demand for credit in the broader economy. Lenders, who originate mortgages, borrow money themselves from capital markets or hold deposits from savers. The cost at which they can acquire these funds, combined with their operating expenses, desired profit margins, and an assessment of risk associated with lending, dictates the rates they offer. This makes the “current” rate a constantly moving target, susceptible to a myriad of external pressures. For instance, a major economic report, a shift in central bank policy, or even geopolitical developments can trigger immediate rate adjustments. Therefore, a prospective homeowner needs to think beyond a single number and understand the underlying mechanisms at play.
Key Factors Influencing Rates
Several powerful macroeconomic and market-specific factors exert influence over mortgage rates:
-
Federal Reserve Policy: The U.S. Federal Reserve, through its Federal Open Market Committee (FOMC), sets the federal funds rate, which is the target rate for overnight borrowing between banks. While not directly setting mortgage rates, changes to the federal funds rate ripple through the financial system, influencing the prime rate and other lending rates, including those for mortgages. When the Fed raises rates to combat inflation, it typically makes borrowing more expensive across the board.
-
Inflation: Perhaps the most significant driver of long-term interest rates, including mortgages, is inflation. Lenders demand a higher return on their money to compensate for the erosion of purchasing power over time. If inflation expectations rise, interest rates tend to follow suit. Conversely, low inflation can allow rates to remain subdued.
-
Economic Growth and Health: A strong economy, characterized by robust job growth and increasing consumer spending, often leads to higher demand for credit and, consequently, higher interest rates. Investors may pull money out of bonds (which typically move inversely to rates) to invest in riskier, higher-return assets like stocks. Conversely, an economic slowdown or recession typically sees rates fall as investors seek the safety of bonds and central banks often lower rates to stimulate activity.
-
Housing Market Supply and Demand: While less direct than the Fed or inflation, the health of the housing market itself can have an impact. High demand for homes, coupled with limited supply, can sometimes put upward pressure on rates as lenders recognize a strong market. However, more often, a hot housing market reflects broader economic strength, which is the primary driver.
-
Bond Market Performance (Specifically 10-Year Treasury Yield): Mortgage rates are closely tied to the yield on the 10-year U.S. Treasury note. When the yield on this benchmark bond rises, mortgage rates generally follow suit, and vice versa. This is because mortgage-backed securities (MBS) — which are bundles of mortgages sold to investors — compete with Treasury bonds for investor dollars. If Treasury yields go up, MBS must offer higher yields (and thus higher mortgage rates) to remain attractive.
Types of Mortgage Rates: Fixed vs. Adjustable
Navigating the mortgage landscape requires understanding the fundamental differences between the types of rates available. The choice between a fixed-rate and an adjustable-rate mortgage (ARM) has profound implications for a borrower’s monthly payments and overall financial risk.
Fixed-Rate Mortgages: Stability and Predictability
A fixed-rate mortgage is perhaps the most common and often preferred option for homeowners seeking stability. With a fixed-rate loan, the interest rate remains constant for the entire duration of the loan term, typically 15 or 30 years. This means your principal and interest payment will never change, regardless of how market interest rates fluctuate.
Pros:
-
Predictable Payments: Budgeting is easier as your monthly payment remains consistent.
-
Protection from Rising Rates: You are insulated if market rates climb significantly.
-
Simplicity: Generally easier to understand and manage.
Cons:
-
Higher Initial Rates: Fixed rates are often initially higher than introductory ARM rates, as lenders price in the risk of future rate increases.
-
Missed Opportunity if Rates Fall: If market rates decrease, you won’t automatically benefit unless you refinance.
Adjustable-Rate Mortgages (ARMs): Flexibility with Risk
An adjustable-rate mortgage (ARM) starts with an initial fixed interest rate for a set period (e.g., 3, 5, 7, or 10 years). After this initial period, the rate adjusts periodically, usually annually, based on a predetermined index (like SOFR – Secured Overnight Financing Rate) plus a margin set by the lender.
Pros:
-
Lower Initial Rates: ARMs typically offer lower introductory rates than fixed-rate mortgages, making them attractive for those planning to move or refinance before the adjustment period.
-
Benefit from Falling Rates: If market rates decrease, your ARM rate could also fall, potentially lowering your monthly payments.
Cons:
-
Payment Volatility: Your monthly payments can increase significantly if interest rates rise, making budgeting more challenging.
-
Complexity: ARMs can be more complex due to caps (limits on how much the rate can change per adjustment period and over the life of the loan) and different adjustment indexes.
-
Interest Rate Risk: The primary risk is that rates could rise substantially, leading to unaffordable payments, especially if the borrower’s income doesn’t keep pace.
Hybrid ARMs and Other Variations
Most ARMs today are “hybrid ARMs,” meaning they start with an initial fixed period (e.g., 5/1 ARM, 7/1 ARM). The first number indicates the number of years the rate is fixed, and the second number indicates how often the rate adjusts thereafter (e.g., annually). There are also specialized loans like FHA loans, VA loans, and USDA loans, which are government-backed and can offer more lenient qualification requirements or specific benefits, often with competitive rates within both fixed and adjustable structures.
How to Find the Best Mortgage Rate for You

Securing the best possible mortgage rate isn’t just about timing the market; it’s also about optimizing your financial profile and diligently comparing options. A fraction of a percentage point difference in your interest rate can translate into tens of thousands of dollars saved over the life of a loan.
Impact of Your Financial Profile
Lenders assess risk, and your financial profile is their primary indicator. The stronger your financial standing, the lower the risk you pose, and the more likely you are to qualify for preferential rates.
-
Credit Score: This is paramount. Borrowers with excellent credit scores (typically 740+) consistently receive the lowest rates. A strong credit history demonstrates your reliability in managing debt.
-
Debt-to-Income (DTI) Ratio: This ratio compares your total monthly debt payments to your gross monthly income. A lower DTI indicates you have more disposable income to cover mortgage payments, making you a less risky borrower. Lenders typically prefer a DTI below 43%, though it can vary.
-
Down Payment: A larger down payment reduces the loan amount and increases your equity from day one, which lowers the lender’s risk. Lenders often offer better rates to borrowers with substantial down payments (e.g., 20% or more), and it can also help you avoid private mortgage insurance (PMI).
-
Loan-to-Value (LTV) Ratio: This is the inverse of your down payment. A lower LTV (meaning you’re borrowing less relative to the home’s value) is favorable.
-
Loan Type and Term: As discussed, fixed vs. adjustable rates will yield different immediate rates. Shorter loan terms (e.g., 15-year fixed) typically come with lower interest rates than longer terms (e.g., 30-year fixed) because the lender is exposed to risk for a shorter period.
The Importance of Shopping Around and Comparing Lenders
One of the biggest mistakes borrowers make is accepting the first offer they receive. Mortgage rates, fees, and closing costs can vary significantly among lenders.
-
Get Multiple Quotes: Contact at least 3-5 different lenders – including large banks, credit unions, and online lenders.
-
Compare Apples-to-Apples: When comparing offers, focus on the Annual Percentage Rate (APR), which includes the interest rate plus certain fees and charges, giving a more complete picture of the total cost of the loan. Also, scrutinize closing costs and any lender fees.
-
Read the Fine Print: Understand any prepayment penalties, escrow requirements, and specific terms of the loan.
Utilizing Online Tools and Mortgage Brokers
Technology has made shopping for rates more transparent.
-
Online Rate Comparison Sites: Websites allow you to input your financial information and receive multiple rate quotes quickly. While a good starting point, these are often estimates.
-
Mortgage Brokers: A mortgage broker acts as an intermediary, working with multiple lenders to find you the best rates and terms. They can be particularly useful for complex financial situations or for gaining access to lenders you might not find on your own. Brokers are paid either by the lender or by the borrower (or both), so understand their compensation structure.
The Broader Economic Context and Future Outlook
Understanding the present also requires an eye on the future. Mortgage rates are not independent variables; they are deeply entwined with the health of the economy and central bank policy.
The Fed’s Role and Monetary Policy
The Federal Reserve’s actions, particularly regarding the federal funds rate and quantitative easing/tightening policies, are critical. When the Fed signals a commitment to fighting inflation through rate hikes, bond yields typically respond by rising, pulling mortgage rates up. Conversely, if the Fed indicates a pause or potential cuts due to economic weakening, rates often trend downward. Monitoring the Fed’s statements and economic projections (the “dot plot”) offers valuable insights into potential rate movements.
Inflationary Pressures and Their Effect
Persistent inflation remains a primary concern for lenders and central banks. As long as inflation remains elevated above the Fed’s target, there will be upward pressure on long-term interest rates like mortgages. Borrowers should pay attention to inflation data (Consumer Price Index, Producer Price Index) and how it’s trending, as this will heavily influence the Fed’s stance and, consequently, mortgage rates.
Expert Predictions and Market Volatility
Forecasting mortgage rates is notoriously difficult, even for seasoned economists. Market volatility, geopolitical events, and unexpected economic data can swiftly alter predictions. While various financial institutions and experts offer rate forecasts, it’s crucial to view them as informed opinions rather than certainties. They can provide a directional sense, but rarely pinpoint exact future rates. The key takeaway is that rates are subject to continuous adjustment, and flexibility in financial planning is often beneficial.
Strategies for Navigating High-Interest Rate Environments
When mortgage rates are elevated, potential homebuyers and those considering refinancing might feel discouraged. However, strategic planning can still make homeownership attainable and managing an existing mortgage more efficient.
Improving Your Financial Standing
Even in a high-rate environment, a strong financial profile can help mitigate the impact. Continue to focus on:
-
Boosting Your Credit Score: Pay bills on time, reduce credit card balances, and review your credit report for errors. Even a slight improvement can unlock better rate tiers.
-
Reducing Your DTI: Pay down other debts, such as car loans or student loans, to improve your debt-to-income ratio.
-
Saving a Larger Down Payment: A substantial down payment not only reduces your loan amount but also signals lower risk to lenders, potentially earning you a better rate.
Considering Shorter Loan Terms
While 30-year fixed mortgages are popular for their lower monthly payments, 15-year fixed mortgages typically come with significantly lower interest rates. If your budget allows for the higher monthly payment, a 15-year loan can save you a tremendous amount in interest over the life of the loan and build equity much faster. This can be a smart play, especially when 30-year rates are elevated.
The Potential for Refinancing Down the Line
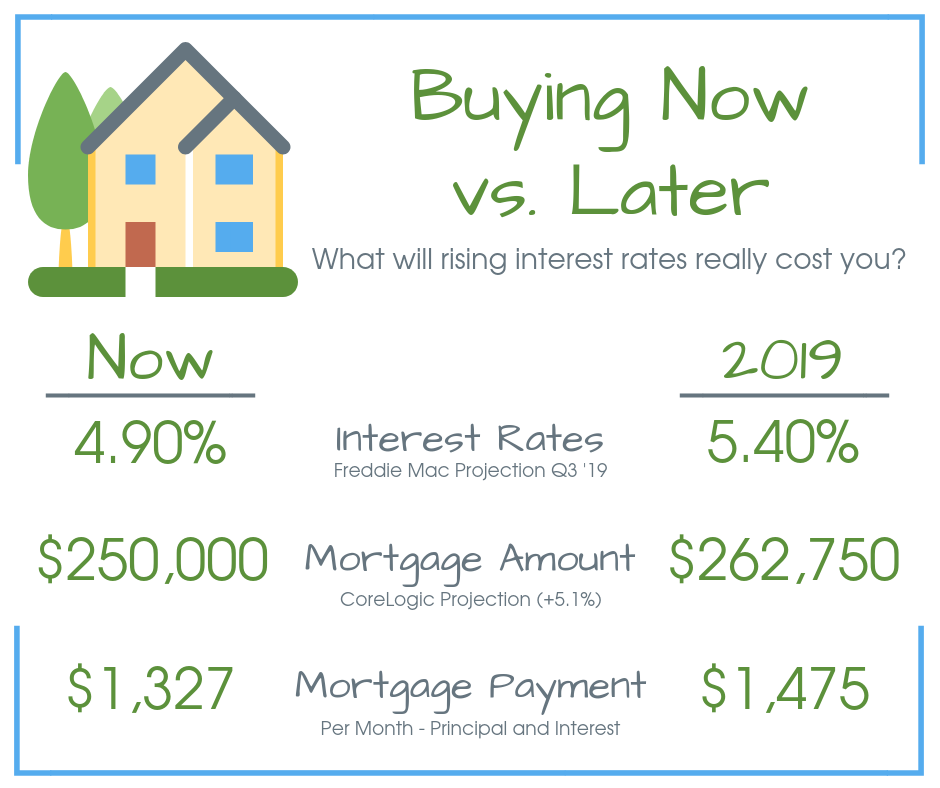
If you purchase a home in a higher interest rate environment using a fixed-rate mortgage, or if you opt for an ARM to take advantage of lower initial payments, you always have the option to refinance later if rates drop. Many borrowers use this strategy: secure a home with a manageable payment now, and keep an eye on the market for an opportunity to reduce their rate and payment in the future. Be mindful of closing costs associated with refinancing, and ensure the savings outweigh these upfront expenses.
In conclusion, understanding “what is the current interest rate on home mortgages” goes far beyond a single number. It involves grasping the economic forces at play, recognizing the different types of loan products, strategically preparing your personal finances, and diligently shopping for the best terms. While the market is constantly shifting, an informed and proactive approach remains your most powerful tool in navigating the journey to homeownership and financial stability.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.